With different plans, premiums, deductibles, and networks to consider, it's important to understand what you're actually getting before deciding. We'll help you compare your options in clear, straightforward language.

A message from Our CFO, John "JJ" Guillory
Health insurance is designed to help cover eligible healthcare expenses according to the terms of your policy or plan — from doctor visits and preventive care to hospital services and prescriptions.
Your premium, deductible, copayments, coinsurance, provider network, and out-of-pocket costs can vary depending on the plan you choose. Understanding these details can help you make a more informed decision.
Your ideal coverage may depend on your age, family size, healthcare needs, budget, location, and preferred doctors. When comparing plans, consider:
Monthly premium
Annual deductible
Copayments
Coinsurance
Out-of-pocket maximum
Provider networks
Prescription drug coverage
Plan limitations & exclusions
Looking beyond the monthly premium can help you better understand the overall cost and value of a plan.
Coverage designed for someone not receiving health coverage through an employer or group arrangement — useful if you're self-employed, between jobs, or working independently.
Coverage offered through private insurance companies and private-market options — look past the premium to the full picture.
Medical insurance is often used interchangeably with health insurance — both generally help pay for eligible medical and healthcare expenses. When comparing, look carefully at doctor & specialist coverage, hospital coverage, prescription coverage, preventive and emergency care, deductibles, copays, coinsurance, and provider networks.
A plan with a low premium may carry a higher deductible or other out-of-pocket costs — so it's worth looking at the total potential cost of coverage.
Consider the total potential cost of coverage — premiums plus expected healthcare expenses — not the premium alone.
A plan that looks inexpensive at first may not provide the coverage or network you need. When reviewing quotes, weigh the premium against the deductible, network, benefits, and out-of-pocket costs together.
These options can fill in gaps that a primary plan may not fully cover.
Temporary coverage for a limited period, with different benefits and eligibility requirements than comprehensive plans.
Helps cover eligible dental services — cleanings, basic and major procedures — often separate from your primary plan.
May help cover eligible medical expenses during international travel, when your domestic plan may have limited reach.
A tax-advantaged account for qualified medical expenses, available when paired with an eligible high-deductible health plan.
These plan types work differently and aren't interchangeable — compare carefully before choosing.
| Consideration | Medicare Advantage | Medicare Supplement (Medigap) |
|---|---|---|
| Offered by | Private insurers approved by Medicare | Private insurers, alongside Original Medicare |
| Structure | Bundles Medicare-covered benefits into one plan | Helps cover costs Original Medicare doesn't fully pay |
| Provider network | Often network-based | Generally works with any provider accepting Medicare |
| Extra benefits | May include added benefits, varies by plan | Focused on supplementing Original Medicare costs |
| What varies | Premiums, networks, copays, drug coverage, out-of-pocket limits | Plan options, premiums, coverage, eligibility rules |
General comparison for educational purposes. Medicare information here is not intended to replace official Medicare guidance.
Your healthcare needs can change throughout your life — as an individual, for your family, during a career transition, or in retirement.
Think about your expected medical care, prescriptions, doctors, and specialists.
Consider both your monthly premium and potential out-of-pocket expenses.
Review what services, medications, providers, and treatments are covered.
Consider whether your healthcare needs may change over the coverage period.
Explore our latest guides, articles, and educational resources to help you better understand health insurance.
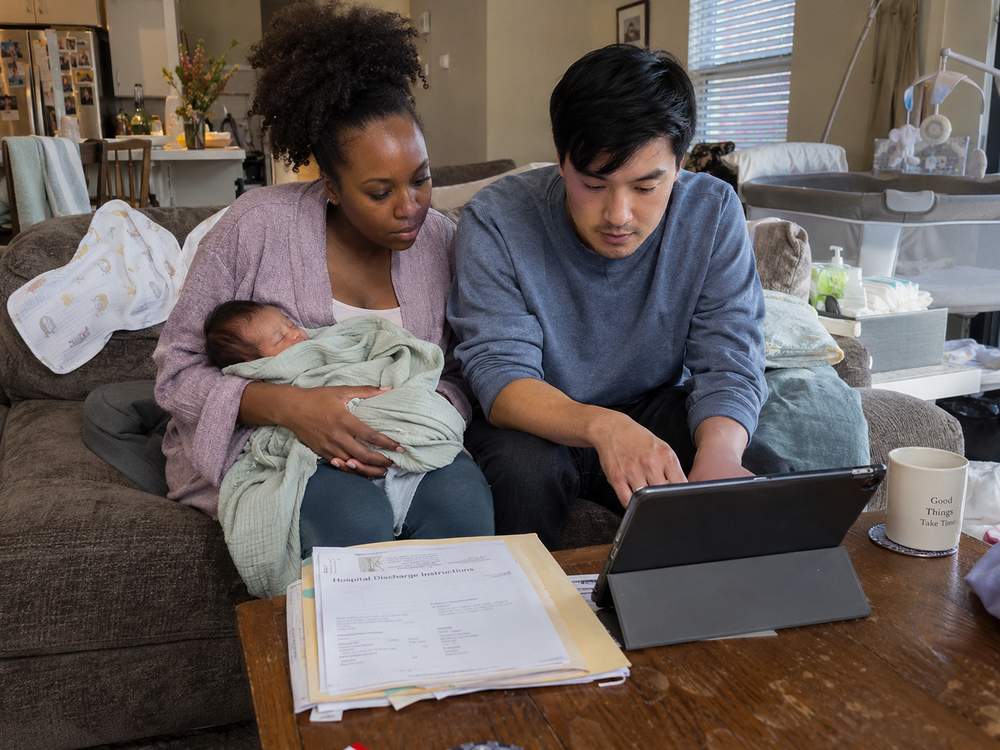
Learn how adding family members can affect premiums, deductibles, enrollment rights, provider needs, and the way a family health plan...
Read Article →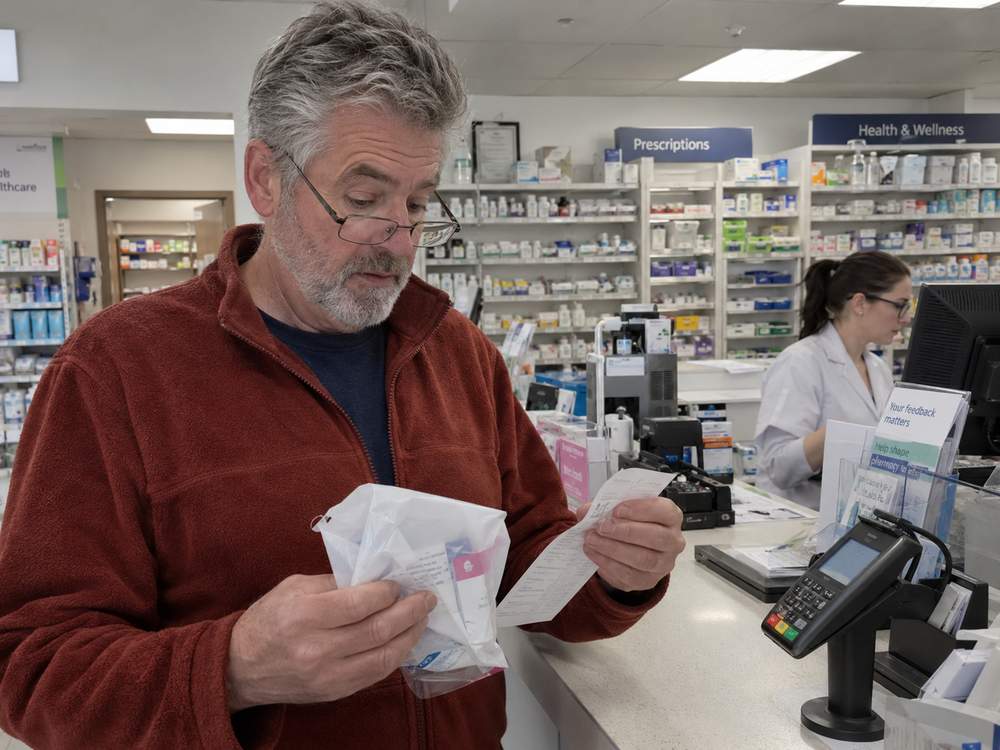
Understand formularies, drug tiers, prescription deductibles, and prior authorization so you can estimate medication costs before choosing a plan.
Read Article →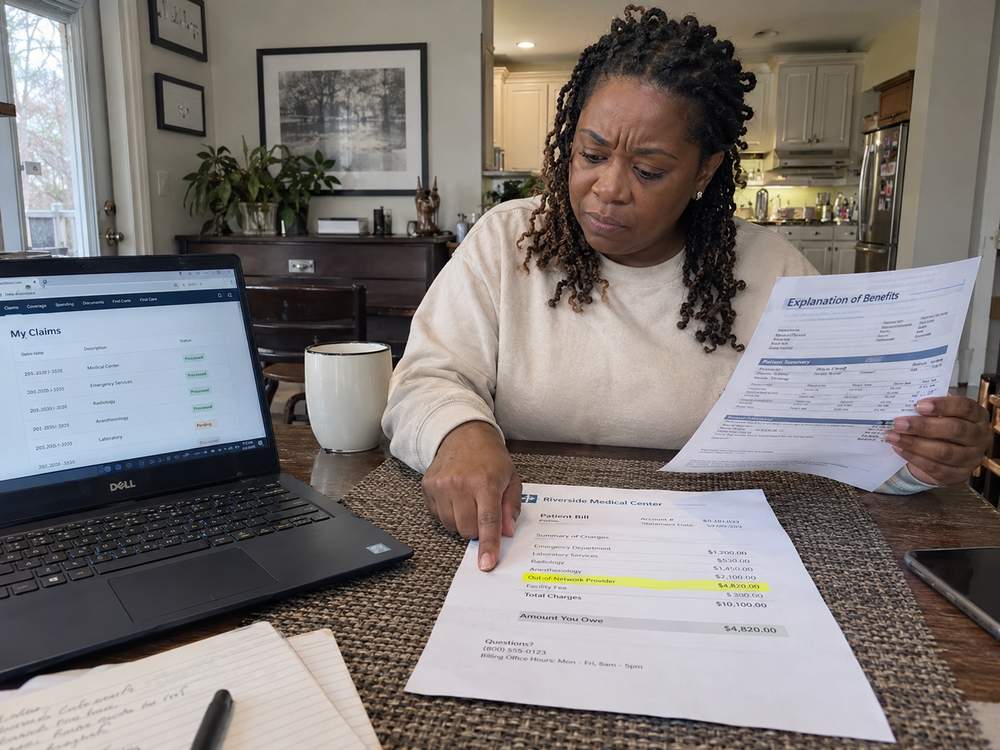
Learn how provider networks affect medical costs, when out-of-network bills can occur, and what federal surprise-billing protections may cover.
Read Article →
Learn why preventive care may be covered without cost sharing while diagnostic testing or follow-up services can result in a...
Read Article →
Learn what happens when you age off a parent’s health plan, when special enrollment may apply, and which coverage options...
Read Article →
Explore health insurance options for freelancers, consultants, and independent contractors, including Marketplace plans and income-based savings.
Read Article →Try a different search term.
We're committed to helping you understand your options with clear information and straightforward guidance.
Individual, private, short term, dental, travel, and Medicare coverage options.
Explore Health Insurance →Term, whole, and permanent coverage to protect the people who depend on you.
Explore Life Insurance →Turn retirement savings into a more confident, predictable income strategy.
Explore Annuities →Individual, private, affordable, short term, dental, travel, or Medicare coverage — we're here to help without unnecessary confusion.
No obligation. Just clear guidance on the coverage that fits your situation.