
Why Your Prescription Is “Covered” but Still Expensive: Formularies, Tiers, and Prior Authorization
A prescription can be listed as ‘covered’ and still cost far more than expected at the pharmacy. The reason is that prescription drug coverage is not a simple yes-or-no system. A plan’s formulary, drug tier, deductible, prior authorization rules, quantity limits, and pharmacy network can all change the amount a member pays.
The most useful way to compare plans is to check the exact medication before enrollment rather than assuming that ‘covered’ means inexpensive.
What a Health Insurance Formulary Is
A health insurance formulary is the plan’s list of covered prescription drugs. The formulary can also show the cost-sharing level for each medication. HealthCare.gov notes that plans may organize medications into different tiers, such as generic and brand-name levels, with different member costs.
A formulary can change, so the current plan-year list matters. The same medication can be preferred on one plan, nonpreferred on another, or excluded entirely from a third. The drug name, dosage, and formulation should all be checked.
Why Prescription Drug Tiers Matter
Many plans use multiple prescription drug tiers. A lower tier may contain preferred generics with a small copay, while higher tiers can include preferred brands, nonpreferred brands, and specialty drugs with much higher cost sharing. The exact number and meaning of tiers vary by plan.
A medication’s tier can be more important than the plan’s headline premium. Someone who takes an expensive drug every month can easily spend more on prescriptions than the amount saved by choosing a lower-premium plan.
A Prescription Deductible Can Delay the Lower Copay
Some health plans have a separate prescription deductible. Until that deductible is met, the member may pay much of the plan’s negotiated cost for certain medications. Other drugs may receive copay treatment before the deductible, depending on the plan.
This is why the Summary of Benefits and Coverage should be read together with the formulary. One document explains the broad prescription cost-sharing structure; the other shows where the specific drug sits inside that structure.
What Prior Authorization Insurance Rules Mean
Prior authorization is a plan decision that a service or prescription meets the plan’s medical-necessity requirements before coverage is approved. A medication can be on the formulary and still require prior authorization. The prescriber may need to submit clinical information or confirm that certain criteria are met.
Prior authorization is not a promise that the entire cost will be paid. Once approval is obtained, the normal deductible, copay, or coinsurance rules can still apply.
Step Therapy and Quantity Limits Can Also Affect Access
Some formularies use step therapy, which may require trying another covered medication before the plan approves a more expensive option. Quantity limits can restrict how much medication is covered during a defined period. Specialty drugs may also have special dispensing or monitoring requirements.
These rules vary significantly among plans. Someone taking regular medication should check not only the tier but also whether prior authorization, step therapy, quantity limits, or specialty-pharmacy rules appear next to the drug.
Preferred Pharmacy Networks Can Change the Price
The same medication may cost different amounts at different pharmacies because insurers negotiate preferred pharmacy networks. A plan may provide its lowest copay at certain retail pharmacies, through mail order, or through a designated specialty pharmacy.
Before enrollment, confirm that the pharmacy you actually use is preferred under the specific plan. A drug being covered does not guarantee that every pharmacy will charge the same member amount.
How to Compare Plans When You Take Regular Medication
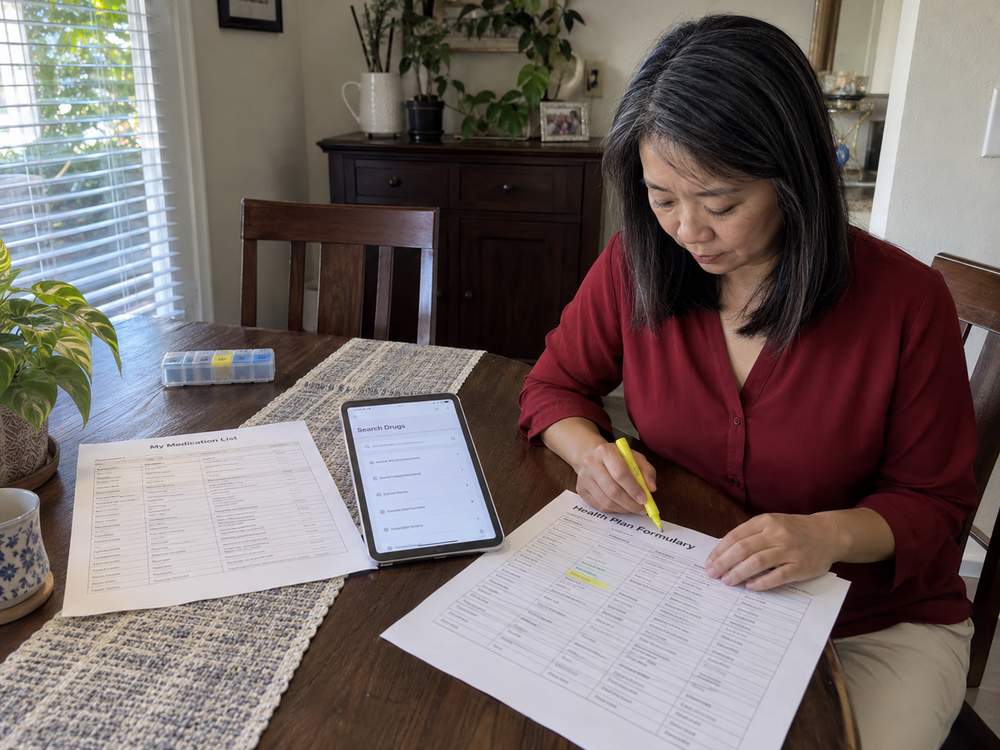
Create a simple list with the medication name, dose, frequency, and formulation. For each plan, check whether the drug is on the formulary, which tier it occupies, whether a prescription deductible applies, what the copay or coinsurance is, and whether prior authorization or another utilization rule is required.
Also check the preferred pharmacy. This process can reveal that a plan with a higher monthly premium actually costs less overall for someone with several ongoing prescriptions.
What to Do When a Drug Is Not Covered
If a medication is excluded or heavily restricted, contact the plan to ask about covered alternatives and the exception or appeal process. The prescribing clinician can decide whether a covered alternative is medically appropriate or whether an exception request should be submitted.
Do not change or stop a medication solely because of insurance cost without discussing the medical decision with the prescriber. The insurance question and the treatment question are related but not identical.
Formularies Can Change During the Plan Year
Drug lists are not always frozen forever. Plans can make formulary changes subject to applicable notice and consumer-protection rules, and a medication may move between tiers or be replaced by a preferred alternative. Members taking expensive medications should read plan notices and pharmacy messages instead of assuming last month’s price will remain unchanged.
If a change affects an important drug, contact the plan early to ask about transition rules, covered alternatives, prior authorization, or the exception process. Waiting until the pharmacy counter can leave very little time to solve the problem before the next dose is needed.
Use the Exception and Appeal Process When Appropriate
When a plan denies a prior authorization or excludes a medically necessary drug, the member may have an internal exception or appeal process. The prescriber may need to provide clinical reasons that the covered alternatives are not appropriate. The exact steps and deadlines are described in the plan documents and denial notice.
An appeal is not guaranteed to succeed, but it is part of the insurance process. Keeping copies of the denial, formulary page, medical records requested by the plan, and all call reference numbers makes the process easier to follow.
A Generic Drug Is Not Automatically the Lowest-Cost Choice on Every Plan
Generics are often placed on lower-cost tiers, but plan design still controls the member’s price. A preferred brand, biosimilar, mail-order option, or other negotiated arrangement can sometimes produce a different result. The pharmacy benefit should be checked rather than relying only on the generic-versus-brand label.
The goal is not to guess which drug should be used. The prescriber makes the treatment decision. The insurance task is to understand how the plan prices the options that are medically appropriate.
Do a Medication Audit Before Choosing the Plan
If regular medication is part of the household budget, compare prescription drug coverage before comparing small differences in premiums. Search each medication in the health insurance formulary, note its tier, and check whether a separate prescription deductible applies. The listed prescription drug tiers can change what you pay substantially, especially when a plan uses coinsurance instead of a fixed copay. Also check whether prior authorization insurance rules apply to the medication or to a preferred alternative.
Repeat the review for the exact dose and form prescribed, because a tablet, injection, or extended release version can be treated differently. Strong prescription drug coverage should be evaluated together with the pharmacy network and any mail order rules. If the health insurance formulary does not list a needed drug, ask about alternatives and the exception process before enrolling. Understanding the prescription deductible and prescription drug tiers before the first refill reduces the chance of a surprise at the counter. When prior authorization insurance requirements exist, knowing them early also gives the prescriber time to submit the necessary clinical information.
Frequently Asked Questions
What does formulary mean?
A formulary is the list of prescription drugs a health plan covers, often organized into cost-sharing tiers.
Why is a covered drug still expensive?
The medication may be on a higher tier, subject to a prescription deductible or coinsurance, filled at a nonpreferred pharmacy, or affected by other plan rules.
What is prior authorization?
Prior authorization is a plan requirement that certain clinical criteria be reviewed before the plan approves coverage for a service or prescription. It does not automatically eliminate the member’s normal cost sharing.
Check the Medication Before You Check the Box
Prescription drug coverage can vary dramatically between plans that otherwise look similar. A five-minute formulary check can be more valuable than comparing premiums alone. If a medication is important to your health, verify its tier, restrictions, deductible treatment, and pharmacy network before choosing the plan.