
Turning 26 and Losing a Parent’s Health Insurance? What to Do Before Coverage Ends
Turning 26 can turn a routine birthday into a health insurance deadline. Federal law generally lets young adults stay on a parent’s plan until age 26 when the plan offers dependent coverage, but the exact date coverage ends can depend on whether the parent has Marketplace coverage, an employer plan, and any state-specific rules.
The safest strategy is to start comparing young adult health insurance before the old card stops working. That gives time to confirm the end date, compare networks and premiums, and line up the new plan so there is no accidental coverage gap.
Why Age 26 Matters
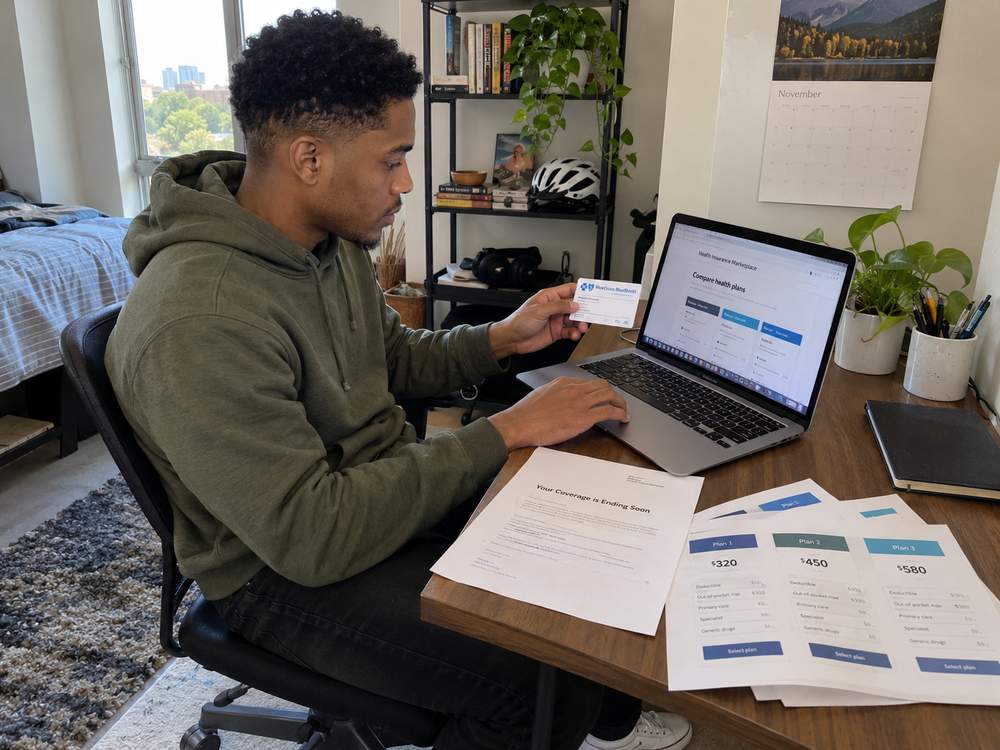
When a parent’s health plan covers dependents, a young adult can generally remain on that plan until turning 26. Current HealthCare.gov guidance says this usually applies even if the young adult is married, has a child, lives away from the parent, is no longer a student, or is financially independent.
That rule does not mean every plan uses the exact same termination date. The young adult should ask the plan or employer benefits department when coverage actually ends rather than assuming it ends at midnight on the birthday.
Find the Exact Date Your Parent Coverage Ends
For a parent’s Marketplace plan, current federal guidance says a dependent can stay covered through December 31 of the year they turn 26, or the later age allowed in the state. Job-based plans can handle the end date differently, so the employer or plan should be contacted directly.
The end date controls the enrollment timeline. Once it is known, the young adult can count backward and start applications before the existing coverage disappears.
Losing Parent Coverage Creates a Special Enrollment Opportunity
Turning 26 and losing qualifying coverage through a parent’s plan is a recognized Marketplace Special Enrollment event. The federal Marketplace currently allows enrollment within the applicable loss-of-coverage window, which generally includes time before and after the old plan ends.
That means aging off parents insurance does not require waiting for annual Open Enrollment. The new plan should still be selected early enough for the effective date and first premium payment to line up with the old coverage ending.
Option 1: Your Own Employer Coverage
If the young adult has a job that offers health insurance, the employer plan may be the simplest option. Compare the employee premium, employer contribution, deductible, provider network, prescriptions, and whether the plan offers an HSA or other benefits.
Loss of other coverage can also create special enrollment rights in a job-based plan. The deadline for employer enrollment can be shorter than the Marketplace window, so the HR department should be contacted as soon as the parent-plan end date is known.
Option 2: Marketplace Health Insurance
A young adult can compare Marketplace plans based on location, household, and tax status. Depending on income and household circumstances, premium tax credits can reduce the monthly cost. If someone else claims the young adult as a tax dependent, the subsidy calculation can involve the tax household rather than only the young adult’s personal income.
The plan should be checked for doctors, mental health providers, prescriptions, and any care needed near school or work. A low premium is not enough if the network is unusable.
Option 3: Medicaid or CHIP Where Applicable
A low-income young adult may qualify for Medicaid depending on the state and individual circumstances. Medicaid can be applied for throughout the year. CHIP is primarily designed for children and, in some states, certain pregnant individuals, so a 26-year-old generally looks first to Medicaid rather than CHIP for personal coverage.
The Marketplace application can screen for Medicaid eligibility while also showing individual-plan options.
Option 4: Student Coverage
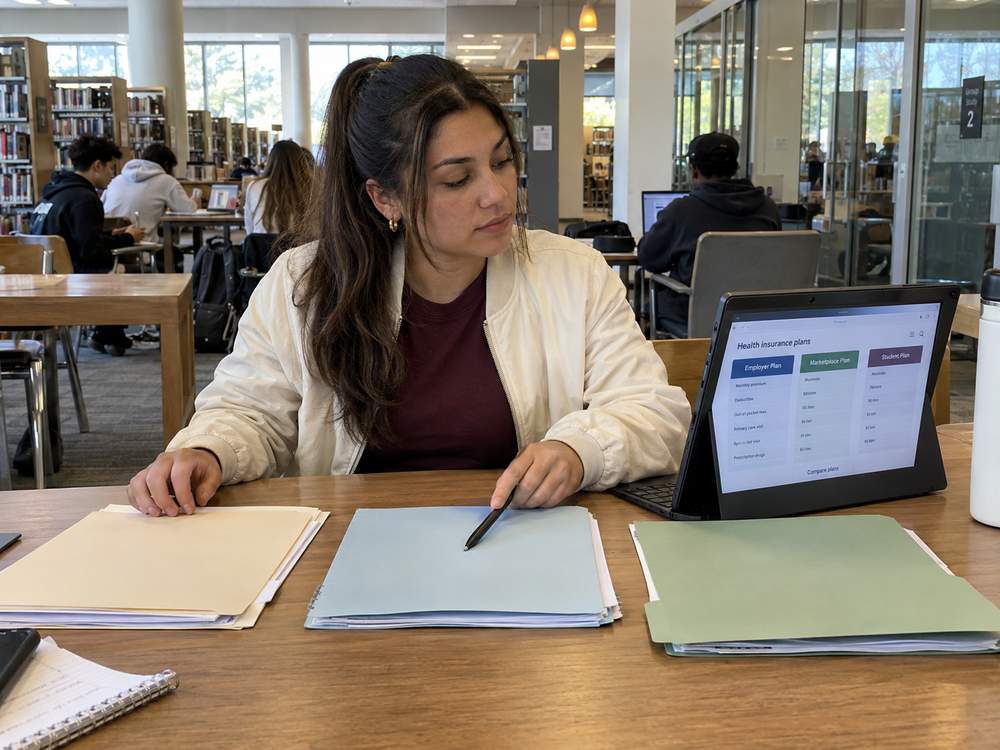
College and graduate students may have access to a school-sponsored health plan. Student coverage can be convenient, especially when the campus health system and local providers are included, but it should still be compared with Marketplace and employer options.
A student plan is not automatically the cheapest or broadest choice. Compare the premium, network outside the campus area, prescriptions, and whether the plan still works during breaks or travel.
Build a Simple Action Timeline
About 60 days before coverage ends, confirm the exact termination date and list your options. Thirty to forty-five days before the end date, compare premiums, doctors, prescriptions, and enrollment deadlines. Before the old plan ends, complete enrollment, submit any required documents, and pay the first premium if the new plan requires it.
After enrollment, download the new ID card, verify the effective date, and update doctors and pharmacies. Do not assume the new policy will automatically pay for care that occurred before its effective date unless the specific enrollment rule provides retroactive coverage.
Tax-Dependent Status Can Change Marketplace Savings
A 26-year-old can buy Marketplace coverage regardless of whether a parent helps with expenses, but subsidy eligibility depends on the tax household. If the young adult is claimed as someone else’s tax dependent, the Marketplace may need information about that household’s income rather than treating the young adult as a separate subsidy household.
That is why two people the same age with the same personal income can see very different Marketplace savings. Before applying, know whether someone expects to claim you as a tax dependent for the coverage year and answer the application consistently with that tax plan.
Under 30? Compare Catastrophic Coverage Too
People under 30 can generally consider Catastrophic Marketplace plans when they are offered in the area. These plans are designed mainly for worst-case protection and can have very high deductibles. They may appeal to someone who wants a lower premium, but they should still be compared with subsidized Bronze or Silver plans.
Premium tax credits generally cannot be used to lower the cost of a Catastrophic plan, so a metal-level plan can sometimes be cheaper after subsidies. Turning 26 is a good moment to compare the actual after-credit prices rather than assuming the Catastrophic label means the lowest-cost option.
Set the Replacement Coverage Date Before the Birthday
A practical turning 26 health insurance plan starts with the exact date the parent’s coverage will end, not simply the birthday itself. Once that date is confirmed, compare health insurance after 26 options early enough to avoid a gap. People researching aging off parents insurance should look at employer coverage, Marketplace plans, Medicaid where eligible, and student coverage when available. The best young adult health insurance choice depends on premium, deductible, provider network, prescriptions, location, and expected care.
The enrollment window also deserves attention. A special enrollment age 26 opportunity may apply when qualifying dependent coverage ends, but the timing rules still have to be followed. Keep the termination notice and any enrollment confirmation until the replacement policy is active. If you are aging off parents insurance, do not cancel or ignore the old coverage until you know its exact end date. A second turning 26 health insurance review about a month before the transition can confirm that the new plan is ready. That makes health insurance after 26 a planned handoff rather than an emergency search, and it gives more time to compare young adult health insurance options within the special enrollment age 26 window. A final turning 26 health insurance check should confirm the new effective date and the special enrollment age 26 deadline.
Frequently Asked Questions
Does my parents’ insurance always end on my 26th birthday?
No. Marketplace and employer plans can use different end dates, and state rules can vary. Confirm the exact date with the plan or employer benefits department.
Can I use the Marketplace when I turn 26?
Yes. Losing qualifying parent coverage at age 26 can create a Marketplace Special Enrollment Period, so you do not have to wait for annual Open Enrollment.
Can I stay on my parents’ insurance if I am married?
Generally yes until the plan’s age limit applies. Being married does not by itself remove a young adult from a parent’s dependent coverage before age 26.
Start Before the Old Coverage Ends
Health insurance after 26 is easier to manage when the decision begins before the birthday or termination date. Confirm when the parent’s plan ends, compare employer, Marketplace, Medicaid, and student options, and complete enrollment before a gap develops. Turning 26 is a deadline, but it is also a clear opportunity to choose coverage based on your own needs for the first time.