

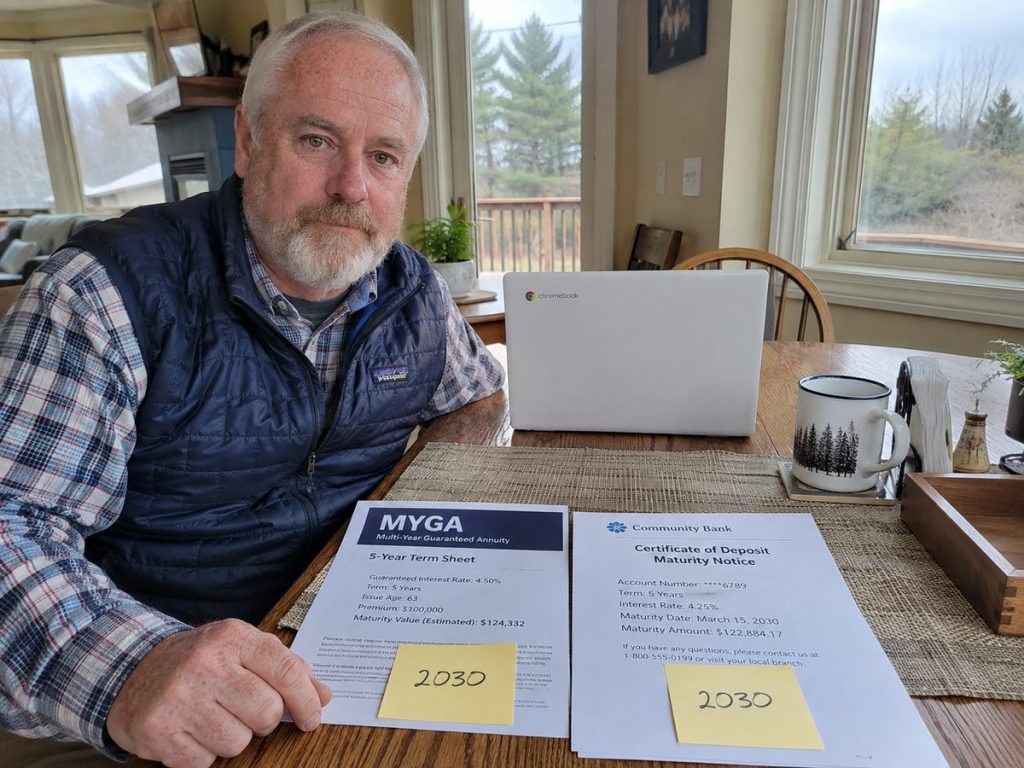
MYGA vs CD: A Rate Lock Is Only Part of the Comparison
A MYGA and a CD can look almost interchangeable on a rate sheet. Both may advertise a fixed rate for a specific number of years, and both appeal to savers who want less uncertainty than market-based investments. But a MYGA vs CD decision cannot be made from the percentage alone because the products are governed by different tax, liquidity, and insurance rules.
A MYGA, short for multi-year guaranteed annuity, is a type of fixed annuity issued by an insurance company. A CD is a deposit issued by a bank or credit union. The similar rate-lock idea is real, but nearly everything around that rate can work differently.
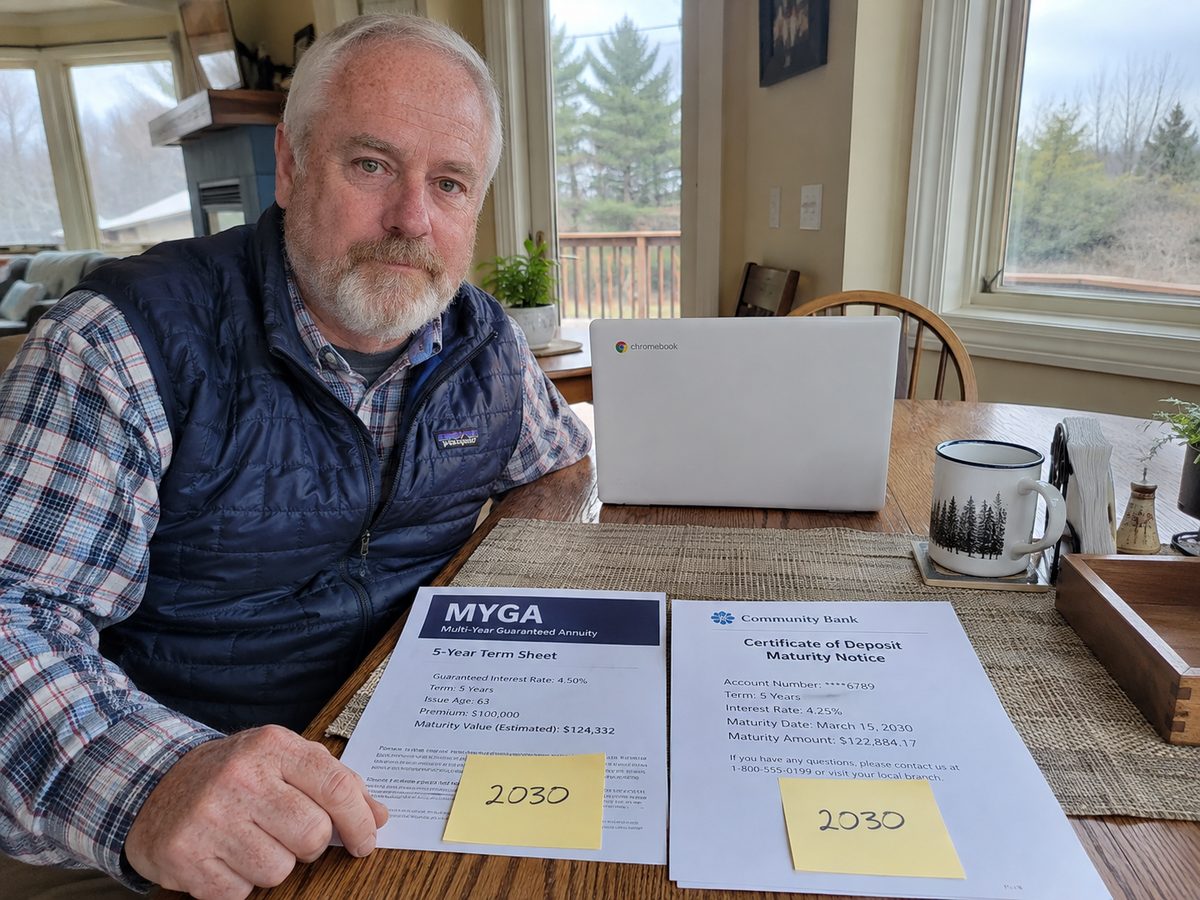
Where a MYGA and a CD Look Similar
Both products can offer a stated rate for a defined term. A three-year MYGA and a three-year CD may therefore be easy to compare at first glance. In each case, committing money for the full term is important because early access can trigger a financial cost.
That similarity explains why MYGA rates are often compared with CD rates. But the meaning of “term” should be checked carefully. For a CD, the maturity date usually ends the deposit term. For a MYGA annuity, the guaranteed-rate period and surrender-charge period may line up, but the contract should be read rather than assumed.
Tax Treatment Is One of the Clearest Differences
Interest from a CD held in a taxable account is generally taxable as it is earned or made available. Earnings inside a nonqualified MYGA funded with after-tax money generally accumulate tax-deferred until distribution. That deferral can matter over several years, especially if the owner does not need current income.
Tax deferral is not tax elimination. When earnings are distributed from a nonqualified annuity, they are generally taxed as ordinary income. Certain early distributions can also face an additional federal tax before age 59½ unless an exception applies. Tax treatment should therefore be considered alongside the rate, not treated as a free bonus.
Early Access Works Differently
A CD usually imposes a stated early-withdrawal penalty if money is removed before maturity. A MYGA can use a multi-year surrender schedule, often with a limited annual free-withdrawal provision. Some contracts can also use a market value adjustment, which may increase or decrease the amount received when money is surrendered under specified conditions.
The practical question is simple: If you unexpectedly need $20,000 in year two, what happens? Request the exact CD penalty and the exact MYGA surrender calculation. A slightly higher MYGA rate can lose its appeal if the money may be needed before the contract’s surrender period ends.
The Insurance Behind the Products Is Not the Same
A qualifying CD at an FDIC-insured bank receives federal deposit insurance within applicable limits and ownership rules. A MYGA is not FDIC-insured. Its guarantees depend on the financial strength and claims-paying ability of the insurance company that issues the contract.
State guaranty associations can provide protection for covered insurance claims if a licensed insurer fails, subject to state statutes and limits. This system is different from FDIC deposit insurance. Anyone considering a MYGA should therefore evaluate the insurer as well as the rate.
A Rate Lock Can Become an Opportunity Cost
Locking a rate creates certainty, but certainty has a price when market rates rise later. Someone who buys a five-year CD or five-year MYGA today may see new products offering more attractive rates two years from now. Leaving early can trigger penalties or surrender charges, so the original lock can become an opportunity cost.
The reverse can also happen. If rates fall, the locked rate may look increasingly attractive. Because nobody knows future rate movements with certainty, the decision should be based on a term the saver can realistically hold, rather than a prediction about what rates will do next.
What Happens at the End of the Term Matters
A CD typically matures into cash or renews according to the institution’s rules unless the depositor takes action. A MYGA reaches the end of its guaranteed-rate or surrender period, but the annuity contract may continue. The owner may have options to withdraw, renew, exchange, or continue under a new declared rate, subject to contract rules.
Review the end-of-term process before purchase. Find out whether there is a renewal window, what rate applies if no action is taken, whether a new surrender period begins, and how the contract can be transferred if the owner wants a different annuity.
A MYGA Ladder Can Spread Maturity Dates, but It Adds Complexity
Some savers divide money among MYGAs with different end dates rather than placing all funds into one contract. The idea is similar to a CD ladder: not all money becomes available at the same time, which can reduce the risk of locking every dollar at one rate.
That strategy is not automatically better. Multiple contracts mean multiple insurers, surrender schedules, beneficiary forms, and renewal dates. It also requires enough liquid savings outside the annuities for emergencies. A ladder is a planning structure, not a guarantee of higher returns.
Compare Renewal Rules Before the Original Rate Expires
The original MYGA rate is usually the easiest number to see, but the renewal process can matter just as much. Some contracts may offer a new declared rate after the guarantee period, while others give the owner a window to withdraw or transfer without a surrender charge. The contract should explain what happens if no instruction is given.
Ask whether renewal creates a new guarantee period, whether a new surrender schedule begins, and how much notice the insurer provides before the current term ends. The same questions apply to a CD’s automatic-renewal rules. A strong first-term rate can become less attractive if the owner misses a short decision window and the money rolls into terms they would not have chosen.
Frequently Asked Questions
Is a MYGA basically a CD from an insurance company?
No. The fixed-rate concept is similar, but a MYGA is an insurance contract with different tax rules, surrender provisions, protection systems, and potential annuity options. A CD is a bank or credit-union deposit.
Is a MYGA FDIC-insured?
No. Annuities are not FDIC-insured. A MYGA’s guarantees depend on the issuing insurance company, and state guaranty protections may apply subject to state rules and limits.
What happens when a MYGA term ends?
Options depend on the contract and may include withdrawing funds, accepting a renewal rate, exchanging to another annuity, or continuing the contract. Review the renewal and surrender provisions before the original purchase.
Compare the Whole Holding Period, Not Just Today’s Rate
A MYGA vs CD comparison is strongest when the rate is placed beside taxes, liquidity, insurance protection, and end-of-term choices. If the money can remain untouched and tax deferral is useful, a MYGA may deserve consideration. If deposit insurance and a conventional maturity structure are higher priorities, a CD may fit better. The rate is only one line in the decision.