

Moving an IRA to an Annuity: What Changes—and What Doesn’t—Tax-Wise
Moving IRA money into an annuity can sound like a tax strategy, but the first fact to remember is that the IRA is already tax-deferred. An IRA to annuity transfer changes the investment or insurance contract inside the retirement account; it does not create a second layer of tax deferral simply because the new asset is an annuity.
That distinction keeps the decision focused on the right questions. Does the annuity provide a guarantee, income feature, or risk profile that improves the retirement plan? How much liquidity will be lost? What will the contract cost? And can the transfer be completed without accidentally creating a taxable distribution?
Understand What ‘IRA to Annuity’ Usually Means
In many cases, the IRA remains the retirement account while an annuity contract becomes the asset held inside it. The annuity may be fixed, fixed indexed, variable, or designed primarily for income. A deferred annuity delays income until a later date, while other contracts can begin payments sooner.
Because the IRA wrapper remains important, the annuity must comply with applicable IRA rules. The insurer or custodian should be able to explain how the account is titled, how beneficiaries are recorded, how required distributions are processed, and which party handles tax reporting.
A Trustee-to-Trustee Transfer Can Keep the Process Cleaner
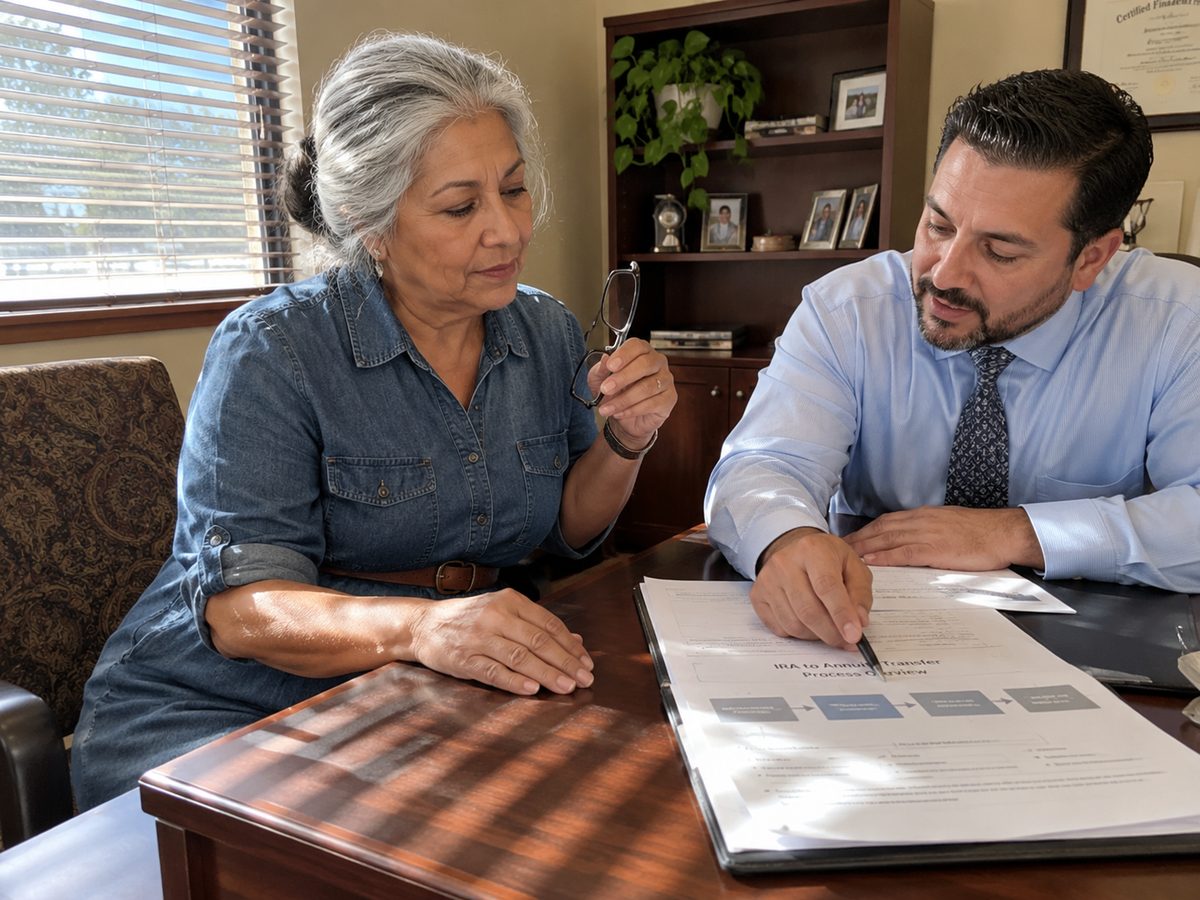
Current IRS guidance allows an IRA owner to request a trustee-to-trustee transfer in which the existing financial institution sends the money directly to the new IRA custodian or issuer. In a true trustee-to-trustee transfer, the owner does not take possession of the money and federal withholding generally does not apply.
This can be simpler than receiving an IRA distribution personally and attempting a 60-day rollover. Once money is paid to the owner, deadlines, withholding elections, and rollover rules become more important. Before moving an IRA, confirm whether the transaction will be processed as a direct transfer, rollover, conversion, or taxable distribution.
What Stays the Same After a Proper Transfer
If traditional IRA money moves properly into an IRA annuity, the qualified retirement-account tax status generally continues. The transfer does not make pre-tax money tax-free, and future taxable distributions are still governed by retirement-account rules. Required minimum distribution obligations also do not disappear simply because the IRA owns an annuity.
Beneficiary and early-distribution rules continue to matter as well. The contract can change how money is invested or paid, but it does not replace federal IRA law. That is why anyone asking how are annuities taxed should first identify whether the contract is qualified or nonqualified.
What Changes Is the Contract Around the IRA Money
Moving from mutual funds, bank deposits, or another investment into an annuity can change fees, surrender rules, investment choices, guarantees, and income options. A fixed annuity may offer a guaranteed rate. A fixed indexed annuity may use a market-linked crediting formula. A variable annuity may offer market-based subaccounts. An income-focused contract may emphasize future payments instead of flexible account access.
Those changes can be useful, but they can also reduce flexibility. An annuity account can have surrender charges or rider rules that do not exist in a conventional brokerage IRA. Review the contract as a new long-term commitment rather than assuming all IRA assets remain equally liquid.
Do Not Buy an IRA Annuity for Tax Deferral Alone
The NAIC’s annuity guidance specifically encourages consumers to ask what features other than tax deferral make an annuity appropriate, particularly when other tax-deferred opportunities are already available. That question is even more important inside an IRA because the account already defers tax.
A reasonable answer might be guaranteed lifetime income, a fixed interest structure, a specific downside-protection design, or an insurance feature that supports retirement income planning. If the only explanation is “your money grows tax-deferred,” the recommendation is incomplete.
Check RMD Compatibility Before Using a Deferred Annuity
Traditional IRAs can become subject to required minimum distributions under federal law. The applicable starting age depends on birth year and current rules. A deferred annuity inside an IRA should therefore be evaluated for how it handles required distributions once they begin.
Ask whether RMD withdrawals are treated as free withdrawals under the surrender schedule, whether they reduce an income benefit, and how the insurer calculates the amount attributable to the contract. If the IRA contains assets outside the annuity, the overall RMD may sometimes be managed across IRA holdings, but the tax and account rules should be confirmed for the specific situation.
Compare the Old IRA and the New Annuity Side by Side
List the current IRA’s annual costs, investment options, withdrawal flexibility, beneficiary setup, and service features. Then list the annuity’s premium, surrender period, rider charges, guaranteed values, investment or crediting options, and income provisions. This reveals whether the transfer improves a real part of the plan.
The comparison should also include what cannot easily be reversed. If the annuity introduces a long surrender schedule, the owner may be committed for years. If an existing IRA investment is sold to fund the annuity, returning to the old allocation later may require surrendering the contract or waiting until charges decline.
Keep Emergency and Near-Term Money Outside the Contract
Retirement income planning works better when long-term insurance products are not expected to handle every cash need. Before committing IRA assets to an annuity, identify money for near-term spending, taxes, healthcare, large purchases, and emergencies. The more restrictive the annuity, the more important outside liquidity becomes.
This is especially important close to retirement, when unexpected withdrawals can interfere with surrender schedules or guaranteed-income features. A contract can provide valuable certainty without needing to hold every retirement dollar.
Review Beneficiaries and Ownership Before the Transfer
An IRA annuity can introduce a new beneficiary form and a new insurer record, even when the retirement account remains an IRA. Confirm that primary and contingent beneficiaries match the intended estate plan and understand whether the insurer’s beneficiary election works together with the IRA custodial documents. Do not assume an old brokerage designation automatically carries over correctly.
Ownership also matters because an IRA generally must remain individually owned under retirement-account rules. If a proposal uses language about joint ownership, corporate ownership, or changing the annuitant, ask how that fits the IRA structure before signing. Administrative details can create tax or beneficiary problems even when the investment idea itself is reasonable.
Frequently Asked Questions
Does moving an IRA into an annuity create a tax bill?
A properly structured trustee-to-trustee transfer or eligible rollover can generally preserve the IRA’s tax-deferred status. A taxable distribution can occur if the transaction is handled incorrectly or involves a conversion or other taxable event.
Does an IRA annuity eliminate required minimum distributions?
No. Applicable RMD rules continue to apply to traditional IRA money. The annuity contract must be managed within those rules.
Why buy an annuity inside an IRA if the IRA is already tax-deferred?
The reason should be an insurance or planning feature, such as a guaranteed rate, lifetime-income option, or risk-management design. Tax deferral by itself is not an additional benefit inside an already tax-deferred IRA.
The Transfer Should Improve the Retirement Plan, Not Just Change the Account
An IRA to annuity move can make sense when the contract adds a feature the investor genuinely values. But the transfer should preserve the retirement account’s tax status, fit current RMD rules, leave enough liquidity, and justify its costs with more than tax deferral. The best comparison is between the IRA you already have and the exact annuity contract being proposed.