

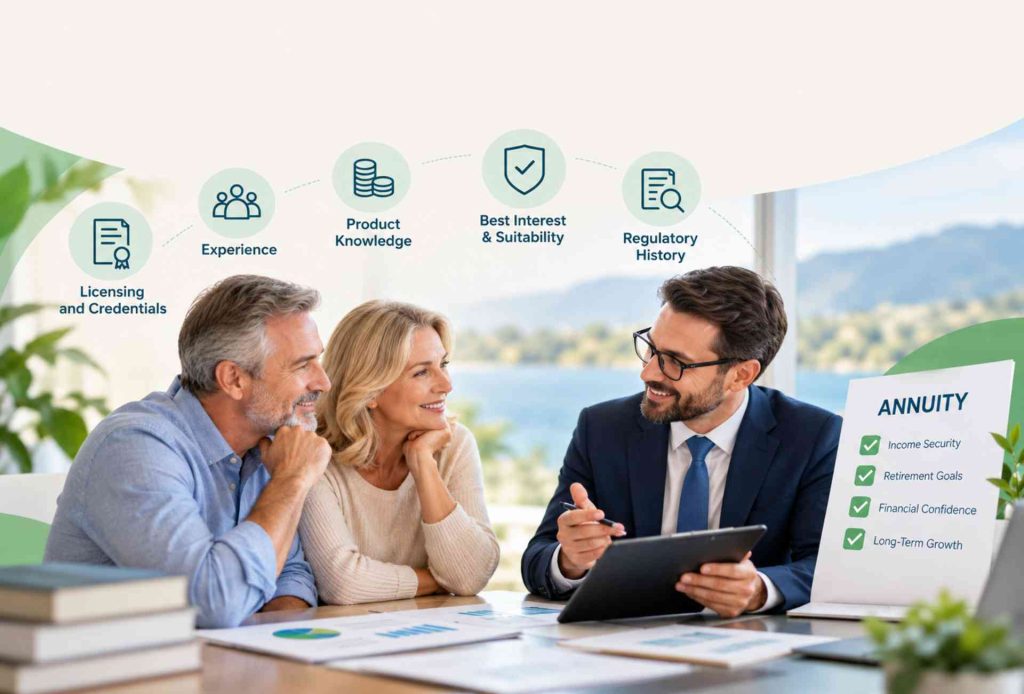
Choosing an Annuity Advisor: What to Look For
Choosing an Annuity Advisor: Why the Person Matters as Much as the Product
An annuity can be a useful retirement planning tool, but choosing one is only half of the decision. The person recommending it can influence how your needs are interpreted, which products you see, how trade-offs are explained, and whether the final annuity recommendation actually fits your circumstances.
With an advisor shaping your annuity decision, the selection becomes not just a matter of credentials but also a due-diligence exercise.
The regulatory framework reflects this concern. The National Association of Insurance Commissioners, or NAIC, has updated its annuity suitability model to require producers and insurers to make recommendations in the consumer’s best interest, subject to the rules adopted in each jurisdiction. The framework includes obligations involving care, disclosure, conflicts of interest, and documentation.
The practical lesson is straightforward: the quality of an annuity decision depends on both the contract and the person helping you evaluate it.
Start With the Advisor, Not the Annuity
Many consumers begin with the product.
They ask about a MYGA, fixed indexed annuity, variable annuity, income annuity, or another product category. A better starting point is to understand who is recommending the product and what role that person is legally and professionally authorized to play.
An advisor’s title alone does not answer that question. “Retirement specialist,” “wealth strategist,” or similar marketing descriptions do not necessarily tell you what licenses the person holds, what products they can recommend, how they are compensated, or what regulatory obligations apply to their activities.
The SEC advises investors to verify whether a financial professional is properly registered or licensed and to examine the individual’s background before working with that person.
Ask What the Advisor Is Licensed to Do
Annuity advisor licensing matters because professionals operate within different regulatory frameworks.
An insurance producer may be licensed to sell annuity contracts under state insurance law. A securities professional may also hold registrations that permit broader investment-related activities. An investment adviser may operate under SEC or state securities regulation.
These distinctions can affect the products and services available to you.
For this reason, you should ask a prospective annuity advisor:
- What licenses do you currently hold?
- Which states are you licensed in?
- Are you acting as an insurance producer, investment adviser, broker, or in another capacity?
- Which annuity products are you authorized to sell?
- Are you limited to products from particular insurers?
The answers help establish the boundaries of the relationship before a recommendation is made.
Experience Matters, But Verify It
An advisor can be licensed and still lack meaningful annuity advisor experience with the type of retirement decision you face.
Annuities contain contract-specific features that can require careful analysis. Surrender periods, withdrawal provisions, riders, interest-crediting methods, caps, participation rates, fees, income options, and death benefits can materially affect the economic outcome.
Experience should therefore be relevant, not merely impressive.
An advisor who primarily works with accumulation products may approach a lifetime-income question differently from someone who routinely helps retirees coordinate Social Security, pensions, investment portfolios, and guaranteed income.
The SEC recommends asking investment professionals about their experience, particularly experience working with people in circumstances similar to yours.
Ask for Specific Experience
Instead of asking, “How long have you been in the business?” ask more useful questions.
How often do you work with retirees? How frequently do you evaluate annuities? Which types do you commonly recommend? How do you compare annuity guarantees against liquidity and growth potential?
Specific questions produce more useful answers than broad claims about experience.
Product Knowledge Is Different from Product Access
An advisor may know an annuity well because they sell it frequently. That does not automatically mean it is appropriate for you.
There is an important distinction between annuity product knowledge and access to a broad range of alternatives.
An advisor affiliated with one insurer may have deep knowledge of that insurer’s products. Another advisor may have access to products from several carriers. Neither arrangement is automatically better, but the difference should be disclosed clearly.
The NAIC’s best-interest framework requires producers to understand the consumer’s financial situation, insurance needs, and objectives, and to consider the recommendation options available within their authority and license.
That means you should ask: “How broad is the universe of annuity products you can actually recommend?”
The answer may reveal an important limitation before you commit to anything.
Compensation Can Shape the Conversation
Annuity advisor compensation deserves direct discussion.
Annuity transactions can involve commissions or other forms of compensation. The existence of compensation does not automatically make a recommendation inappropriate. The important issue is whether compensation creates a conflict that could influence the recommendation.
The NAIC’s current best-interest framework specifically includes conflict-of-interest and disclosure obligations. Producers are expected to disclose relevant information about their role, compensation, and material conflicts under the applicable regulatory framework.
A straightforward advisor should be comfortable explaining how they are paid.
Ask: “How are you compensated if I purchase this annuity?”
After the answer, ask: “Would your compensation change if I selected a different annuity or another financial strategy?”
A clear answer is valuable evidence.
Regulatory History Deserves a Closer Look
A polished website tells you very little about an advisor’s regulatory history.
Fortunately, consumers can investigate financial professionals through public databases.
The SEC’s Investment Adviser Public Disclosure system, or IAPD, provides information about registered investment advisers and representatives. It can show registration status, professional background, and certain disciplinary information.
For brokers, FINRA BrokerCheck provides information about registration, employment history, qualifications, regulatory events, customer disputes, and other disclosures.
The SEC specifically recommends checking the background of investment professionals before entrusting them with investment decisions.
Look Beyond the Marketing Story
A regulatory disclosure does not automatically mean an advisor is unsuitable.
Context matters.
The important question is what happened, when it happened, how it was resolved, and whether there is a pattern of concerning conduct.
You should also check the appropriate state regulator because insurance licensing and insurance-related disciplinary information can involve state authorities.
This is an essential part of annuity advisor due diligence.
“Best Interest” Does Not Mean “Best Product in America”
The phrase annuity best interest can easily be misunderstood.
Under the NAIC model framework, acting in a consumer’s best interest does not mean the advisor must identify the single best annuity available anywhere in the market. It also does not simply mean choosing the product with the lowest cost, highest stated interest rate, or largest income payout.
The standard is more contextual.
The recommendation should be based on reasonable diligence, care, skill, and prudence, while putting the consumer’s interests ahead of the producer’s financial interests under the applicable regulation.
That distinction is important.
A higher income rate may be attractive, but it may come with a longer surrender period. A product with stronger liquidity may offer different accumulation economics. A rider may provide an appealing benefit while adding cost.
The advisor’s job is to explain those annuity trade-offs, not merely highlight the most attractive number.
Ask How the Advisor Reached the Recommendation
A strong annuity recommendation should have a logical chain behind it.
The advisor should understand your financial situation, insurance needs, financial objectives, liquidity requirements, existing assets, time horizon, and other relevant circumstances.
The NAIC model specifically identifies consumer profile information, insurer characteristics, product costs, rates, benefits, and features as factors relevant to determining whether an annuity addresses a consumer’s needs.
Ask three important questions.
First: “Why does this product fit my situation?”
Second: “What alternatives did you consider?”
Finally: “What would make you conclude that I should not buy this annuity?”
The last question can be particularly revealing.
The Right Advisor Should Make Complexity Easier
Annuities can be difficult to understand. Even regulators recognize their complexity. The NAIC continues to develop educational and regulatory materials focused on improving consumer understanding of annuity products and recommendations.
A good financial professional should therefore make complicated provisions understandable.
You should be able to explain, in your own words, what the annuity guarantees, what can change, what it costs, how much annuity liquidity you retain, how long your money may be committed, and what happens if your circumstances change.
If the explanation remains confusing after repeated questions, slowing down is reasonable.
Clarity is part of good advice.
The Person and Product Must Fit Together
Choosing an annuity is ultimately a matching exercise.
The product must fit the client’s objectives. The advisor must fit the complexity of the decision. The regulatory framework must fit the transaction. The compensation arrangement must be understood. The recommendation must have a defensible rationale.
That is why the advisor matters almost as much as the annuity.
A contract can contain attractive guarantees and still be inappropriate for a particular person. Conversely, an ordinary-looking product may serve a specific retirement objective well when its features, restrictions, costs, and risks are properly understood.
The real measure of an annuity advisor is therefore not how enthusiastically they present an annuity.
It is how carefully they help you decide whether you need one, which characteristics matter, what alternatives exist, and what trade-offs you are accepting.
A Better Way to Choose an Annuity Advisor
Before signing an annuity contract, investigate the person standing beside the product.
Verify licensing. Examine experience. Check regulatory history. Understand compensation. Ask about product access. Explore conflicts. Request an explanation of the recommendation and the alternatives considered.
Most importantly, make sure the conversation begins with your financial objectives rather than the advisor’s preferred product.
When your financial goals drive advisor recommendations, that is where a better annuity decision begins.
Educational and Financial-Information Notice
This article is intended to help readers evaluate the professional relationship surrounding an annuity decision. It does not endorse any advisor, insurer, annuity, or retirement strategy, nor does it determine whether an annuity is suitable for any individual. Licensing requirements, regulatory standards, compensation arrangements, and product availability can vary by jurisdiction and circumstance. Verify credentials with the appropriate regulators, review applicable disclosures and contract documents, and seek individualized advice from appropriately licensed professionals before making a financial decision.