

What Determines Your Annuity Check? Five Inputs Behind the Payment
Two people can put the same amount of money into an income annuity and receive different monthly payments. That difference is not random. The insurer is pricing a stream of payments based on the premium, the age of the person receiving income, when payments begin, how long they may need to continue, and which protections are added for a spouse or beneficiary.
That is why calculating annuity payments involves more than dividing a deposit by a number of months. An annuity payout calculator can illustrate the basic relationship, but the actual check depends on the contract and the payout election. Understanding the main inputs makes it easier to see why one option pays more each month while another offers more protection or flexibility.
Input 1: The Premium You Put Into the Contract
The starting premium is the most obvious input. All else equal, a larger premium can support a larger income stream. A $300,000 premium generally has more purchasing power for lifetime income than a $100,000 premium under the same pricing and payout terms. The relationship is not a simple universal multiplier because insurer pricing and options vary.
For planning, an annuity income calculator can help show how different premium amounts change estimated income. That exercise is useful when deciding how much of a retirement portfolio might be considered for guaranteed income while leaving enough liquid assets available for emergencies and other goals.
Input 2: Your Age When Income Begins
Age matters because a lifetime payment may need to continue for many years. When lifetime income begins at an older age, the insurer is generally pricing payments over a shorter expected period than when payments begin earlier. That can affect the payment amount, although actual pricing also depends on the product and market conditions at the time of purchase.
Age should not be treated as a reason to delay income automatically. Waiting may increase a future quote, but it also means giving up payments that could have been received earlier. The right start date depends on cash-flow needs, health, other retirement income, and the purpose of the annuity.
Input 3: One Life or Two
A single-life payout is designed around one annuitant. A joint-and-survivor option is designed to continue income while either of two covered people remains alive, subject to the contract. Because the insurer may have to make payments for a longer combined period, joint-life income is often lower than a comparable single-life payment at the same premium.
This trade-off can be important for couples. A higher single-life check may look attractive, but it may leave the surviving spouse with less income after the first death. The payment amount should therefore be evaluated together with the household’s need for survivor income.
Input 4: The Payout Guarantee You Select
Life-only income generally emphasizes the largest payment for the covered lifetime, but payments may stop at death with little or no remaining value for beneficiaries, depending on the contract. Period-certain or refund options can provide additional protection if death occurs early, but that added protection typically changes the payment amount.
For example, a life-with-10-years-certain option may promise payments for life while also ensuring that, if death occurs during the first ten years, remaining guaranteed payments continue to a beneficiary. A cash-refund or installment-refund feature may work differently. The specific wording matters, so payout illustrations should be compared line by line.
Input 5: Pricing Conditions and Insurer Assumptions
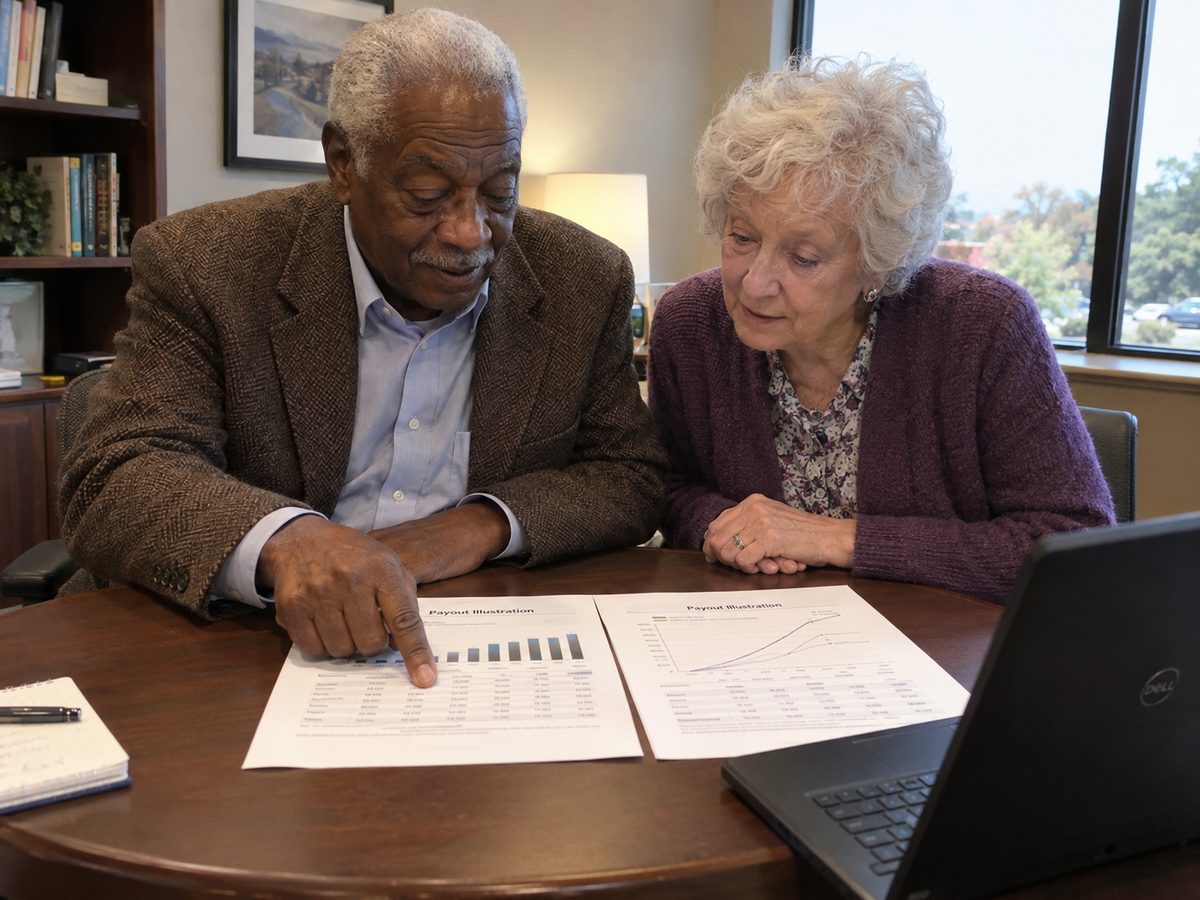
An immediate annuity quote also reflects the pricing environment when the contract is issued. Interest rates available to insurers, mortality assumptions, product expenses, and company pricing can all influence the amount offered. That is one reason quotes from two insurers can differ even when the customer, premium, and payout option are the same.
Quotes can also change over time. An estimate created months before purchase should not be treated as permanent. When income timing is near, obtain current illustrations from the insurers being considered and compare the same payout structure across each quote.
The Income-Start Date Can Change More Than One Variable
Starting income later can change a quote for more than one reason. The purchaser is older, the insurer is pricing at a later date, and a deferred contract may have accumulated additional value before payments begin. These effects should not be blended into a simple rule that waiting always produces a better outcome.
If income is needed now, delaying solely to chase a potentially larger future payment may create a cash-flow gap. If income is not needed for several years, deferral may be reasonable. The start date should be chosen around the retirement plan rather than around a single projected payment.
Payment Frequency Can Change the Way the Quote Looks
Monthly, quarterly, semiannual, and annual payments may be available depending on the contract. The annualized value may be similar, but the exact quoted payment can vary with payment frequency and timing. Retirement budgeting usually works best when the payment frequency is coordinated with recurring household expenses.
Do not confuse payment frequency with payout duration. Monthly income for life is very different from monthly income for a fixed ten-year period. When using an annuity payout calculator, confirm whether the tool is modeling lifetime income, a period-certain payment, or a simple withdrawal schedule.
The same discipline applies when using an annuity income calculator. If the tool quietly changes from lifetime income to a fixed-period payout, the resulting monthly amount may look higher while providing a very different promise. Always confirm the payout duration before comparing numbers.
A Simple Comparison Shows Why the Check Changes
Imagine two retirees with the same premium. Retiree A chooses single-life income with no period-certain feature. Retiree B chooses joint lifetime income covering a spouse and adds a guarantee period. Retiree B may receive a lower monthly amount because the contract is designed to support a potentially longer payment period and additional beneficiary protection.
Neither choice is automatically better. The higher payment may fit someone whose household has other survivor resources. The lower payment with stronger continuation features may fit a couple that depends on the annuity for essential expenses. The amount of the check is meaningful only when viewed beside what the payment is required to do.
When comparing quotes, hold the inputs constant. Use the same premium, ages, start date, payment frequency, and survivor or guarantee features. Otherwise, a larger payment may simply reflect a less protective payout option rather than better pricing.
Frequently Asked Questions
Does age affect annuity payments?
Yes. Age at the time income begins is one factor insurers use when pricing lifetime payments. Older starting ages may produce different payment levels than younger starting ages, but the final amount also depends on premium, payout option, insurer pricing, and other terms.
Why does joint-life income usually differ from single-life income?
A joint-life option may need to continue payments across two lifetimes. That potentially longer obligation can reduce the starting payment compared with a similar single-life option.
Can the monthly payment change after income begins?
It depends on the contract. Traditional fixed immediate annuity payments may remain level, while some products offer increasing, variable, or inflation-related payment features. Confirm whether the selected payment is fixed or can change.
Compare the Payment With the Promise Behind It
The largest monthly check is not always the strongest retirement choice. Premium, age, income-start date, single-versus-joint coverage, and beneficiary protections all shape the payment. Before choosing an option, compare both the dollar amount and the obligation the insurer is taking on. That is the clearest way to understand why the checks differ.
Educational note: This article provides general information and is not individualized tax, legal, investment, or insurance advice. Product terms vary by insurer and contract. Guarantees depend on the claims-paying ability of the issuing insurance company.