

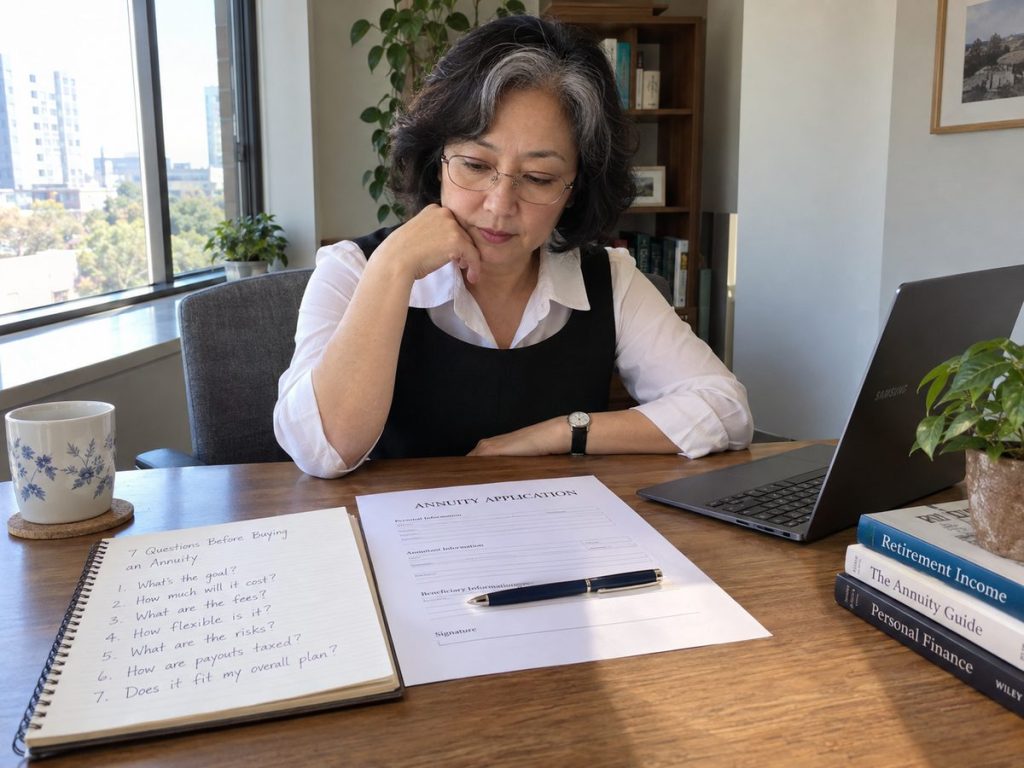
Before You Buy an Annuity, Answer These Seven Questions First
The hardest part of deciding whether to buy an annuity is often not understanding the word annuity. It is deciding whether a particular contract solves the financial problem you actually have. A product can sound attractive because it offers a guaranteed rate, market-linked interest, or lifetime income, yet still be a poor fit if the money may be needed sooner, the fees are misunderstood, or the contract duplicates benefits you already have.
Before comparing the best annuities or choosing among annuity companies, slow the decision down. The seven questions below force the conversation away from marketing language and toward purpose, liquidity, guarantees, costs, and trade-offs. A good annuity advisor should be able to answer them clearly and show where the answers appear in the contract documents.
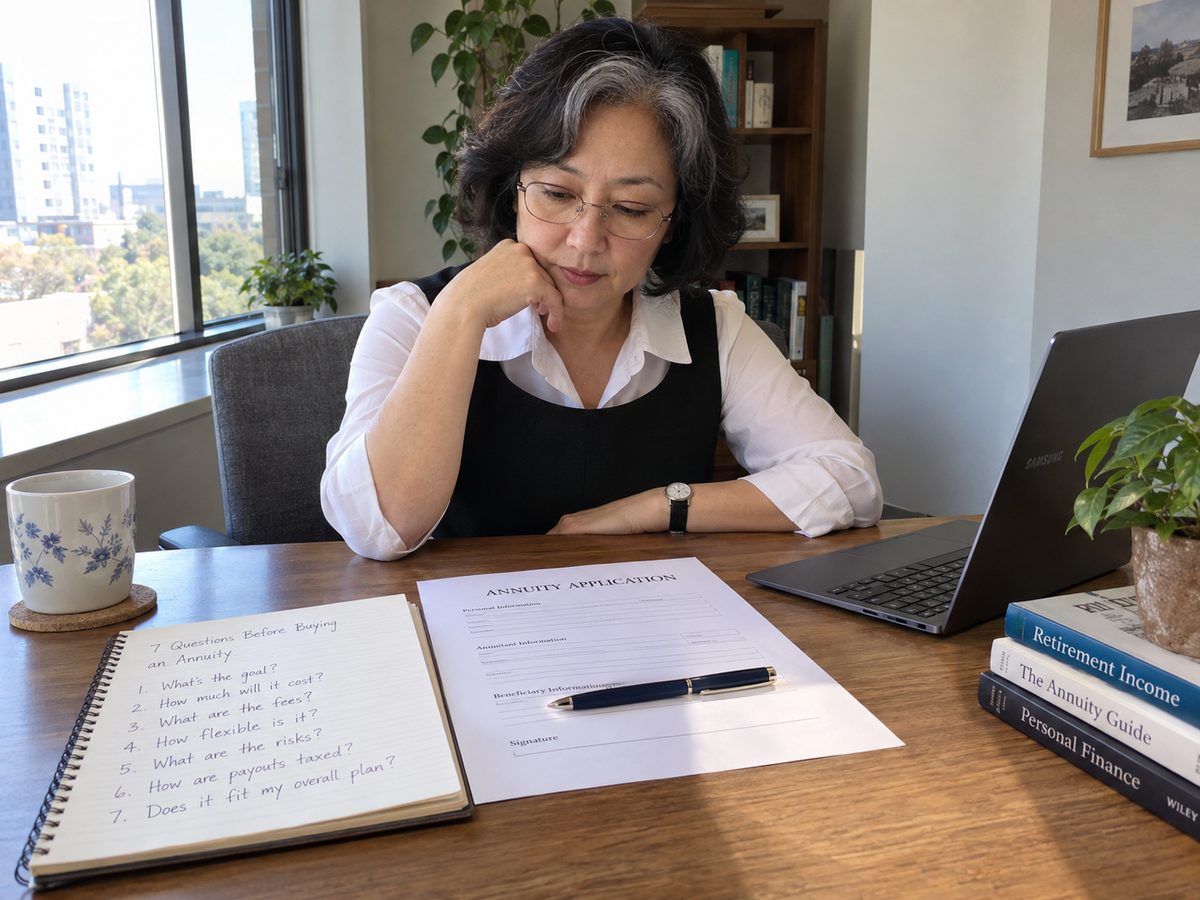
Seven Questions to Answer Before You Sign
1. What financial problem am I trying to solve?
Start with the job, not the product. Are you trying to create predictable retirement income, protect part of your savings from market loss, lock in a fixed rate for a period, or defer income until later? Those are different goals. An immediate income annuity may fit a person seeking current income, while a fixed deferred annuity serves a different purpose. If you cannot state the problem in one sentence, it is too early to choose a contract.
2. When might I need access to this money?
Annuities are long-term contracts. Many include surrender periods during which withdrawals above a permitted amount can trigger a charge. Some contracts may also use a market value adjustment or other provision that changes the amount received on an early withdrawal. Keep emergency savings and near-term spending needs separate from money committed to a long-term annuity unless the contract’s liquidity features genuinely match those needs.
3. Exactly what is guaranteed, and who guarantees it?
A guarantee should be defined precisely. It may apply to a fixed crediting rate, a minimum value, a lifetime-income formula, or another contract feature. Other values may be non-guaranteed. Insurance guarantees depend on the claims-paying ability of the issuing insurer, so the name of the distributor or advisor does not replace the need to identify the legal insurance company behind the contract.
4. What fees, spreads, caps, or other limits affect the result?
The cost structure depends on the annuity type. A variable annuity may have contract charges, underlying investment expenses, and optional rider fees. A fixed indexed annuity may use caps, participation rates, spreads, or other crediting rules that limit how much index growth is credited. A fixed annuity may look simpler but still has surrender provisions and contract-specific conditions. Ask for a complete explanation of both explicit charges and growth limitations.
5. How long is the surrender period, and what can I withdraw without a charge?
Read the surrender schedule year by year. Do not rely on a verbal description such as ‘you can always get your money.’ Many contracts allow some withdrawals without a surrender charge, but the percentage, timing, and calculation vary. Tax consequences can apply even when the insurer does not charge a surrender fee. If the contract may be replaced later, a new surrender period can also begin with the replacement contract.
6. What happens if I die before using the money?
Beneficiary provisions vary widely. Some deferred annuities provide a death benefit based on contract value or another defined amount. Income annuities may offer life-only, period-certain, joint-life, or refund features. Adding beneficiary protection can reduce the amount of current income available in some payout designs. Confirm who is named, what they would receive, and whether the contract requires any action to keep beneficiary information current.
7. Why is this contract better for this goal than the alternatives?
A recommendation should survive comparison. Depending on the objective, alternatives might include Treasury securities, CDs, bond funds, a diversified portfolio, delaying Social Security, keeping more cash, or using a different type of annuity. The point is not that one alternative is always superior. It is that the annuity should earn its place in the plan through a feature you actually need rather than through a sales illustration alone.
Documents to Request Before Buying
Ask for the product disclosure, current illustration or quote, surrender schedule, current rate sheet when relevant, rider information, and the insurer’s legal name. Variable and registered products may also have prospectuses and investment-option information. Read documents that explain what is guaranteed separately from assumptions used in an illustration.
Also ask how the person recommending the contract is compensated and whether the professional can compare products from multiple insurers. Compensation does not automatically make a recommendation inappropriate, but understanding incentives helps you evaluate the advice. If an annuity is replacing another annuity or life-insurance contract, compare old and new guarantees, fees, surrender periods, and tax consequences before giving anything up.
Red Flags That Deserve More Questions
Be cautious when a recommendation depends on urgency rather than explanation. Phrases such as ‘you must act today,’ ‘there is no risk,’ or ‘this is better than the market’ oversimplify a long-term insurance contract. Another warning sign is a recommendation to place nearly all liquid savings into an annuity without discussing emergencies or near-term expenses.
Likewise, do not accept a promise that the highest advertised rate makes one contract automatically superior. Rates can apply for different periods, and indexed products can use different crediting formulas. The best annuities for one household can be unsuitable for another because age, liquidity, income needs, state availability, tax status, and existing assets differ.
Use the Free-Look Period as a Second Review
After a contract is delivered, read it again while the free-look period is still open. Compare the issued policy with the illustration and application you reviewed before purchase. Check the premium amount, ownership, beneficiaries, surrender schedule, riders, and income provisions. If something is different from what you expected, contact the insurer and the professional immediately rather than waiting until the review period has passed.
Keep copies of the signed application, disclosure forms, illustration, rate sheet, and the final contract. These documents become the reference point years later if you need to understand a renewal rate, a withdrawal provision, or a beneficiary election.
Frequently Asked Questions
How much money do you need to buy an annuity?
Minimum purchase amounts vary by insurer and product. The more important question is how much can be committed without weakening emergency reserves, near-term spending plans, or overall diversification.
Can you cancel after purchasing an annuity?
Many states and contracts provide a free-look period during which a new owner can review and cancel the contract under specified rules. The length and refund mechanics vary, so read the contract and state-required notices immediately after delivery.
Should every retiree own an annuity?
No. An annuity is one planning tool. Suitability depends on the retiree’s income sources, liquidity, risk tolerance, tax situation, life expectancy considerations, and goals.
A Good Purchase Starts With a Good Question
Before you buy an annuity, the most useful question is not ‘Which company is best?’ It is ‘What problem must this money solve, and what am I giving up to get that benefit?’ When the answers are specific, comparing annuity pros and cons becomes much easier. The contract should fit the plan, not force the plan to fit the contract.
Educational note: This article is for general educational purposes and is not individualized financial, tax, or legal advice. Annuity features, availability, fees, surrender provisions, and guarantees vary by contract and state. Review the contract and consult appropriately licensed professionals before purchasing or replacing an annuity.