

Annuity vs CD: Same Goal, Very Different Rules for Access, Taxes, and Guarantees
A certificate of deposit and an annuity can both appeal to someone who wants more predictability than a stock portfolio provides. That surface similarity is why an annuity vs CD comparison comes up so often. Both may offer a stated rate for a period of time, but they are built under different legal structures, insured in different ways, taxed differently, and designed for different financial jobs.
A CD is a bank or credit-union deposit. An annuity is an insurance contract. That single distinction affects nearly every other part of the decision, including access to money, the meaning of a guarantee, how earnings are taxed, and whether the product can create income that lasts for life.
Start With the Provider and the Type of Guarantee
A CD issued by an FDIC-insured bank is a deposit product. The standard federal deposit insurance amount is currently $250,000 per depositor, per insured bank, for each ownership category, assuming the account meets FDIC requirements. Credit-union CDs may instead fall under NCUA insurance rules. The key point is that deposit insurance applies to the qualifying deposit relationship.
An annuity is not FDIC-insured. Its contractual guarantees depend on the claims-paying ability and financial strength of the issuing insurance company. State insurance guaranty associations may provide another layer of protection if a licensed insurer fails, but coverage rules and limits are set by state law. That protection should not be described as equivalent to federal bank-deposit insurance.
Rates Can Look Similar While the Products Work Differently
A CD rate generally applies to money deposited for a specified term. A fixed annuity can also credit a stated interest rate for a defined period, while other annuities use indexed or market-based methods. Comparing annuity rates with CD rates is therefore meaningful only when the contracts being compared are truly similar in term and risk.
A high rate can also hide a mismatch in time horizon. A five-year CD and a seven-year annuity may both display attractive rates, but the annuity could have a longer surrender schedule or different renewal provisions. The better comparison asks how long the rate is guaranteed, how long the money is restricted, and what happens when that period ends.
Access to Money Is One of the Biggest Differences
CDs commonly impose an early-withdrawal penalty if money is removed before maturity. The penalty structure is set by the bank or credit union and should be reviewed before opening the account. Once the CD matures, the owner usually receives the principal and interest or can choose another deposit term.
An annuity may have a surrender-charge period lasting several years. Many contracts allow some limited withdrawals without a surrender charge, but the amount and timing vary. Some fixed annuities can also use a market value adjustment, which may raise or lower the surrender value when money is taken out under specified conditions. This is why liquidity belongs near the top of any annuity pros and cons discussion.
Tax Timing Can Be Very Different
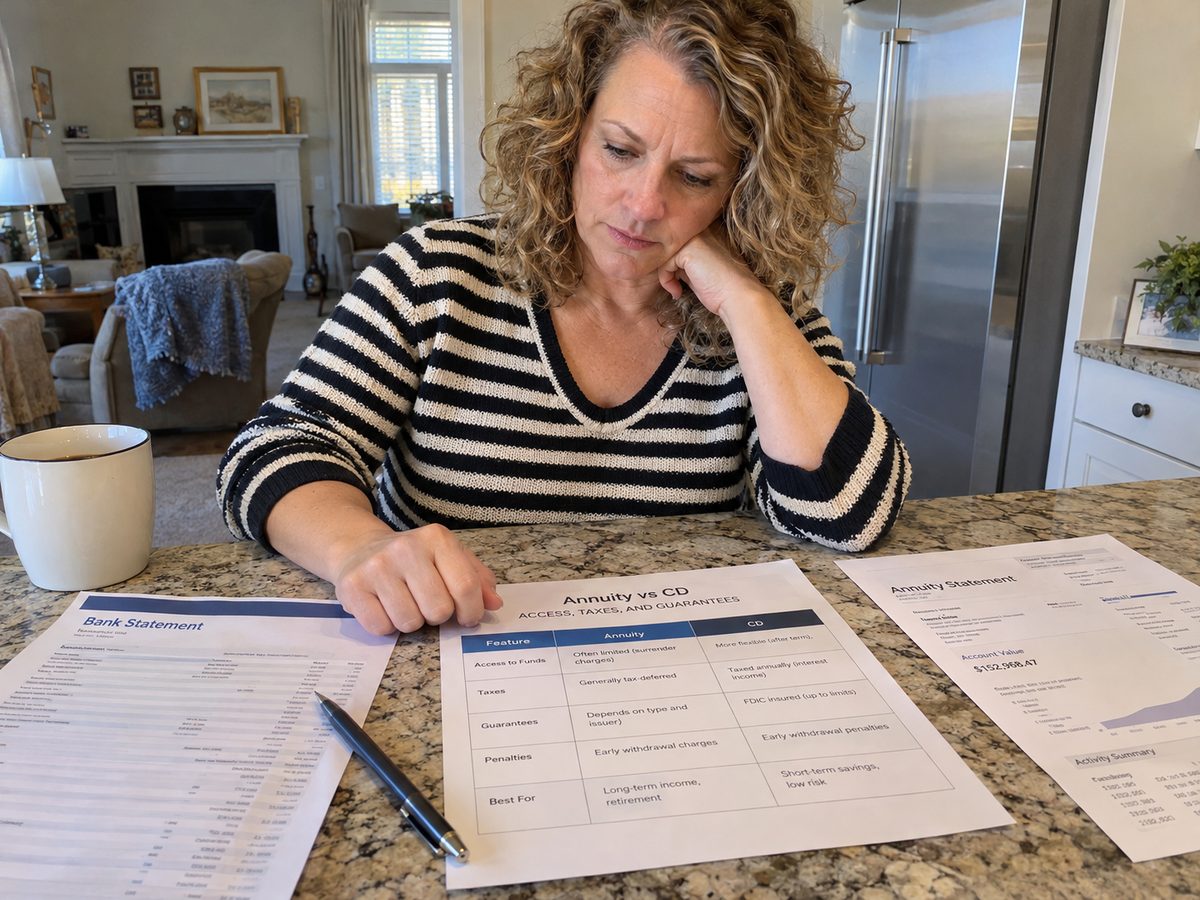
Interest earned on a CD held in a regular taxable account is generally taxable as interest income as it is credited or becomes available under federal tax rules. A nonqualified annuity funded with after-tax money generally allows earnings to grow tax-deferred until distribution. Tax deferral means tax is postponed, not eliminated.
Before the annuity starting date, withdrawals from a typical nonqualified annuity are generally treated as coming from earnings first. That taxable portion is usually taxed as ordinary income. Depending on age and circumstances, an additional federal tax can also apply to certain early annuity distributions. Tax treatment can change when the annuity is held inside an IRA or another retirement account.
A CD Is a Savings Product; an Annuity Can Also Be an Income Product
A CD reaches maturity and returns money under the deposit agreement. It is not designed to insure against the risk of living a very long time. An annuity can be structured to provide a stream of payments, including lifetime income in contracts and payout options that offer that feature.
That does not automatically make an annuity the better choice. Someone saving for a home purchase in two years may value the simpler maturity structure of a CD. Someone approaching retirement may care more about converting part of savings into predictable income. The product should be matched to the financial problem rather than selected because one category sounds safer or pays a slightly higher headline rate.
Compare the Insurance Systems Correctly
One common mistake is to say that a fixed annuity is “insured just like a CD.” It is not. Bank deposits and insurance contracts are governed by different systems. FDIC coverage is federal deposit insurance. Annuity guarantees come from the issuing insurer, with state guaranty mechanisms potentially applying if an insurer becomes insolvent and the claim is covered under state law.
For an annuity investment, insurer financial strength therefore matters. For a CD, the depositor should confirm that the institution is federally insured and understand how all deposits at that institution are grouped under the relevant ownership category. In both cases, knowing the protection system is more useful than relying on the word “guaranteed.”
Use a Side-by-Side Decision Framework
Compare provider, rate guarantee, term, early-access rules, tax timing, insurance protection, maturity or surrender process, and the need for future income. If two products are being compared on rate, make sure the term and liquidity are also similar. If retirement income is the goal, add payout options and beneficiary provisions to the comparison.
The final decision can be different for two people with the same amount of money. One may need easy access within a few years; another may be comfortable committing funds for a longer period in exchange for tax deferral and future income options. The best use of an annuity vs CD analysis is to expose those trade-offs clearly.
Frequently Asked Questions
Are annuities safer than CDs?
They are protected in different ways, so “safer” is too broad. Eligible CDs at FDIC-insured banks receive federal deposit insurance within applicable limits. Annuity guarantees rely on the issuing insurer’s claims-paying ability, with state guaranty protections subject to state rules and limits.
Which usually pays the higher rate, an annuity or a CD?
There is no permanent winner. Rates change with market conditions, term length, issuer pricing, product design, and liquidity. Compare current offers with similar terms rather than assuming one product category always pays more.
Is a CD more liquid than an annuity?
Often, but not always in every circumstance. CDs can impose early-withdrawal penalties, while annuities can impose surrender charges and other adjustments. The exact contract terms determine how costly early access would be.
Choose the Product for the Job, Not the Label
CDs and annuities can both support conservative financial planning, but they are not interchangeable. A CD is a deposit with a maturity date and federal deposit-insurance rules when eligible. An annuity is an insurance contract that can provide tax deferral, accumulation features, or retirement income. Compare the whole structure, not just the rate, before deciding where the money belongs.