

Searching for an Annuity Advisor Near You? Check Credentials Before the Sales Pitch
Typing ‘annuity advisor near me’ into a search box can produce dozens of names, advertisements, seminars, and lead-generation sites. Proximity is convenient, but it tells you almost nothing about licensing, experience, conflicts, or whether the person can explain the contract you are considering. Before discussing how to buy an annuity, verify who the professional is and what role that person is legally performing.
The word advisor is especially tricky because people who discuss annuities can operate under different licenses. A professional may be an insurance producer, a broker or registered representative, an investment adviser representative, or more than one of those at the same time. The product being recommended also matters. A fixed annuity is regulated differently from a variable annuity, which is a security as well as an insurance product.
First Identify the Professional’s Role
Insurance producers are licensed by state insurance regulators to sell, solicit, or negotiate insurance. That category includes agents and brokers under state law. If a person is discussing a fixed annuity or fixed indexed annuity, state insurance licensing is central to the transaction. Ask for the individual’s full legal name, license information, agency affiliation, and the name of the insurance company that would issue the contract.
Variable annuities and registered index-linked annuities involve securities regulation in addition to insurance regulation. Someone selling a securities product generally needs the appropriate securities registration through a broker-dealer. A financial professional who provides investment advice for compensation may also be associated with an investment adviser firm. One person can wear more than one regulatory hat, which is why the role should be clear before the recommendation is evaluated.
Verify Licensing and Background Yourself
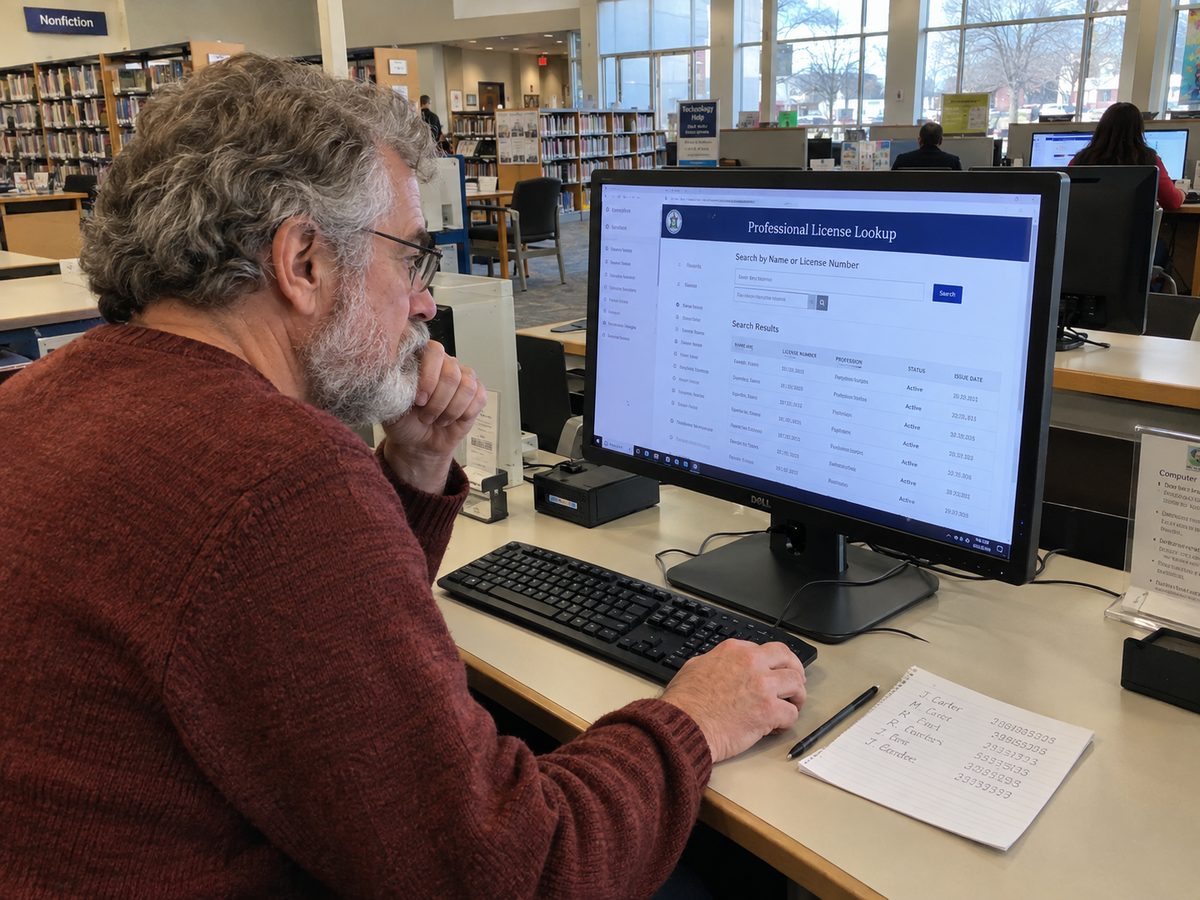
Do not rely only on a business card or website badge. State insurance departments regulate insurance-producer licenses and can help consumers verify whether a producer is properly licensed. For securities professionals, Investor.gov directs consumers to the SEC’s Investment Adviser Public Disclosure database and FINRA BrokerCheck. These tools can show registration status, employment history, and certain disciplinary disclosures.
A clean record does not guarantee good advice, and a disclosure does not automatically prove wrongdoing. The purpose of the background check is to understand who you are dealing with and to ask informed follow-up questions. If a name, employer, or license status does not match what you were told, resolve the discrepancy before transferring money or signing an application.
Ask How the Advisor Gets Paid
Compensation can shape incentives. Insurance products may pay commissions to the selling professional or agency. Some fee-based advisers may charge advisory fees and may have access to annuity designs created for advisory relationships. Variable products can include compensation through broker-dealer arrangements. The exact structure depends on the product, firm, and relationship.
Ask a simple question: ‘How are you and your firm paid if I buy this contract?’ Then ask about any ongoing fees, rider charges, trails, advisory fees, or other compensation that may apply. The goal is not to assume that a commission is improper. It is to make the economics visible so you can judge the recommendation in context.
Find Out How Broad the Product Search Really Is
An advisor may represent one insurer, a limited group of annuity companies, or a broader marketplace. That affects what can be compared. If someone claims to have found the best annuity companies for your situation, ask how many insurers and product types were actually considered and why the recommended contract was selected over the alternatives available through that professional.
Also distinguish company selection from contract selection. A financially strong insurer can issue several annuities with very different liquidity, income features, rates, surrender periods, and costs. The advisor should be able to explain the specific contract rather than relying on the reputation of the company name.
Ask the Advisor to Explain the Recommendation in Plain English
A suitable explanation should connect the contract to your stated goal. If the objective is retirement income, ask how the income is calculated, when it can start, whether it covers one or two lives, and what happens at death. If the objective is accumulation, ask how interest is credited, what can change after the first year, and how long the money is subject to surrender charges.
Then ask what could go wrong. What happens if you need $30,000 unexpectedly? What happens if interest rates rise after purchase? What happens if the index earns less than expected? What happens if the insurer’s financial condition weakens? A professional who can discuss downside scenarios is more useful than one who explains only the illustration’s attractive columns.
Pressure Tactics Are a Reason to Slow Down
Long-term financial products should withstand time for review. Be cautious if someone says a contract must be purchased immediately, describes a non-guaranteed illustration as a promise, minimizes surrender charges, or suggests moving nearly all available savings without discussing liquidity. Claims that an annuity has ‘no risk’ are also incomplete because different annuity types carry different market, insurer, inflation, and access risks.
You should also be wary if the professional refuses to provide documents before the application is signed or discourages you from getting a second opinion. A legitimate recommendation should be explainable in writing and should not become less attractive merely because you read the contract carefully.
Bring Your Own Interview Questions
Treat the first meeting like an interview rather than a sales appointment. Ask the professional to describe the annuity types they sell, which companies they can access, how they are paid, and what circumstances would make them recommend that a client not buy an annuity. A thoughtful answer to the last question can reveal whether the conversation is truly needs-based.
Ask for the recommendation in writing before moving money. The explanation should identify the objective, the reason this contract was selected, major costs and restrictions, and the alternatives considered. Written reasoning gives you something concrete to review with a spouse, accountant, attorney, or another financial professional.
If the meeting includes a replacement of an existing annuity, ask the advisor to compare the old contract and the proposed contract side by side. A new contract may offer attractive features while also restarting surrender charges or giving up older guarantees. The recommendation should explain both the benefit of changing and the cost of leaving the existing contract.
Frequently Asked Questions
Do annuity advisors need a license?
Yes, a person who sells, solicits, or negotiates insurance generally needs the appropriate state insurance-producer license. Variable and other securities-based annuities can require additional securities registrations. Specific requirements depend on the product and jurisdiction.
How do annuity agents get paid?
Compensation varies. Some insurance sales involve commissions paid through the insurer or distribution system. Advisory relationships may use fees, and some professionals have multiple compensation arrangements. Ask for the specific structure before buying.
Should I get more than one annuity quote?
Comparing more than one appropriate option can help you see differences in rates, surrender periods, income benefits, insurer strength, and costs. The comparison is most useful when the products are designed to solve the same goal.
Choose the Professional Before You Choose the Product
A local search can start the process, but it should not finish it. Verify licensing, understand compensation, check the professional’s background, ask what products can be compared, and insist on a clear explanation of the recommendation. The right annuity advisor should help you understand the contract well enough to say no as confidently as yes.
Educational note: This article provides general information and is not individualized financial, legal, or tax advice. Licensing and registration requirements vary by product and jurisdiction. Verify a professional through the appropriate state insurance regulator, securities regulator, IAPD, or BrokerCheck before acting.