

Can an Annuity Create a Paycheck for Life? How Lifetime Income Works
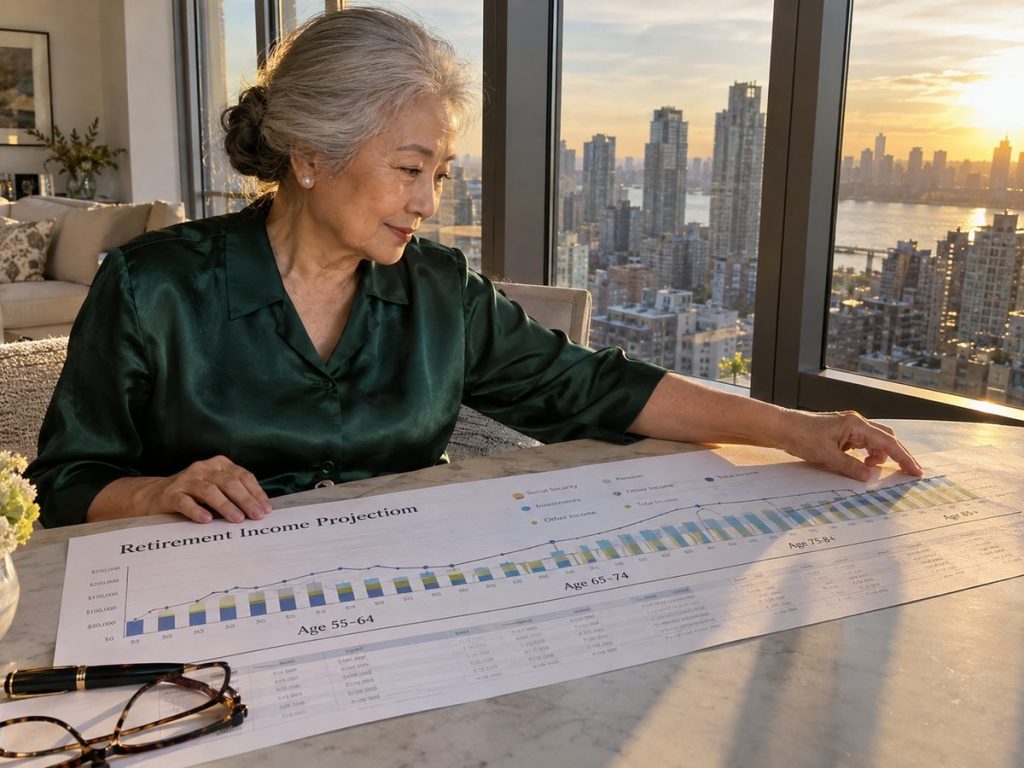
Retirement creates a problem that saving alone cannot answer: no one knows exactly how long the money must last. A person may retire at 65 and need income for ten years, thirty years, or longer. A lifetime income annuity is designed around that uncertainty by turning a premium into scheduled payments that can continue for as long as the covered person lives, subject to the contract and the issuing insurer’s claims-paying ability.
That can make an annuity feel like a personal pension, but the comparison has limits. The size of the payment depends on age, premium, payout option, interest-rate conditions, and whether the contract must continue for a spouse or provide a benefit after an early death. The promise of income for life is valuable only when the buyer understands what is guaranteed, what becomes less liquid, and what may happen to beneficiaries.
Why Lifetime Income Exists
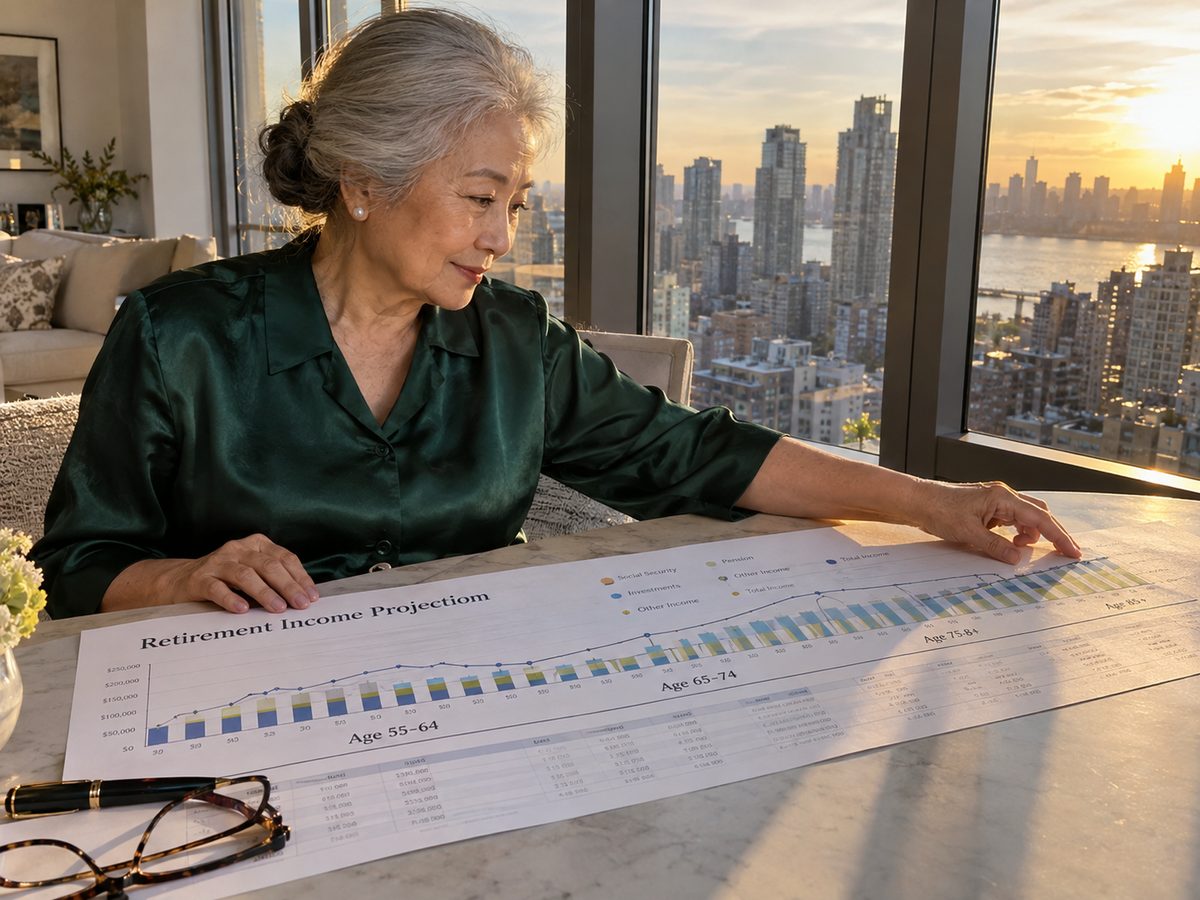
Traditional investments leave longevity risk with the retiree. If a person withdraws too quickly or lives much longer than expected, the portfolio can be depleted. A lifetime annuity shifts part of that risk to an insurance company. In exchange for a premium and the terms selected, the insurer promises scheduled payments for the covered lifetime.
Insurers can offer this structure because they price across large groups of annuitants with different lifespans. The individual does not need to predict an exact date of death. The trade-off is that the contract’s income promise may require giving up some liquidity or legacy value that would remain available in a normal investment account.
Annuitization and Lifetime Withdrawal Riders Are Not the Same
One route to guaranteed retirement income is annuitization. The owner converts contract value into a stream of payments under a selected payout option. Depending on the option, the original account value may no longer remain available as a lump sum after annuitization.
Another route, offered on some deferred annuities, is a guaranteed lifetime withdrawal benefit or similar income rider. The contract may remain in force while the owner takes withdrawals calculated under rider rules. A separate benefit base may be used to determine income and may not equal the cash value available for surrender. Because the mechanics differ, the word “lifetime” should never be enough by itself. Ask exactly how the income is produced.
Single-Life Income Versus Joint-Life Income
A single-life lifetime annuity covers one person. Payments generally continue while that person is alive under the contract terms. A joint-and-survivor option covers two lives and can continue income after the first person dies. That feature can be especially important when both spouses depend on the payment for core expenses.
Joint coverage usually changes the starting payment because the insurer may be required to pay for a longer combined period. The surviving spouse may receive 100% of the original amount or a reduced percentage, depending on the contract. A couple should compare not only the first payment but also what happens after the first death.
Beneficiary Protection Changes the Trade-Off
A life-only payout may provide a higher starting payment because it focuses on income for the covered lifetime and may stop at death. Someone who dies shortly after income begins may therefore receive fewer total dollars than someone who lives for decades. That is not a failure of the contract; it is the nature of pooling longevity risk under that payout option.
Period-certain and refund features can add protection for beneficiaries. For example, a life-with-period-certain option may continue remaining guaranteed payments if death occurs early. Refund options may return some unpaid premium under specified rules. These protections are valuable to some buyers, but they generally affect the amount of the initial income payment.
Inflation Can Reduce the Purchasing Power of a Lifetime Check
A fixed income annuity can create predictable nominal payments, but a level payment may buy less twenty years from now. That matters because retirees can face rising food, housing, and healthcare costs. Some products offer increasing payments or inflation-related features, although a higher future payment path often begins with a lower initial payment.
Another approach is to cover only part of essential spending with level guaranteed income while keeping other assets invested for growth. There is no single formula. The important point is that a lifetime guarantee protects against running out of the payment, not against every possible increase in living costs.
Inflation also changes how much of the household budget should be covered with a level payment. Expenses such as a fixed-rate mortgage may remain stable for years, while groceries, property taxes, or healthcare can rise. Matching the most predictable expenses with predictable income can be more practical than trying to guarantee the entire future budget.
What Lifetime Income Can Solve – and What It Cannot
A lifetime annuity can address longevity risk and can reduce the need to sell investments simply to fund basic monthly expenses. That may make retirement budgeting easier. It can also provide psychological value to people who prefer knowing that part of their income does not depend on daily market performance.
It does not eliminate insurer risk, inflation risk, liquidity needs, or the need for emergency savings. A guaranteed payment is backed by the claims-paying ability of the issuing insurance company. The rest of the retirement plan still needs cash for unexpected expenses, assets for long-term purchasing power, and appropriate beneficiary planning.
Questions to Answer Before Choosing Lifetime Income
Ask whether the income should cover one life or two, whether beneficiaries need a minimum payment period or refund feature, when income should start, and how much liquid money must remain outside the contract. Compare the actual lifetime annuity quote with other reliable income already available, including Social Security and pensions.
Also decide what the income is supposed to cover. Using a lifetime payment for essential expenses can be easier to evaluate than simply trying to maximize the monthly amount. If the payment has a clear job, the trade-offs between income, liquidity, and legacy become much easier to see.
Finally, review how the contract coordinates with Social Security and any pension. A lifetime annuity is often most useful when it fills a specific remaining gap rather than duplicating income that is already dependable. The amount of premium committed should leave room for cash reserves and other long-term assets.
Frequently Asked Questions
Can lifetime annuity payments stop while the annuitant is alive?
A properly structured lifetime payout is designed to continue for the covered lifetime, subject to the contract terms and the issuing insurer’s claims-paying ability. Review the exact payout option and any rider conditions.
What happens to a lifetime annuity after death?
It depends on the payout option. Life-only payments may stop at death, while joint-life, period-certain, or refund options may continue payments or provide value to a spouse or beneficiary under the contract.
Are lifetime annuity payments adjusted for inflation?
Not automatically. Many lifetime annuities pay a level amount. Some contracts offer increasing or inflation-related options, which can change the initial payment. Compare how the payment may behave over a long retirement.
A Lifetime Paycheck Is a Trade-Off, Not a Free Benefit
A lifetime income annuity can provide a powerful form of predictability because the payment does not depend on guessing how long retirement will last. In return, the buyer makes choices about liquidity, beneficiaries, inflation protection, and payout structure. The best comparison is not simply which option pays the most today. It is which promise best supports the household for as long as that promise may be needed.
Educational note: This article provides general information and is not individualized tax, legal, investment, or insurance advice. Product terms vary by insurer and contract. Guarantees depend on the claims-paying ability of the issuing insurance company.