

How Much Retirement Income Do You Actually Need From an Annuity?
A retiree with $700,000 saved can still ask the wrong first question. “How much of this should I put into an annuity?” sounds practical, but it skips the more important step: determining how much dependable income the household actually needs. A portfolio balance is not a monthly budget, and an annuity decision should begin with the income gap rather than an arbitrary percentage of savings.
Retirement income planning works better when each resource has a job. Social Security or a pension may cover part of monthly spending. Cash can handle emergencies. Investments may provide growth and flexible withdrawals. A retirement annuity may be considered for some guaranteed retirement income. The useful number is the amount of essential spending that remains uncovered after the reliable income already available is counted.
Start With Expected Retirement Spending
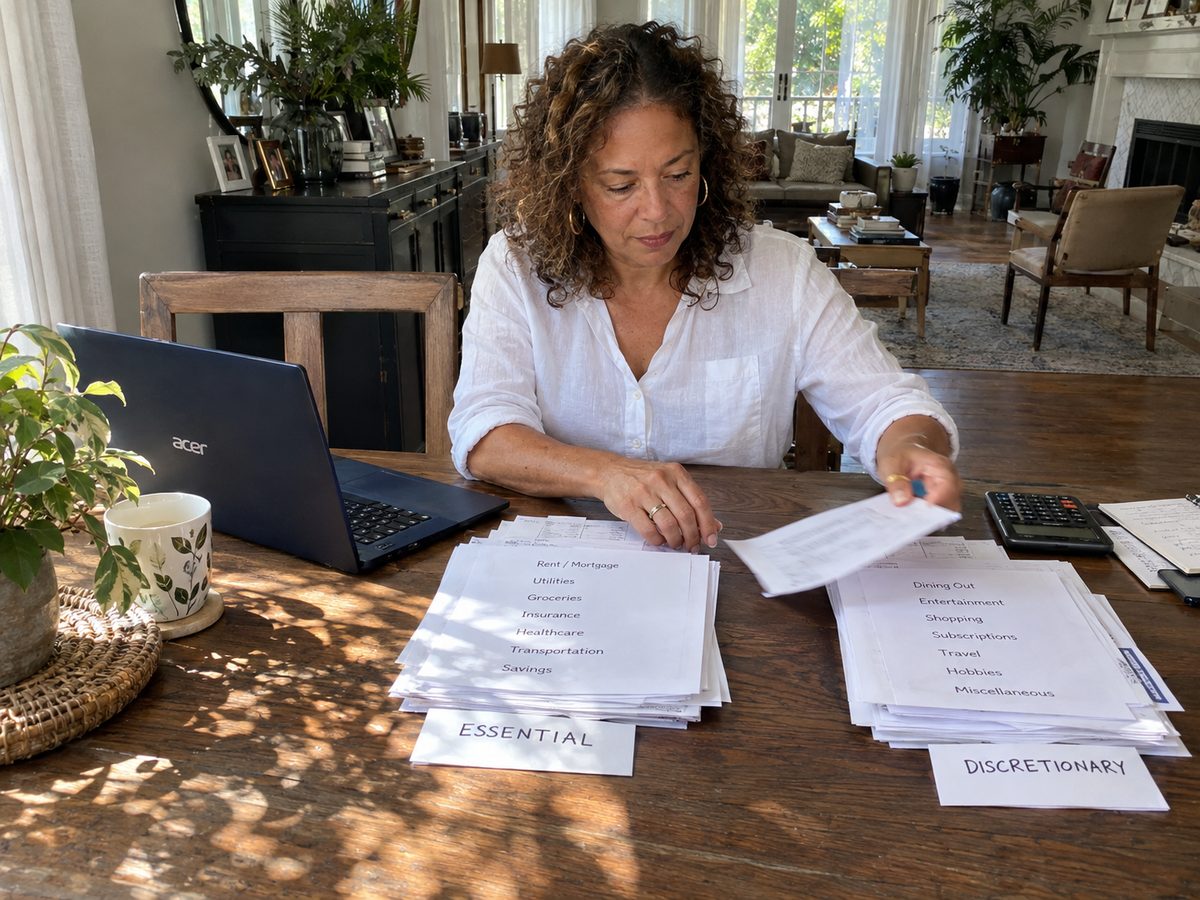
Begin with expenses, not products. Estimate housing, utilities, food, insurance, transportation, healthcare, taxes, and other recurring costs. Then separate expenses that must be paid from spending that can be reduced temporarily. Dining out, travel, gifts, hobbies, and large discretionary purchases may matter greatly to quality of life, but they are easier to adjust than a mortgage payment or medication.
A retirement income calculator can help organize these categories, but the inputs should reflect the household’s real life. Review recent bank and card statements instead of relying entirely on broad rules of thumb. Retirement can remove some costs, such as commuting, while adding others, including travel or healthcare.
Subtract Income That Is Already Predictable
Next, list income expected to arrive without selling investments. Social Security, pensions, and other contractual or government-backed income sources may already cover a meaningful share of the monthly budget. Include only amounts you reasonably expect to receive, and pay attention to whether the income is level, inflation-adjusted, temporary, or dependent on another person’s life.
Suppose a household expects $6,000 a month of essential expenses and has $4,300 from Social Security and pension income. The initial essential-income gap is $1,700 a month. That gap is more useful for planning than simply saying the household has a $900,000 portfolio.
If one spouse is expected to receive a pension or Social Security benefit that changes after the first death, model that possibility as well. Household income can look comfortable while both spouses are alive but become tighter for the survivor. Retirement income planning should test both the joint-life budget and a survivor budget.
The Gap Is a Planning Target, Not an Automatic Annuity Purchase
Once the gap is identified, decide how much of it truly needs to be covered by dependable income. Some retirees want nearly all essential expenses matched by predictable income. Others are comfortable covering part of the gap with systematic withdrawals from investments. The choice depends on risk tolerance, flexibility, other assets, and how strongly the household values payment certainty.
Annuities for retirement can be considered as one way to fill part of that gap, but they are not the only tool. A household may also use bonds, cash reserves, pension elections, or other strategies. The annuity should be evaluated for the specific job it is meant to perform.
Decide Which Expenses You Want to Protect
A useful approach is to create an “income floor” for expenses that would be difficult to cut after a market decline. Housing, basic food, utilities, insurance, and core healthcare are common examples. If reliable income already covers those categories, additional annuity income may be less urgent. If there is a meaningful shortfall, a lifetime or fixed-period income option may deserve closer review.
Do not assume every dollar of discretionary spending needs to be guaranteed. Keeping some expenses flexible can reduce the amount of capital that must be committed to an income product and leave more money available for growth, emergencies, or family goals.
Keep Liquidity in the Plan
An income plan can look secure on paper and still fail if too much money becomes difficult to access. Retirees may face home repairs, dental work, family emergencies, vehicle replacement, or other large one-time expenses. Money allocated to an annuity may be subject to surrender restrictions or, after annuitization, may no longer be available as a lump sum.
That is why retirement income planning should maintain a separate liquidity reserve. The right amount depends on the household, but the principle is straightforward: do not solve the monthly-income problem by creating an emergency-cash problem.
Liquidity is also relevant when comparing an income annuity with a deferred annuity that still has an account value. The products may solve different problems. One emphasizes a payment stream; another may preserve more access before income begins. The correct structure depends on which risk the household is trying to manage.
Inflation Changes the Gap Over Time
A $1,700 monthly shortfall at age 65 may not remain $1,700 at age 80. Prices can rise, while some sources of income remain level. Social Security benefits may receive cost-of-living adjustments, but a level annuity payment can lose purchasing power over a long retirement. Some annuity products offer increasing-payment features, but those features can change the initial payment and should be evaluated carefully.
Long-term investments may also play an important role because growth can help the household respond to inflation. The goal is balance: dependable income for core needs, enough liquid money for surprises, and enough growth potential for a retirement that may last decades.
Use the Annuity as One Component of the Plan
The answer to “How much should go into an annuity?” should come after the budget, income gap, liquidity reserve, and long-term investment needs are clear. A person with a large pension may need little additional guaranteed income. Another person with no pension and high fixed expenses may value a larger income floor.
A retirement income calculator can provide a starting framework, but actual decisions should be tested under multiple scenarios. Ask what happens if markets fall early in retirement, one spouse dies, healthcare costs rise, or inflation stays elevated. A well-sized annuity should strengthen the plan without consuming resources needed for other risks.
This process can be repeated every few years. Spending, tax rules, market values, health needs, and family circumstances can change. Retirement income planning is not a one-time calculation made on the retirement date; it is a framework that should be revisited as the household changes.
Frequently Asked Questions
What percentage of retirement savings should go into an annuity?
There is no universal percentage. The amount should depend on the household’s income gap, liquidity needs, existing pensions or Social Security, risk tolerance, and other assets. Start with the expenses that need dependable funding rather than a preset allocation.
Should Social Security be counted as guaranteed income?
For retirement planning, Social Security is commonly treated as a predictable income source under current law, although future policy can change. Use the benefit estimate you reasonably expect and consider the timing of when benefits will begin.
How do I account for inflation when planning annuity income?
Project expenses over time instead of assuming today’s budget stays unchanged. Compare level payments with any increasing-payment options and retain other assets that may provide growth or flexible withdrawals.
Size the Income Solution Around the Household
The purpose of guaranteed retirement income is not to make the largest possible annuity purchase. It is to cover the part of the household budget that benefits most from predictability. Calculate essential spending, subtract dependable income, protect liquidity, and allow for inflation. Once the gap is clear, the amount of annuity income to consider becomes a much more practical question.
Educational note: This article provides general information and is not individualized tax, legal, investment, or insurance advice. Product terms vary by insurer and contract. Guarantees depend on the claims-paying ability of the issuing insurance company.