

Retiring Soon? How an Immediate Annuity Turns Savings Into Income
A retirement account balance can look reassuring on paper, but retirement expenses arrive as monthly bills. Housing, utilities, groceries, insurance premiums, and healthcare do not wait for a good market year. That mismatch is why some retirees consider an immediate annuity. Instead of leaving the entire amount as a lump sum to be managed and withdrawn over time, part of the savings can be exchanged for scheduled income from an insurance company.
A single premium immediate annuity, often shortened to SPIA, is one of the simplest versions of an income annuity. The buyer pays one lump sum and selects a payout option. Payments generally begin soon after purchase, commonly within one year. The amount received depends on several factors, including age, premium, payout structure, prevailing pricing conditions, and whether the income covers one life or two.
What Happens When You Purchase an Immediate Annuity
The process starts with a lump-sum premium. The insurer uses the premium and the selected payout terms to calculate a periodic payment. The owner then chooses how often payments will arrive, usually monthly, quarterly, semiannually, or annually, depending on the product. Once the contract is issued and the income start date arrives, the payments begin according to the selected option.
An immediate annuity has little or no accumulation phase. That is what separates it from a deferred retirement annuity, which may grow for years before income begins. The immediate contract is mainly about converting capital into cash flow now rather than maximizing future account value.
What Determines the Income Amount
The premium matters first. All else equal, a larger premium generally supports a larger payment. Age also matters because lifetime-income pricing reflects how long the insurer expects payments may continue. A person who starts income later will often receive a different payout than someone starting at a younger age with the same premium.
The payout option can have an equally important effect. A life-only payment generally provides income for one person’s lifetime and stops at death. A joint-and-survivor option continues while either covered person is alive, so the initial payment is usually lower than a comparable single-life payment. Adding a period-certain or refund feature can also reduce the starting payment because the insurer is taking on an additional obligation to beneficiaries.
Interest-rate and insurer pricing conditions at the time of purchase also affect quotes. That is why immediate annuity quotes should be compared using the same premium, ages, start date, and payout option.
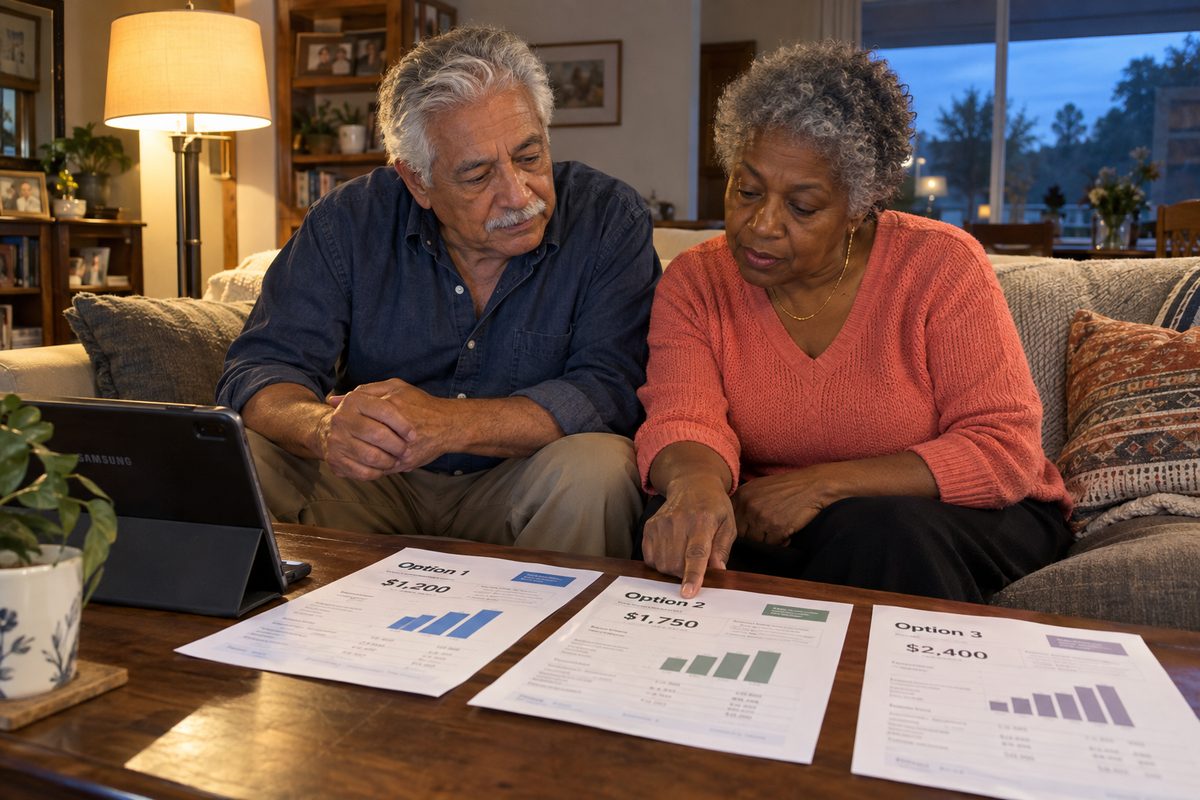
Quote comparisons work best when every variable is held constant. If one insurer is asked to quote a single-life payment starting next month while another is asked for joint-life income with a 10-year certain period, the numbers are not comparable. Consumers should use the same premium, ages, start date, payment frequency, and survivor or refund option when collecting quotes, then compare insurer strength and contract terms alongside the monthly amount.
Choosing the Payout Structure
The highest initial payment is not always the most appropriate choice. Life-only income can maximize the monthly amount, but there may be little or no value remaining for heirs after the annuitant dies. Someone who wants survivor protection can choose a joint-life option. Someone who wants payments to continue for at least a minimum number of years may select a life-with-period-certain option, if offered.
Refund features can provide another form of beneficiary protection. Depending on the contract, the insurer may return remaining premium in a lump sum or continue installments if the annuitant dies before receiving payments equal to the amount specified by the contract. Each additional protection changes the economics of the payout.
This is a central decision with a single premium immediate annuity: more protection for beneficiaries usually means less monthly income while the annuitant is alive.
The Biggest Trade-Off: Liquidity
When an immediate annuity is annuitized for lifetime income, the original premium generally stops functioning like a normal savings account. The buyer has exchanged access to that lump sum for a contractual stream of payments. That can be useful for someone who wants predictable cash flow, but it can become a problem if too much of the household’s liquid savings is committed.
For this reason, an immediate annuity is often considered for only part of retirement assets. A retiree may keep emergency savings, short-term spending money, and growth investments outside the contract while using an annuity to cover a portion of essential expenses. The exact balance depends on personal needs and risk tolerance.
Before purchasing, ask whether the contract offers any commutation, cash-refund, or liquidity feature, and understand how choosing it affects the payment amount. Do not assume money can be withdrawn later simply because other types of annuities allow withdrawals.
This trade-off is easiest to see by separating retirement money into categories. Funds for next year’s property taxes, a replacement vehicle, or emergency medical costs need ready access. Money dedicated to covering groceries and utilities for the rest of life has a different job. An immediate annuity may make sense for the second category while being a poor place for the first.
What About Inflation?
A fixed monthly payment may feel secure at retirement, but purchasing power can erode over time. A payment of $2,000 today will not buy the same amount of goods and services decades later if prices continue rising. That creates inflation risk even when the income itself is guaranteed.
Some immediate annuities may offer increasing payment options or inflation-related adjustments, but the starting payment is usually lower when future increases are built in. Another approach is to use the annuity only for part of essential expenses while keeping other assets invested for long-term growth. The objective is not to eliminate every risk with one product, but to assign different assets to different jobs.
Retirement length makes this especially important. Someone retiring at 65 may need income for 25 or 30 years, and even moderate inflation can materially change living costs over that period. A level-payment annuity can still be useful, but the household should understand which expenses will be covered by fixed income and which assets remain available to grow or adjust with rising prices.
Where an Immediate Annuity May Fit in Retirement
An immediate annuity can be useful for a retiree who has a clear gap between reliable income and essential monthly expenses. Suppose Social Security and a pension cover most expenses but leave a recurring shortfall. A portion of savings could be used to create guaranteed retirement income that helps cover that gap, while the rest remains available for liquidity, inflation protection, and discretionary spending.
It may be less suitable for someone who needs flexible access to most of their savings, wants to leave the maximum possible liquid estate, or is uncomfortable exchanging a lump sum for income. Health, family longevity, other guaranteed income sources, and the need for survivor protection also affect the decision.
The best use of an immediate annuity is usually not “put everything in it.” It is to decide whether converting a specific portion of savings into dependable income makes the overall retirement plan easier to manage.
Frequently Asked Questions
How soon can an immediate annuity begin payments?
Immediate annuity payments generally begin soon after purchase, often within one year. The exact first payment date depends on the contract and the payment frequency selected.
What happens to the money when the annuitant dies?
It depends on the payout option. Life-only income may stop at death, while joint-life, period-certain, or refund options can continue payments or provide value to a surviving spouse or beneficiary.
Can immediate annuity payments increase over time?
Some contracts offer increasing or inflation-adjusted payout options. These typically begin with a lower initial payment than a level-payment option, so the trade-off should be compared carefully.
Use Income to Solve a Specific Gap
An immediate annuity is most useful when it solves a clearly defined retirement-income need. Estimate essential monthly expenses, subtract Social Security, pension, and other reliable income, then determine whether a remaining gap needs to be covered with guaranteed income. Compare several payout structures and insurers before converting any portion of retirement savings into an irreversible or less-liquid income stream.
Educational note: This article provides general information and is not individualized tax, legal, investment, or insurance advice. Product terms vary by insurer and contract. Guarantees are subject to the claims-paying ability of the issuing insurance company.