

Rolling a 401(k) Into an Annuity? Avoid These Transfer and Liquidity Mistakes
Leaving a job can turn a familiar 401(k) balance into a new decision. The money might stay in the former employer’s plan, move to a new employer plan if allowed, roll to an IRA, or be used to purchase an annuity inside a retirement account. A 401k rollover to annuity can preserve tax-deferred retirement status when handled correctly, but the transfer method and the new contract both deserve close attention.
The biggest mistake is treating the rollover as a simple product purchase. It is actually two decisions: where the retirement money should be held and whether an insurance contract improves the retirement plan. The tax rules for the transfer should be handled first; then the annuity’s guarantees, costs, and liquidity should be evaluated separately.
Understand Why You Are Considering the Rollover
Common reasons include retiring, changing employers, wanting a predictable future income stream, or seeking a different risk profile. A retirement annuity can potentially provide fixed accumulation, index-linked crediting, market-based investment choices, or guaranteed lifetime income, depending on the contract.
Those benefits should solve a real problem. If the current 401(k) already offers low-cost investments, convenient withdrawals, and features the participant values, moving it solely because an annuity salesperson highlights tax deferral is not a complete reason. Qualified retirement money is already tax-deferred.
A Direct Rollover Usually Avoids Mandatory Withholding
Current IRS guidance allows an eligible retirement-plan distribution to be sent directly to another eligible retirement plan or IRA. In a direct rollover, mandatory federal withholding generally does not apply to the transferred amount. This is usually cleaner than receiving the distribution personally and trying to move it afterward.
If an eligible rollover distribution from an employer plan is paid directly to the participant, federal rules generally require 20% withholding on the taxable amount. The participant normally has 60 days to complete a rollover, and rolling over the full taxable amount can require replacing the withheld money from another source. That is why the payment instructions matter.
Not Every 401(k) Distribution Can Be Rolled Over
Some distributions are not eligible for rollover. IRS rules exclude items such as required minimum distributions, hardship distributions, and certain periodic payments, among others. Before initiating any transfer, confirm that the specific amount is rollover-eligible and that the receiving account can accept it.
This is also where timing matters. Someone already subject to required minimum distributions generally cannot roll that year’s required distribution into an annuity as part of the rollover. Administrative errors can create unwanted taxes even when the larger retirement strategy makes sense.
Tax Deferral Is Not an Extra Benefit Inside an IRA
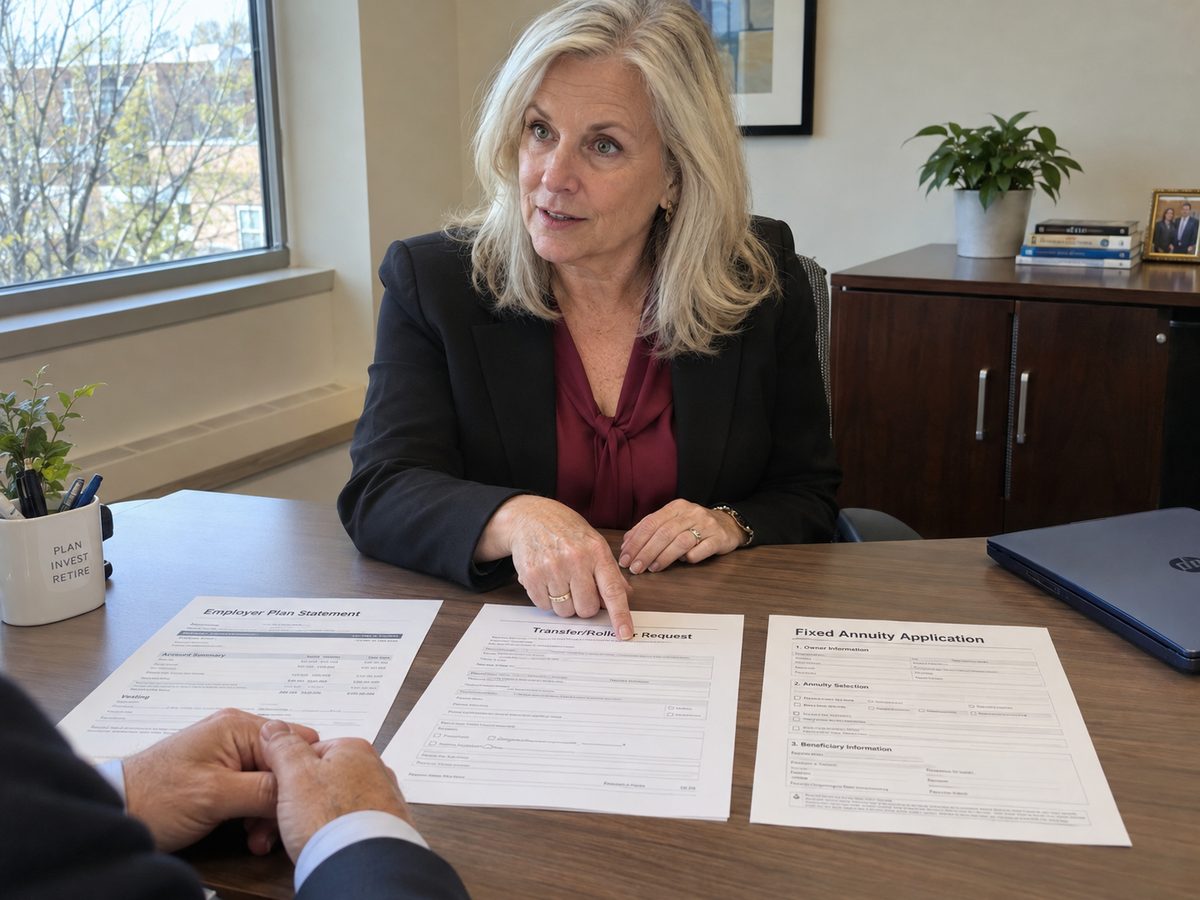
When pre-tax 401(k) money is rolled into a traditional IRA and then used to buy an annuity, the retirement account already provides tax deferral. The annuity needs to justify itself through its insurance features, such as a guaranteed rate, lifetime-income option, or a particular form of downside protection.
People asking how are annuities taxed should separate qualified and nonqualified contracts. A qualified annuity held with pre-tax retirement money generally follows the tax rules of the retirement account. Distributions are not transformed into tax-free income simply because the money is paid from an annuity.
Compare What You May Lose by Leaving the 401(k)
A rollover can provide more product choices, but the old plan may have advantages. These can include institutional investment pricing, plan-specific withdrawal features, creditor protections under federal law, access to plan loans before separation where applicable, or age-based distribution exceptions that do not work exactly the same way in an IRA.
The details vary by plan and personal situation, so make a written list before moving the money. Ask what the 401(k) currently costs, which funds are available, what withdrawal options exist, and whether any protections or tax exceptions would be lost after the rollover.
Do Not Let Long Surrender Terms Trap Money Needed Soon
Annuities for retirement are often designed as long-term contracts. A surrender schedule can create a problem if too much of the retirement balance is moved into one annuity and the retiree later needs cash for healthcare, housing, family support, or another major expense.
Before deciding to buy an annuity, identify how much liquid money will remain outside the contract. Then ask how much can be withdrawn annually without a surrender charge, whether a market value adjustment applies, and how excess withdrawals affect any guaranteed-income rider.
Evaluate the Income Promise Separately From the Account Value
If the reason for the rollover is lifetime income, ask how the payment is calculated. Find out whether the contract is annuitized or uses a guaranteed withdrawal rider, whether the benefit covers one life or two, what age income can begin, and how withdrawals affect the benefit.
An income base shown on an illustration may not be the same as the cash surrender value. The advisor should be able to identify which number determines income, which number can actually be withdrawn, and what happens if the investment account is depleted while the rider rules are followed.
Required Minimum Distribution Rules Still Matter
Moving qualified retirement money into an annuity generally does not erase required minimum distribution obligations. Current RMD rules depend on factors such as the owner’s birth year and account type. The annuity should be able to support required distributions without unexpectedly damaging guarantees or triggering avoidable surrender costs.
Ask the insurer how required distributions are handled and whether the contract has provisions designed to accommodate them. This is especially important when a large percentage of an IRA balance is placed into a deferred annuity.
Be Careful With Bonuses and Replacement Incentives
Some annuity proposals use premium bonuses, enhanced benefit bases, or other incentives to make a rollover look immediately attractive. Those features can have separate vesting rules, longer surrender periods, rider charges, or limits on the amount that is actually available as cash. A bonus shown on an illustration should not be assumed to be freely withdrawable money.
Ask the advisor to explain what portion of any bonus becomes part of the cash surrender value, what happens if the contract is surrendered early, and whether accepting the feature changes other terms. The decision should still be based on the retirement plan, not on an upfront number that may be conditional.
Frequently Asked Questions
Is a direct 401(k) rollover to an annuity taxable?
A properly completed direct rollover of an eligible distribution to an eligible retirement arrangement generally preserves tax deferral. The annuity is usually held inside the receiving IRA or other eligible retirement structure. Specific tax treatment depends on the accounts involved.
Can I roll my entire 401(k) into an annuity?
It may be possible for eligible amounts, but that does not mean it is automatically appropriate. Consider liquidity, plan benefits, diversification, required distributions, and the annuity’s surrender rules before moving the entire balance.
Does an annuity eliminate required minimum distributions?
No. Qualified retirement money generally remains subject to applicable RMD rules. The exact rules depend on account type and current federal law.
Treat the Rollover and the Annuity as Two Separate Decisions
A 401(k) rollover can be handled efficiently, but the new destination must still earn its place in the retirement plan. Use a direct transfer where appropriate, verify rollover eligibility, compare what the old plan provides, and preserve enough liquidity. Only then evaluate whether the annuity’s guarantees or income features solve a problem worth the contract’s restrictions and costs.