

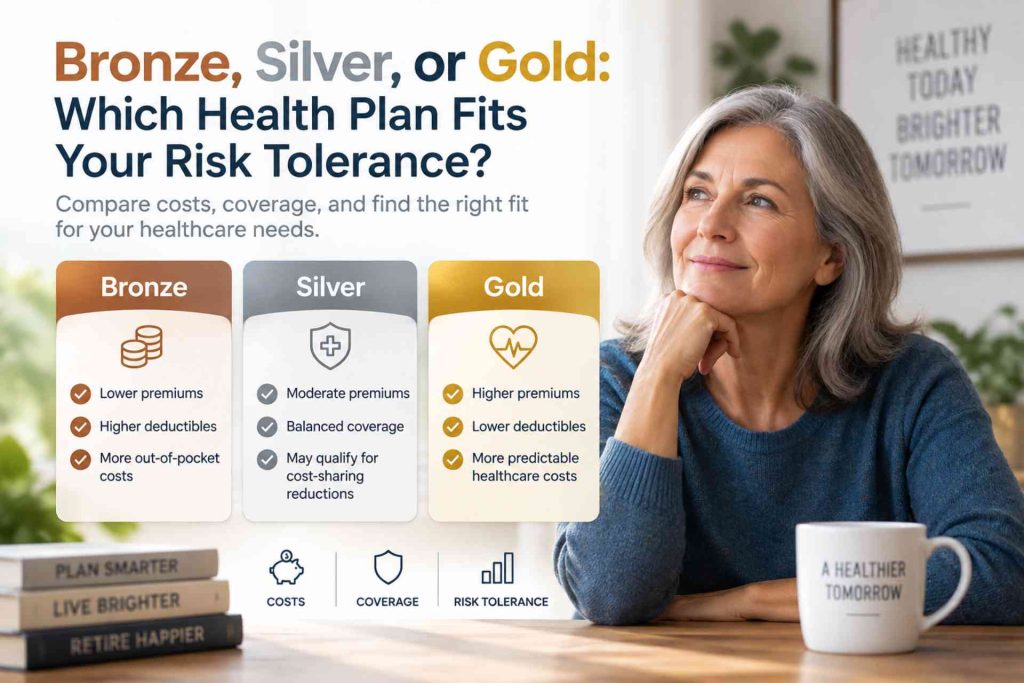
Bronze Silver Gold Health Plans: Which Fits Your Risk?
Choosing a Marketplace health plan is not really a contest between Bronze, Silver, and Gold. The metal levels describe how healthcare costs are generally divided between you and the insurer, not the quality of doctors, hospitals, or medical care.
For a professional approaching retirement, the more useful question is different: How much financial risk are you comfortable retaining when healthcare is actually needed?
That question brings premiums, deductibles, copayments, coinsurance, provider networks, expected healthcare use, and available cash reserves into the same decision.
The cheapest monthly premium may not produce the lowest annual cost. A more expensive plan may also provide greater predictability when medical expenses rise.
What Do Bronze, Silver, and Gold Actually Mean?
Marketplace plans use metal categories to indicate the approximate share of covered healthcare costs paid by the plan versus the enrollee.
HealthCare.gov currently describes the categories this way:
| Plan level | Approximate plan share | Approximate enrollee share | Typical cost structure |
| Bronze health insurance | 60% | 40% | Lower premiums, higher cost-sharing |
| Silver health insurance | 70% | 30% | Moderate premiums and cost-sharing |
| Gold health insurance | 80% | 20% | Higher premiums, lower cost-sharing |
These percentages are actuarial estimates across a standard population, not promises about what one individual will pay.
The metal level therefore should not be interpreted as a quality ranking.
Bronze is not inferior coverage.
It generally shifts more financial responsibility toward you when covered healthcare is used. Gold generally shifts more of that responsibility toward the insurer.
Why Does Risk Tolerance Matter?
Suppose you are financially comfortable and have substantial liquid assets.
You might reasonably tolerate a higher deductible because you can absorb a large unexpected medical bill without disrupting your retirement plan.
Another person with similar income might prefer predictable healthcare expenses and willingly pay higher premiums to reduce potential out-of-pocket exposure. Neither choice is automatically better.
The difference is health insurance risk tolerance.
Your decision should reflect how much uncertainty you want your household budget to absorb.
Is Bronze Health Insurance Actually Cheaper?
Usually, Bronze plans have lower premiums than their Silver or Gold counterparts, but it does not necessarily mean lower total healthcare costs.
HealthCare.gov describes Bronze plans as generally having lower premiums and higher deductibles, while the Gold ones have generally had higher premiums and lower deductibles.
This, in effect, creates a straightforward trade-off. You save money while healthy, but potentially assume more expense when healthcare is required.
For someone who rarely uses medical services and has substantial emergency reserves, that structure may be reasonable.
However, for someone expecting frequent care, the calculation can change considerably.
What Does Silver Health Insurance Offer?
Silver health insurance occupies the middle of the standard metal-tier structure.
It generally involves higher premiums than Bronze and lower cost-sharing than Bronze. For many consumers, that creates a middle-ground approach between monthly affordability and protection against healthcare expenses.
But Silver has another important feature.
If you qualify for cost-sharing reductions, you generally must select a Silver plan to receive those additional savings. These reductions can lower deductibles, copayments, and coinsurance for eligible lower-income Marketplace enrollees.
That makes Silver particularly important to evaluate based on household income.
Why Has Bronze Become More Popular?
Current Marketplace data provide an interesting lesson about consumer risk decisions.
KFF reports that Bronze selections increased from 30% of Marketplace plan selections in 2025 to 40% in 2026. Silver selections fell from 57% to 43%, while their Gold counterparts increased from 13% to 17%.
KFF attributes much of the shift toward Bronze to consumers seeking lower premiums after enhanced premium tax credits expired. The trade-off was significant.
Average Marketplace deductibles increased from $2,759 in 2025 to $3,786 in 2026, a 37% increase. This illustrates the central issue perfectly.
Lower premiums can transfer risk elsewhere.
Could Gold Health Insurance Make Sense?
Gold health insurance generally costs more each month but requires less cost-sharing when covered healthcare is used.
For someone expecting substantial healthcare utilization, the higher premium may be worth considering.
Imagine someone expecting regular specialist visits, expensive prescriptions, or planned medical procedures. Paying more for coverage could reduce financial exposure during the year.
The relevant comparison is, therefore, not simply: “Which plan has the lowest premium?”
Instead, it is: “Which combination of premium and expected out-of-pocket spending best fits the household?” This leads to a much more useful calculation.
What Does Current Pricing Tell You?
KFF’s 2026 data show national average monthly premiums of approximately $456 for the lowest-cost Bronze plan, $611 for the lowest-cost Silver, and $615 for the lowest-cost Gold for a 40-year-old. The figures are averages and vary substantially by geography and plan availability.
Health insurance costs differ, and making location and plan availability are crucial. The result is particularly interesting. Gold does not necessarily cost dramatically more than Silver in every market.
Consequently, consumers should not assume that the traditional progression always produces proportionately higher premiums.
The actual marketplace should be compared.
Why Should You Calculate Total Annual Cost?
A meaningful health insurance comparison needs more than monthly premiums.
Consider this simplified framework:
| Cost component | Bronze | Silver | Gold |
| Monthly premium | Lower | Moderate | Higher |
| Deductible | Usually higher | Moderate | Usually lower |
| Copayments | Generally higher | Moderate | Generally lower |
| Coinsurance | Generally higher | Moderate | Generally lower |
| Financial exposure | Higher | Moderate | Lower |
| Best fit | Lower utilization, higher risk tolerance | Balanced approach | Higher utilization, greater predictability |
Actual plan designs vary, so the table should be treated as a framework rather than a prediction. HealthCare.gov specifically recommends considering total healthcare spending rather than premiums alone.
What About Your Emergency Reserves?
This is where your financial position becomes relevant. A professional with significant liquid savings may be able to withstand a high deductible without selling investments at an inconvenient time.
But this does not automatically make Bronze appropriate.
The question is whether the household can absorb the potential expense without compromising other financial objectives.
Consider:
- Emergency savings.
- Retirement assets.
- Expected healthcare utilization.
- Prescription expenses.
- Upcoming procedures.
- Monthly cash flow.
- Other insurance coverage.
- Debt obligations.
Your financial capacity changes the meaning of healthcare risk.
Does Your Health Change the Decision?
Expected healthcare utilization should be one of the strongest variables in your comparison.
If healthcare use is consistently low, a lower-premium plan may deserve closer examination.
If healthcare use is high, paying more for reduced cost-sharing may become economically attractive.
The calculation becomes particularly important when regular prescriptions, specialist care, or planned procedures are involved.
Do not choose based solely on today’s health. Insurance exists partly because tomorrow’s healthcare needs are uncertain.
What About Provider Networks?
Metal level does not tell you whether your preferred physician or hospital participates in the plan.
HealthCare.gov notes that Marketplace plans can have different provider networks, including arrangements involving HMOs and PPOs.
Therefore, health insurance plan comparison should examine network structure separately from metal level.
A Gold plan with an unsuitable network may be less useful than a Bronze plan that provides access to the providers you actually need.
First, check the network, then the cost.
What Is the Best Choice for Someone Approaching Retirement?
There is no universal winner.
A financially strong professional with substantial reserves and low expected utilization may consider Bronze because lower premiums preserve cash flow.
Someone expecting greater healthcare use may prefer Gold because greater premium expense can provide more predictable cost-sharing.
Silver can occupy a useful middle position, particularly when cost-sharing reductions are available.
The decision should therefore begin with three questions:
How much healthcare will you likely use?
How much financial risk can you comfortably absorb?
How much predictability do you value?
Those answers provide a stronger foundation than the metal label itself.
The Better Way to Choose
Bronze, Silver, and Gold are not three grades of healthcare quality.
They are different ways of distributing healthcare costs between you and the insurer.
For professionals and pre-retirees, the strongest health insurance strategy is therefore the one that aligns premiums, healthcare utilization, liquidity, risk tolerance, and expected financial obligations.
A lower premium can preserve cash today.
A higher premium can purchase greater predictability tomorrow.
The right choice depends on which form of uncertainty you are better positioned to carry.
Educational Disclaimer
This article provides general educational information about Marketplace health-plan metal tiers. It is not individualized financial, tax, legal, or insurance advice. Premiums, deductibles, networks, subsidies, eligibility, and plan designs vary by person, location, income, and insurer. Verify current plan details before enrolling.