
Can You Have Multiple Life Insurance Policies? How Layered Coverage Works
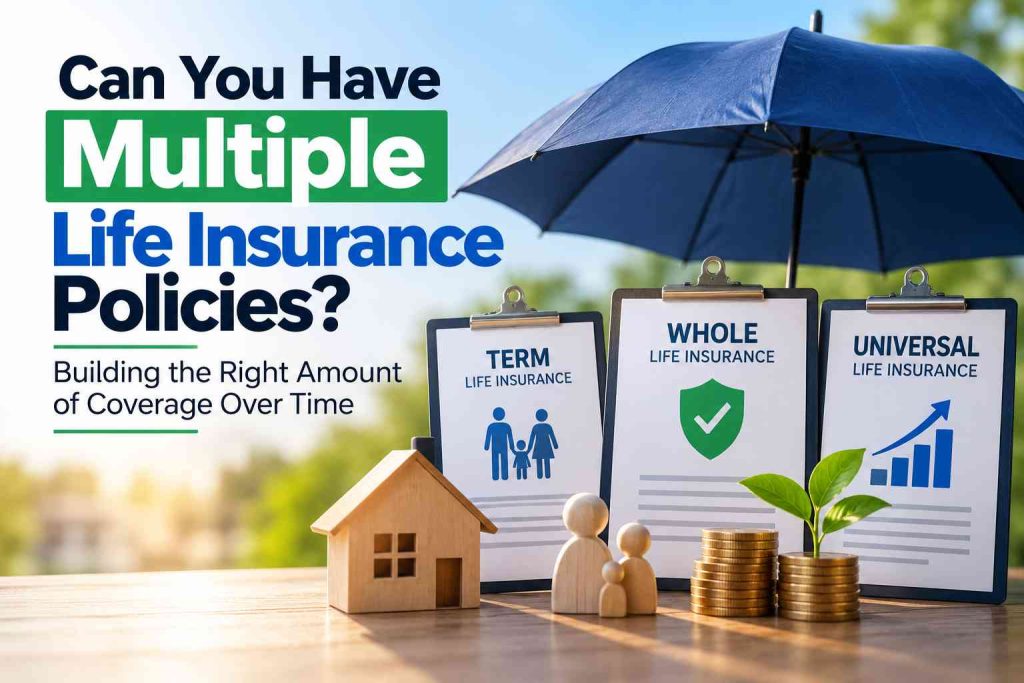
Life insurance does not have to be one policy purchased once and never revisited. Can you have multiple life insurance policies? Yes, people can own more than one policy, subject to underwriting, insurable-interest rules, and the insurer’s evaluation of total coverage. Layering can make sense when different financial needs have different timelines.
A new parent might already have a small permanent policy and then add a large term policy for income replacement. A business owner may have personal coverage plus coverage connected to a business agreement. Someone nearing retirement may let temporary coverage decline while keeping a permanent policy for a lifelong goal.
The key question is not the number of policies. It is how much life insurance do I need in total, what does life insurance cover in each layer, and whether the combined premium still fits the budget.
Yes, People Can Own More Than One Policy
There is no general rule limiting a person to one life insurance policy. Insurers can issue additional coverage when there is a legitimate financial need and the total amount is supported by underwriting. The applicant must disclose existing coverage and pending applications accurately.
Insurable interest also matters at policy issue. The policy owner must have a valid reason recognized by applicable law for insuring the person’s life. Personal, family, and business relationships can create different situations.
The practical point is that multiple policies are allowed, but every new application is still underwritten. A second policy is not automatically approved just because the first one exists.
Why People Layer Coverage
People layer coverage because needs change. A term policy can protect income during child-raising years. A permanent policy can address final expenses or a legacy goal. A business policy can address key-person or ownership obligations. Different term lengths can also be stacked to match debts that decline over time.
Layering can make the premium more efficient because the entire death benefit does not have to be permanent. The household can reserve permanent coverage for permanent needs and use term where the need is temporary.
That strategy still requires organization. Beneficiaries should know policies exist, and the owner should keep insurer information and policy numbers in a secure place.
Recalculate the Amount When Life Changes
Recalculate coverage when life changes. Marriage, divorce, a new child, a mortgage, income growth, business ownership, retirement, or caring for a dependent can all alter the need. An annual or periodic review is easier than waiting for a crisis.
Who needs life insurance can also change within a household. A non-working spouse may still create a substantial financial need because replacing childcare or household work costs money. A business partner may create a separate need from family protection.
The review should ask whether each existing policy still has a job. If a policy no longer fits, evaluate the consequences before changing it.
An annual coverage review can be completed in less than an hour if the information is organized. List every policy, owner, insured, beneficiary, death benefit, premium, term end date, and cash value where applicable. Then write the purpose beside each policy. If two policies serve the same purpose, check whether the overlap is still intentional. If a new need has appeared, price the gap rather than replacing everything. This approach makes adding coverage deliberate and reduces the chance of surrendering a useful older policy simply because a new illustration looks more attractive.
Review Existing Policies Before Replacing or Adding
Replacing a policy is different from simply adding coverage. A new policy can involve new underwriting, new contestability and suicide periods under applicable law and contract terms, new acquisition costs, and a new surrender schedule. The existing policy may also have valuable guarantees or cash value that would be lost.
Do not cancel old coverage until the new policy is fully approved, delivered, accepted, and in force according to its terms. State replacement rules and disclosure requirements can apply. The NAIC replacement framework is designed to protect consumers when an old contract is being discontinued in connection with a new sale.
MM4I can help review existing policies before adding or replacing coverage. The final article in this batch returns to the same principle as the first: coverage should follow the need. Multiple policies are useful when each layer has a clear purpose.
Replacement deserves a separate checklist from new coverage. Ask whether the old policy has surrender value, guaranteed benefits, conversion rights, favorable underwriting, or riders that would be lost. Compare the new premium and guarantees using the same time horizon. Confirm whether replacement forms are required in the state. Then wait until new coverage is fully in force before changing the old policy. The NAIC replacement model warns consumers that replacing coverage can involve acquisition costs and surrender costs and encourages careful comparison. The safest process treats replacement as a major contract decision, not as routine housekeeping.
Keeping a simple policy inventory also helps beneficiaries. Include insurer contact information, policy numbers, ownership, and where documents are stored. Do not store sensitive information in an unsecured public file, but make sure a trusted person knows how to locate the records. Multiple policies only help if the family knows they exist.
Before adding another policy, request an updated summary of every policy already in force. Compare the current death benefit, premium, cash value where applicable, term expiration date, riders, beneficiaries, and the original purpose of the coverage. Then identify the exact gap the new policy is meant to fill. This prevents a new application from becoming an unnecessary replacement. It also helps the adviser explain total coverage to the insurer during underwriting. MM4I can make the review simple by organizing existing and proposed policies on one page, so the client can see which needs are temporary, which are permanent, and which are already fully covered.
Finally, multiple policies create a beneficiary-management responsibility. A marriage, divorce, birth, death, or business change can make an old designation inappropriate. Review beneficiaries on every policy, not just the newest one. The insurer’s beneficiary form controls the contract, so changes should be completed through the proper process and confirmed in writing.
Frequently Asked Questions
Can you have multiple life insurance policies at once?
Yes. People can own multiple policies, subject to underwriting, insurable-interest requirements, and financial justification for the total amount of coverage.
How much life insurance do I need?
Estimate income replacement, debts, dependents, final expenses, business obligations, and legacy goals, then subtract assets already available for those needs. The result is a starting point, not a universal formula.
Should I replace an old policy when buying a new one?
Not automatically. Replacing coverage can create new underwriting, surrender costs, and new policy periods. Review the existing contract and keep it in force until any replacement is fully approved and active.
Review Coverage as Life Changes
Multiple policies can be a practical way to match temporary and permanent needs without forcing one contract to do everything. The important number is not how many policies exist. It is whether the total coverage is appropriate and affordable.
MM4I can help organize existing and proposed coverage into one annual review. That makes it easier to see gaps, overlaps, and policies that no longer serve the reason they were purchased.