

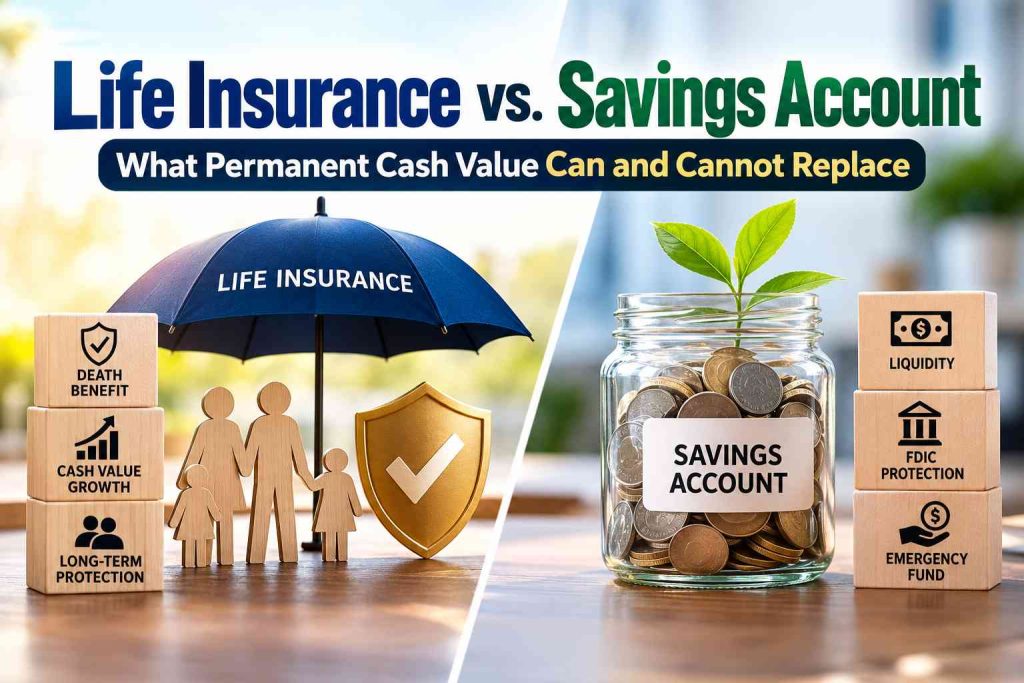
Life Insurance vs Savings Account | What Cash Value Can and Cannot Replace
Cash value can be accessible, but that does not make a permanent policy the same thing as a savings account. Life insurance vs savings account is really a comparison of two tools built for different jobs. A savings account is designed for liquidity. A whole life insurance policy is designed first to provide life insurance protection, with cash value as a long-term policy feature.
That difference matters when someone is building an emergency fund. Money for a broken furnace, car repair, or sudden job loss should be easy to reach. Permanent life insurance cash value may be available through loans, withdrawals, or surrender, but those actions can affect the policy and may create costs or tax consequences.
The better question is not whether one product can technically provide cash. It is whether the money is being kept in the right place for the right purpose.
A Savings Account Is Built for Liquidity
A savings account is designed to hold cash that may be needed quickly. The balance is visible, withdrawals are straightforward, and the account is not tied to a death-benefit contract. At an FDIC-insured bank, eligible savings deposits can also receive federal deposit-insurance protection up to applicable limits and ownership-category rules. Life insurance policies are not FDIC-insured deposit products.
That liquidity is exactly what makes savings useful for emergencies. The household does not have to consider a policy loan, surrender charge, or reduced death benefit before using the money.
An emergency fund should therefore be judged by accessibility and safety, not by long-term return alone. If the family would hesitate to access the money during a real emergency, it may not be functioning as emergency savings.
Permanent Life Insurance Is Built First for Protection
Permanent life insurance is designed first around a death benefit. Cash value develops inside the contract over time and may become a useful secondary feature, but the policy has insurance costs, rules, and a long-term purpose.
That is why whole life insurance cash value should not be compared dollar for dollar with a bank balance in the early years. Premiums are supporting insurance and policy guarantees, not simply being deposited. Early surrender values may be lower than cumulative premiums paid.
The policy can still have value as part of a long-term plan. The mistake is expecting it to do the same job as cash savings. Protection and liquidity are both important, but they should not be confused.
A household can see the difference by assigning each dollar a job. The first several months of essential expenses might stay in a bank savings account because the money must be available on short notice. A permanent policy premium may support a death benefit and long-term cash value, but that money is not serving the same immediate-liquidity role. Retirement contributions may go to another account entirely. When those jobs are separated, the family no longer has to ask whether one product is “better” than another. It can ask whether each product is doing the job it was designed to do.
Cash Value Access Has Rules and Consequences
Accessing cash value can be possible, but the method matters. A policy loan charges interest and can reduce the amount paid to beneficiaries if it remains outstanding. A withdrawal may reduce cash value and the death benefit. A surrender ends the policy and can have tax consequences if the amount received exceeds the owner’s basis, depending on the circumstances.
The owner also needs to consider policy stability. A large loan that remains outstanding can affect values and, in some situations, contribute to lapse risk. That is very different from withdrawing money from a savings account.
Before using cash value, ask for an in-force illustration showing the effect on future values and the death benefit. The decision should be based on the policy after the transaction, not only the cash available today.
Why Early Policy Values May Not Match Premiums Paid
Early policy values may not match premiums paid because permanent insurance is not structured like a deposit account. Insurance costs, acquisition expenses, reserves, and surrender provisions affect the value pattern. Whole-life contracts are generally designed for long-term ownership.
This can surprise buyers who focus on a distant cash-value projection without studying the first five or ten years. If there is a meaningful chance the policy will be surrendered early, those early guaranteed values deserve close attention.
A buyer asking is life insurance worth it should therefore compare the protection value and long-term contract, not only the cash-value return. If the only goal is liquid savings, a life insurance policy may be solving the wrong problem.
Before moving money from savings into a permanent policy, test the household’s liquidity separately. How many months of essential expenses could be covered without borrowing? Are there near-term costs such as home repairs, tuition, taxes, or medical expenses? If the answer shows that cash reserves are thin, the insurance premium may need to be sized more conservatively. A whole life insurance policy can be part of long-term planning, but it should not force the household to use credit for predictable short-term needs. The distinction between liquid cash and policy value should remain clear from the first premium onward.
Use Each Tool for the Job It Was Designed to Do
Savings and permanent insurance can coexist. One can hold accessible emergency cash while the other provides a death benefit and long-term policy value. Retirement accounts can serve another job. Debt reduction serves another. A healthy plan does not force every dollar into one product.
A household might first build a reasonable emergency reserve, then fund retirement priorities, then decide how much permanent insurance fits its long-term protection need. Another household with a lifelong dependent may prioritize permanent coverage earlier. The order depends on circumstances.
MM4I can help separate the jobs before comparing products. Life insurance vs savings account should not end with a winner. It should end with clarity about which dollars need immediate liquidity and which dollars are supporting a long-term insurance contract.
There is also a psychological difference between the two tools. Savings feels available because the balance can be seen and moved quickly. Cash value can look available on a statement, but using it changes an insurance contract. That difference should shape behavior. A family may decide that the emergency fund has a minimum balance that should never be invested or moved into insurance. Once that reserve is established, long-term dollars can be evaluated separately. This discipline prevents a future emergency from forcing an unnecessary policy loan or surrender at the wrong time.
The comparison also becomes clearer when the household names its minimum cash reserve. If the family decides that six months of essential expenses must remain liquid, that amount should not be counted as money available for insurance premiums or policy funding. A rule like this protects the emergency fund from slowly being absorbed into long-term products.
If cash value is part of a future borrowing plan, compare that idea with ordinary borrowing costs and with the effect on the death benefit. Policy loans can be flexible, but interest still accrues and the policy remains responsible for supporting insurance charges. The loan should be evaluated as a financial decision, not described as accessing “your own money for free.”
Frequently Asked Questions
Can whole life cash value replace an emergency fund?
Generally, no. Emergency savings should be readily accessible and separate from an insurance contract. Whole-life cash value can provide options, but loans, withdrawals, and surrender can affect the policy.
Can I withdraw cash value whenever I want?
Access depends on the contract and method. Loans, withdrawals, and surrender have different consequences. Policy loans charge interest, and using value can reduce benefits or affect policy performance.
Is life insurance worth it if I already have savings?
Possibly, if you have a permanent protection need that savings alone does not solve. Savings and life insurance serve different purposes, so having one does not automatically eliminate the need for the other.
Keep Emergency Money Liquid and Insurance Focused on Protection
A savings account and a permanent policy can both contain value, but the similarity ends there. One is built for accessible cash. The other is an insurance contract with long-term value features.
MM4I can help explain where cash value fits without treating it as a substitute for every other financial tool. The strongest plan gives emergency savings, insurance, retirement money, and debt management separate jobs.