

IUL vs Whole Life | Compare Guarantees, Flexibility and Cash Value
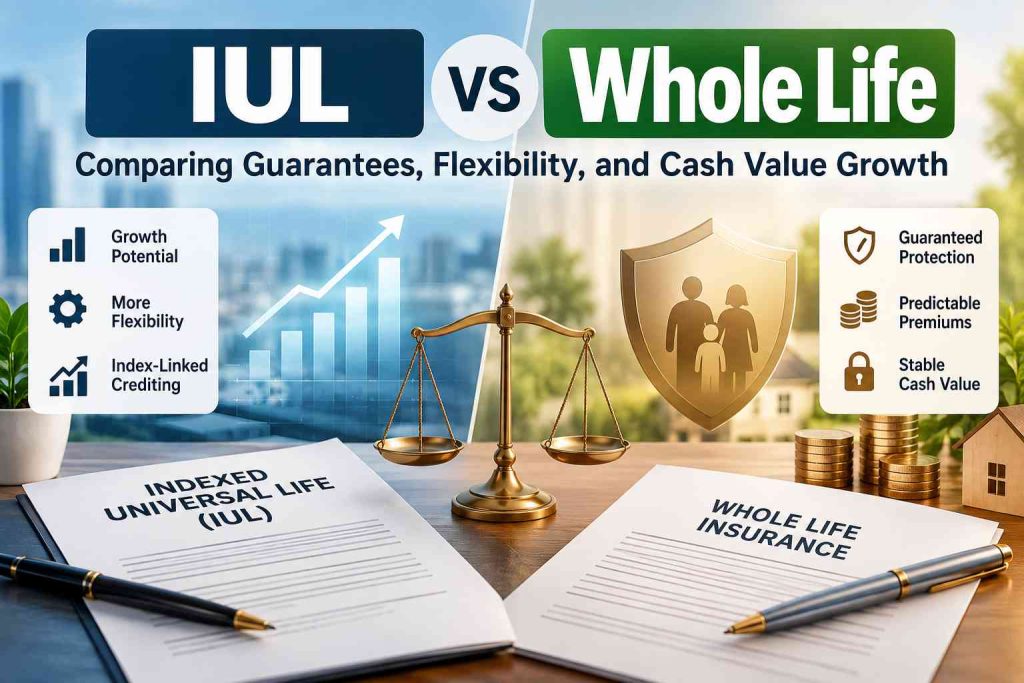
Both whole life insurance and IUL insurance can provide permanent protection and build cash value, but they get there in different ways. That is why IUL vs whole life is not simply a comparison of two projected numbers. It is a comparison of contract structure, guarantees, flexibility, and how much uncertainty the owner is willing to manage.
Imagine two buyers who both want a permanent death benefit. One wants a predictable premium and guaranteed cash-value schedule. The other is comfortable with more moving parts because they value flexible design and index-linked crediting potential. Both may be looking for permanent life insurance, but they are asking the policy to behave differently.
The useful comparison is therefore not, “Which one grows faster?” It is, “Which policy structure fits the owner’s preferences, budget, and willingness to review the contract over time?”
Where Whole Life and IUL Overlap
Whole life and IUL overlap in important ways. Both are forms of permanent insurance. Both can build cash value. Both are designed around a death benefit that may remain in force for life when policy requirements are met. Both can also allow access to policy value through loans or other contract features, with consequences that need to be understood.
Those similarities can make the products look more alike than they really are. The differences appear in premium design, guarantees, cash-value mechanics, and the level of ongoing management.
A buyer should first confirm the amount and duration of the death benefit needed. If the goal itself is not permanent, comparing two permanent products may be the wrong starting point. Once the permanent need is clear, the contract differences become relevant.
Whole Life: More Contractual Predictability
Traditional whole life generally emphasizes contractual predictability. The premium schedule, guaranteed cash values, and guaranteed death benefit are set out in the policy, assuming required premiums are paid and other terms are met. Participating policies may also show dividends, but those dividends are not guaranteed.
This design can appeal to someone who wants fewer assumptions in the core plan. The owner knows the contractual base and can treat non-guaranteed dividends as additional rather than essential.
The trade-off is less flexibility and usually a higher premium commitment than a comparable term policy. Whole life may also develop cash value slowly in early years. The buyer is paying for the permanent structure and guarantees, not for maximum short-term liquidity.
Imagine two illustrations placed on the same table. The whole-life illustration shows a lower guaranteed cash value but also a clear contractual schedule. The IUL illustration shows a higher projected value under a particular crediting assumption, but the guaranteed column is much lower. Calling the IUL “better” because the projected line is higher would mix two different standards. The fair comparison is guaranteed to guaranteed and illustrated to illustrated, with premium, death benefit, and time horizon held constant. That approach can make the choice less exciting, but it makes it far more honest.
IUL: More Moving Parts and More Flexibility
IUL usually introduces more flexibility and more moving parts. Premiums can often be adjusted within contract limits, and cash value may receive interest through an index-linked crediting formula. Caps, participation rates, spreads, floors, and policy charges can all affect results.
That design can appeal to someone who wants permanent coverage but prefers more flexibility than traditional whole life. It also requires more attention. Future cash value depends more heavily on assumptions and actual credited results, and funding decisions can affect sustainability.
An IUL policy should therefore be reviewed periodically. The owner needs to understand current crediting terms, charges, actual values, loans, and whether the planned premium still supports the intended coverage duration. Flexibility is useful only when it is managed.
Compare Cash Value by Guarantees and Assumptions
A common comparison mistake is placing a guaranteed whole-life value beside an optimistic IUL projection. Those are not equivalent numbers. Permanent life insurance cash value should be compared by guarantee level and assumption type.
For whole life, look at guaranteed cash value separately from dividend-based projections. For IUL, separate guaranteed values from illustrated index-linked crediting assumptions. Then compare what premium each design requires and what happens under conservative scenarios.
A buyer should also ask how loans work, how surrender values develop, and how each policy behaves if premiums are reduced. The goal is not to find the highest line on a chart. It is to understand which values are contractual and which depend on future experience.
Before choosing between IUL and whole life, ask each illustration the same five questions. What is guaranteed? What can change? What premium is expected? How much policy management is required? What happens if I take a loan? Put the answers in writing. A buyer who prefers contractual certainty may find whole life easier to own even if an IUL projection is higher. A buyer who values flexible design may accept more uncertainty. The decision should reflect that preference openly instead of hiding it inside projected numbers.
Which Structure Fits Which Preference?
A predictability-focused buyer may prefer whole life. A flexibility-focused buyer who understands index-linked mechanics may prefer IUL. Someone who dislikes complexity may find IUL frustrating. Someone who dislikes a fixed higher premium may find whole life restrictive.
There is no universal winner. The better structure depends on the death-benefit need, budget, desire for guarantees, tolerance for non-guaranteed assumptions, and willingness to manage the policy.
MM4I can help compare IUL vs whole life on the same objective and the same time horizon. That keeps the decision from being driven by a sales illustration. The policy should be chosen because its contract behavior fits the owner, not because one projected line ends higher.
The premium comparison also needs to be fair. A heavily funded IUL and a minimally funded whole-life policy are solving different cash-value objectives. So are a limited-pay whole-life policy and a lifetime-pay design. Ask the adviser to explain why each premium amount was chosen, not simply what the amount is. Then compare the death benefit at the same age and the policy values under conservative assumptions. If one design requires much more premium, identify what additional guarantee or flexibility that extra payment is buying. The decision becomes clearer when every dollar has a purpose.
It can also help to compare the policies under the same ownership objective. If the goal is simply a guaranteed legacy, projected cash value may matter less. If the owner expects to use policy value during life, liquidity, loan provisions, and sensitivity to assumptions become more important. The goal determines which differences deserve the most weight.
The review should include the death-benefit pattern as well. Some policies use level benefits while others can use increasing or adjustable structures. Those choices can affect cost, cash value, and the amount ultimately paid. A whole-life and IUL comparison is only fair when the death-benefit design is understood, not just the face amount printed at the top of the illustration.
One final stress test is to compare what each policy needs from the owner during a weak-crediting or budget-tight year. Whole life may preserve a more predictable contractual path as long as required premiums are paid. IUL insurance may offer more premium flexibility, but that flexibility has to be weighed against charges, actual credited interest, and long-term funding. The comparison should therefore include an in-force review plan, not just the illustration signed on day one.
Frequently Asked Questions
Is IUL better than whole life?
Neither is universally better. Whole life usually emphasizes stronger contractual predictability, while IUL generally offers more flexibility and index-linked crediting mechanics. The better fit depends on the buyer’s priorities.
Which one has more guaranteed cash value?
Whole life commonly has a clearer guaranteed cash-value schedule. IUL guarantees vary by contract and projected values can depend more heavily on crediting assumptions. Always compare guaranteed columns separately.
Which policy requires more ongoing monitoring?
IUL generally requires more monitoring because funding, policy charges, and index-crediting terms affect long-term performance. Traditional whole life tends to require fewer ongoing funding decisions.
Compare the Contracts, Not the Best-Case Charts
Whole life and IUL can both solve a permanent protection need, but they ask different things from the owner. Whole life generally asks for a larger predictable commitment. IUL generally asks for more understanding and ongoing attention.
MM4I can help compare the two using guarantees, conservative assumptions, and the same protection goal. A strong choice should still make sense even when the most optimistic projection is removed.