

Indexed Universal Life Insurance Explained | How IUL Works
Indexed universal life insurance can reference a market index without the policyholder directly investing in that index. That distinction is the first thing to understand about IUL insurance. The policy is life insurance first. It has a death benefit, policy charges, cash value, and a funding structure. Index-linked crediting is one method the insurer may use to calculate interest credited to certain policy values.
This matters because a market index can rise 12 percent while the policy receives a different credited rate. A cap, participation rate, spread, floor, crediting period, or other contract feature may change the result. Policy charges are separate from credited interest, so a year with no negative index credit does not mean cash value cannot decline.
An indexed universal life insurance policy can be useful for someone who wants permanent coverage and is comfortable with a more complex contract. It should not be presented as a stock-market account with life insurance attached.
IUL Is Life Insurance First
IUL belongs to the types of permanent life insurance. Its primary purpose is still life insurance coverage. Premiums fund the policy, charges are deducted, and remaining policy value can receive interest under the contract’s crediting methods. The death benefit and policy sustainability should be understood before anyone focuses on an index illustration.
This order matters because IUL is sometimes marketed around projected cash value. A buyer may see a long upward curve and forget that the policy must first support insurance charges. The actual result depends on funding, charges, credited interest, loans, and contract guarantees.
A useful first question is, “What premium is intended to keep this coverage in force under conservative assumptions?” If the answer depends on one optimistic credited rate, the design deserves more stress testing.
How Index-Linked Crediting Works at a High Level
Index-linked crediting usually begins with the movement of a specified external index over a stated period. The contract then applies its own formula. That formula may include a cap, participation rate, spread, floor, or other feature. Different segments can use different methods.
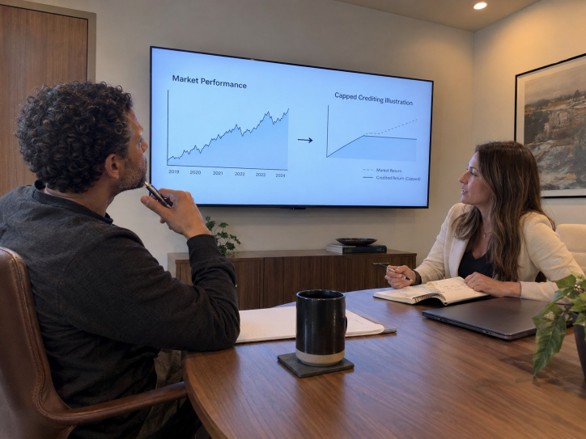
For example, a cap can limit how much of a positive index change is used in the crediting calculation. A participation rate can determine what percentage of an index gain is considered. A spread can reduce the credited result by a stated amount. These terms vary by product and can change according to contract provisions.
The policyholder does not receive the index itself. Dividends from the index are typically not the same as direct ownership of the underlying securities. What matters is the policy’s crediting formula, not the headline market return.
Suppose an index rises strongly during a one-year segment, but the policy has a cap that limits the credited rate. The policyholder may receive a positive credit that is lower than the index gain. In another year, the index may be flat or negative and the segment may receive a floor-based credit of zero, while policy charges are still deducted. Looking at only the index chart would miss both of those outcomes. A good IUL review therefore tracks three separate lines: the index movement, the crediting formula, and the policy value after charges. That simple separation can prevent many misunderstandings.
Why the Index Return Is Not the Policy Return
The index return is not the policy return because several layers sit between them. First, the contract converts the index movement into a credited rate. Then policy charges continue to be deducted. The result affects cash value, but it is not the same thing as owning an index fund.
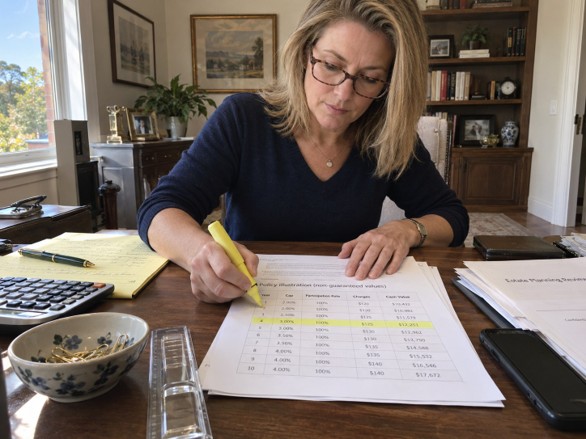
This is why an IUL illustration needs careful reading. A projected value may assume a particular credited rate for many years. The NAIC updated illustration guidance for index-based life policies, including enhanced consumer-protection disclosures effective in 2026, precisely because illustrated outcomes can be sensitive to assumptions.
The buyer should identify the guaranteed assumptions, the illustrated assumptions, current caps or participation rates, and the policy charges. If those concepts are not clear, the projected retirement-age value should not drive the decision.
Funding and Ongoing Policy Reviews Matter
IUL sustainability depends on funding and ongoing review. If premiums are lower than planned, credited interest is weaker, charges rise, or loans reduce values, the policy may need additional funding to remain on track. A strong first-year illustration does not eliminate that responsibility.
Annual statements can show actual credited interest, charges, loans, and cash value. An in-force illustration can then project the policy using current values and assumptions. That is especially useful after a premium change, loan, withdrawal, or major change in crediting parameters.
Permanent life insurance cash value should support the insurance plan, not distract from it. If the owner is relying on future cash value for a major goal, the policy deserves more frequent review because the path is not guaranteed in the same way as a fixed contractual value.
Before relying on an IUL illustration, request the page that explains the crediting method and the page that separates guaranteed from non-guaranteed values. Ask whether caps, participation rates, spreads, multipliers, or bonuses can change. Then ask the adviser to model lower credited rates and a policy loan. An indexed universal life insurance policy should be understandable under an ordinary scenario, not only under the sales illustration. If the policy is expected to support future supplemental income, the owner should also understand what happens if loans remain outstanding and the policy later performs below expectations.
Who Should Consider Learning More About IUL
IUL may be worth learning about for someone who wants permanent coverage, appreciates flexible design, and is willing to understand index-linked mechanics. It may be less suitable for someone who wants simple guarantees and does not want to monitor funding.
The buyer should be comfortable asking technical questions. What index is used? What is the current cap or participation rate? Can those terms change? What are the guaranteed minimums? How do charges work? What premium supports the intended duration under conservative assumptions?
MM4I can help slow the conversation down and separate the insurance need from the projected cash-value story. An indexed universal life insurance policy should be chosen because the death-benefit need, funding plan, and contract structure fit, not because a chart looks similar to stock-market growth.
IUL buyers should also separate current parameters from contractual limits. The cap shown today may not be the cap used ten years from now if the contract allows the insurer to change it within stated bounds. The same can apply to participation rates, spreads, or other features. Ask which values are guaranteed minimums or maximums and which are declared currently. Then keep copies of the original illustration and annual statements. That record makes future reviews more meaningful because the owner can see how the crediting environment and policy values have changed over time instead of relying on memory.
The owner should also know which illustrated features are optional riders and which belong to the base policy. Some riders can change charges, benefits, or cash-value behavior. Ask what happens if a rider is removed later and whether its cost is guaranteed. A clean IUL comparison separates base-policy mechanics from optional enhancements.
Frequently Asked Questions
Does IUL invest directly in the stock market?
No. IUL uses an index-linked crediting formula, but the policyholder does not directly own the index through the policy. Caps, participation rates, spreads, and other contract terms can make credited interest different from the index return.
Can an indexed universal life policy lose cash value?
Yes, cash value can decline because policy charges continue even when index-linked crediting is low or zero. Loans, withdrawals, underfunding, and other policy events can also reduce value.
What are caps and participation rates in IUL insurance?
A cap can limit the positive index change used in the crediting formula. A participation rate can determine how much of an index gain is considered. The exact mechanics depend on the contract.
Understand the Formula Before the Projection
IUL becomes easier to evaluate when the order is correct: protection need first, funding second, charges third, crediting formula fourth, projected value last. Reversing that order can make an illustration look like something the contract is not.
MM4I can help compare IUL insurance using current contract terms and conservative assumptions. A policy should still make sense when the market story is removed and only the insurance structure remains.