
HMO vs PPO vs EPO vs POS: Which Health Plan Gives You the Right Kind of Freedom?
Choosing between an HMO, PPO, EPO, and POS plan is really a decision about how much provider freedom you want and how much structure you are comfortable accepting. The letters do not tell you whether the doctors are better or whether the plan is Bronze or Gold. They describe how the health insurance network works and what happens when you go outside it.
That distinction matters because a plan can look excellent on premium and deductible but still be a poor fit if the member’s doctors, hospital, therapist, or pharmacy are outside the network. For many people, network rules affect daily life more often than the metal level printed on the plan.
First Understand What a Health Insurance Network Is
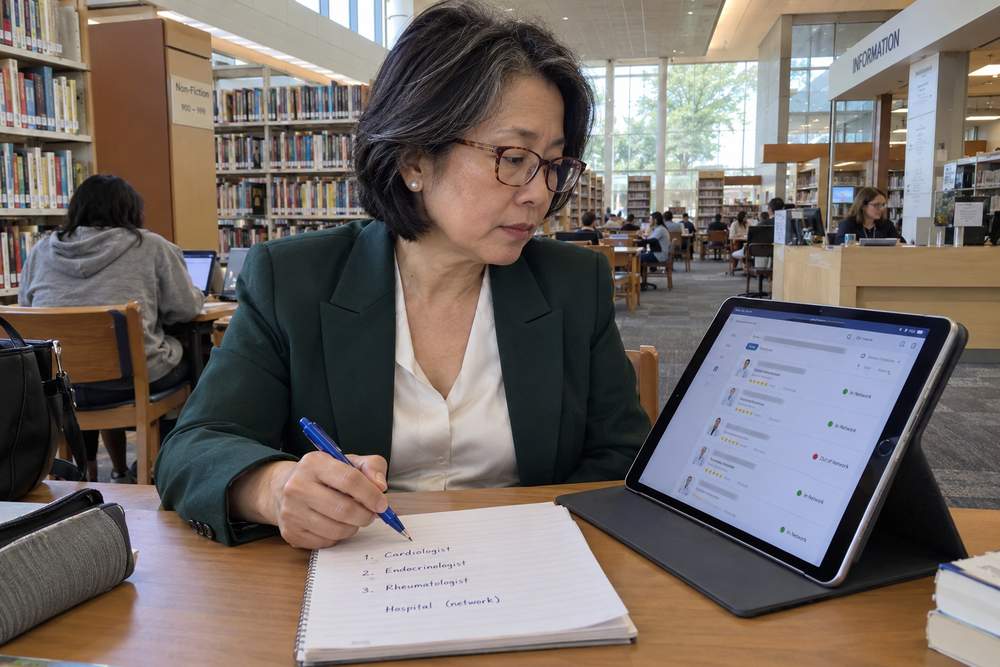
A health insurance network is the group of doctors, hospitals, pharmacies, laboratories, imaging centers, and other providers that have contracts with the plan. Those providers generally agree to negotiated prices and plan rules. Members usually pay less when they stay in network because the plan’s negotiated rates and normal cost-sharing structure apply.
Going out of network can mean higher cost sharing, no routine coverage at all, or exposure to charges beyond the plan’s allowed amount depending on the plan and situation. That is why checking only the insurance company name is not enough. The exact plan and network must be verified.
HMO: More Structure and a Stronger Network Focus
A Health Maintenance Organization usually limits routine coverage to providers that work with or contract with the HMO, except for emergencies. HMOs often emphasize coordinated care and may require members to live or work in a service area. Some HMOs use a primary care doctor to coordinate specialists, although referral rules vary by plan.
An HMO can work well for someone who is comfortable receiving nearly all care inside one system and does not expect to use out-of-network physicians. The trade-off is that a favorite specialist or hospital outside that network may not be covered for routine care.
PPO: More Provider Freedom at a Price
A Preferred Provider Organization generally allows members to use both in-network and out-of-network providers. In-network care costs less, while out-of-network care usually costs more. PPOs generally allow specialist visits without a referral, which can make them attractive to people who want broader provider access.
That flexibility does not mean every doctor is equally affordable. The out-of-network deductible and coinsurance can be much higher, and balance billing may apply when federal or state protections do not. A PPO can be more flexible without being inexpensive.
EPO vs PPO: Similar Freedom Inside the Network, Very Different Outside It
An Exclusive Provider Organization is often easier to understand by comparing EPO vs PPO. An EPO generally requires the member to use doctors, specialists, and hospitals in the plan’s network for covered non-emergency care. A PPO, by contrast, can usually provide some out-of-network coverage at a higher cost.
An EPO may still allow a member to see specialists directly without a referral, depending on the plan. That means someone can have relatively easy access inside the network while still having little or no routine coverage outside it. The strength of the network matters greatly in an EPO.
POS Health Insurance: A Hybrid Structure
Point of Service plans combine parts of HMO and PPO design. Members generally pay less when they use network providers, and POS plans typically require a referral from a primary care doctor before seeing a specialist. Some POS plans also cover out-of-network care at a higher cost.
That can make POS health insurance useful for someone who likes primary-care coordination but wants at least some ability to leave the network. The details are contract-specific, so the referral and out-of-network rules should be checked before enrollment.
A Side-by-Side Way to Think About the Four Plan Types
An HMO usually emphasizes in-network care and may use primary-care coordination. A PPO generally offers the most routine out-of-network flexibility and does not normally require specialist referrals. An EPO usually limits non-emergency coverage to the network but may permit direct specialist access. A POS plan usually combines network discounts and referral requirements with some out-of-network option.
Those are general patterns, not promises. The Summary of Benefits and Coverage, provider directory, and plan documents control. Two plans carrying the same three-letter label can still differ in premium, deductible, specialist rules, and network size.
Check the Doctors and Facilities You Actually Use
Before enrolling, search for your primary doctor, regular specialists, preferred hospital, urgent care center, mental health providers, pharmacy, laboratory, and imaging center. If a particular children’s hospital, cancer center, or specialty clinic matters to your family, confirm it directly rather than assuming the whole health system participates.
Do not rely only on a provider saying, ‘We take that insurance.’ A medical office may accept one network from an insurer but not another. Verify the exact plan name with both the insurer’s current directory and the provider’s billing office, and keep notes or screenshots when the network decision is important.
Do Not Confuse Referrals With Prior Authorization
A referral and prior authorization are different rules. A referral is generally an order or direction from a primary care provider to see a specialist. Prior authorization is approval from the health plan for a service, procedure, medication, or other covered item before it is provided. A plan can require one, both, or neither depending on the service.
This distinction matters when comparing types of health insurance plans. A PPO may let a member see a specialist without a referral but still require prior authorization for an MRI or surgery. An HMO may require a referral and separate authorization. Reading both the referral rules and utilization-management rules prevents unpleasant surprises after enrollment.
Use Your Actual Doctors as the Tie Breaker
When comparing the types of health insurance plans, use the doctors, hospitals, and prescriptions you already rely on as a practical test. If HMO vs PPO is the main decision, check whether your primary doctor and preferred specialists participate in each option before comparing the extra flexibility. An EPO vs PPO decision should include the same check, especially because an EPO may offer no routine out of network benefit. The size of the health insurance network matters only if the providers inside it are useful to you.
The same approach helps with POS health insurance. Ask whether referrals are required, whether out of network care is covered, and how much more that flexibility costs. If two plans seem close, repeat the HMO vs PPO or EPO vs PPO comparison using one realistic year of care. Looking at the actual health insurance network and the rules you would follow is more useful than choosing between the types of health insurance plans based only on the acronym. POS health insurance can be a reasonable middle ground, but only when its referral and network rules match how you prefer to receive care.
Frequently Asked Questions
Is a PPO always better than an HMO?
No. A PPO generally offers more provider flexibility, but an HMO may cost less or provide a network that already includes every provider you need. The better choice depends on the actual doctors, services, and costs involved.
Can an EPO cover an emergency outside its network?
Yes, emergency care is treated differently from routine out-of-network care. EPOs generally cover emergency services even when the emergency provider is outside the normal network, subject to the plan and federal protections.
Does a PPO mean every doctor is covered?
No. A PPO may provide out-of-network benefits, but the member usually pays more and the provider may be able to bill amounts not covered by the plan when surprise-billing protections do not apply.
Choose the Network Structure Around Real Life
The HMO vs PPO decision is not about which acronym sounds better. The same is true of EPO vs PPO or POS health insurance. Start with the doctors and facilities you need, decide how much out-of-network flexibility matters, and then compare the cost of getting that freedom. A strong network fit can be worth more than a small difference in premium.