
Your Health Insurance Premium Is Only the Beginning: What You’ll Really Pay for Care
A health insurance plan can look affordable when the monthly premium is the only number getting attention. Then the first specialist visit, scan, or prescription arrives and the real cost structure becomes clearer. The premium keeps the policy active, but it is only one part of what a household may spend during the year.
The better way to compare health insurance is to look at the premium, deductible, copays, coinsurance, and out of pocket maximum together. Two plans can have very different monthly prices and still produce the opposite result once someone actually starts using medical care.
Start With the Health Insurance Premium
The health insurance premium is the amount paid to keep coverage in force. It is usually charged every month whether the person uses care or not. Marketplace enrollees who qualify for a premium tax credit may pay less than the plan’s full listed premium, so the after-credit premium is the number that matters for a realistic comparison.
A low premium can be useful when monthly cash flow is the priority, but it should never be treated as the total cost of the plan. HealthCare.gov specifically warns that the lowest-premium option may not be the best fit for someone who expects to use a lot of care. A slightly higher premium can sometimes come with a much lower deductible or lower cost sharing.
What the Health Insurance Deductible Actually Means
A health insurance deductible is the amount a member generally pays for services that are subject to the deductible before the plan begins sharing those particular costs. If a plan has a $2,000 deductible, that does not mean every service costs the full negotiated amount until exactly $2,000 is reached. Some services can be covered before the deductible, and Marketplace plans cover certain preventive services without requiring the deductible first.
Plans can also have more than one deductible. Prescription drugs may have their own deductible, and family plans often show both individual and family deductible amounts. The Summary of Benefits and Coverage is the best place to see which services are subject to which deductible instead of assuming one number controls everything.
Copay vs Coinsurance: Fixed Amount Versus Percentage
A copay is usually a fixed dollar amount for a covered service. A plan might charge $35 for a primary care visit or $60 for a specialist. Coinsurance is different because it is a percentage of the plan’s allowed amount. If the allowed amount for a covered service is $1,000 and the member owes 20% coinsurance, the member’s share is $200 after the applicable deductible rules have been satisfied.
That is why the copay vs coinsurance distinction matters when estimating larger expenses. A $40 copay is easy to understand before an appointment. Twenty percent coinsurance on imaging, outpatient surgery, or another expensive service can be harder to predict because the final allowed amount may not be obvious in advance.
The Out of Pocket Maximum Is the Ceiling for Qualifying Cost Sharing
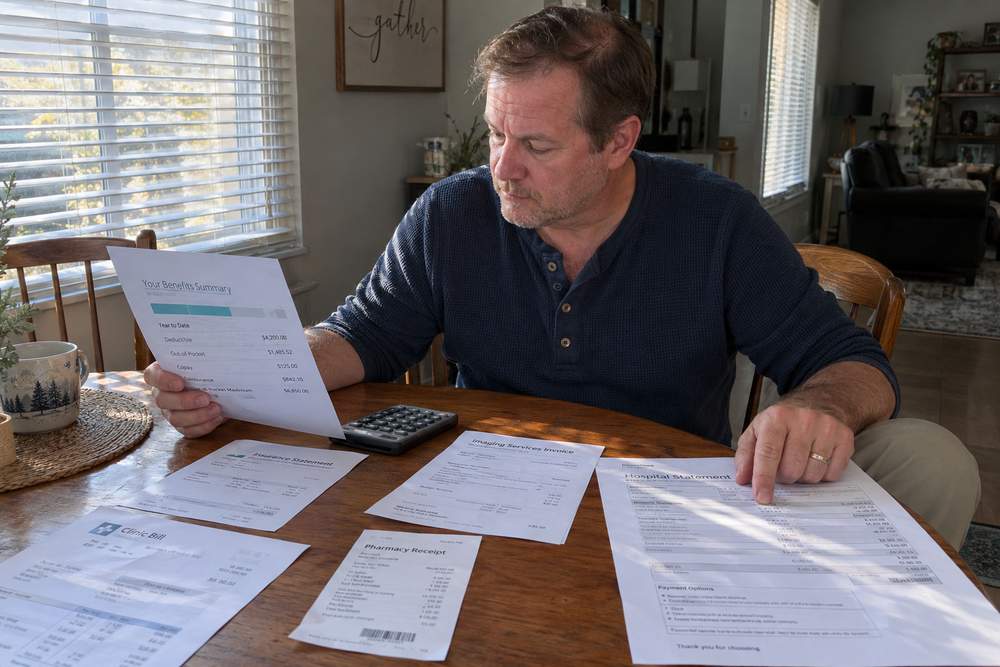
The out of pocket maximum is the most a member generally has to pay during the plan year for covered, in-network cost sharing. Deductibles, qualifying copays, and qualifying coinsurance usually count toward it. Once that limit is reached, the plan generally pays 100% of covered in-network benefits for the rest of that plan year.
The limit does not mean every dollar spent on health care counts. Monthly premiums do not count. Noncovered services do not count. Out-of-network charges and amounts above the plan’s allowed amount generally do not count toward the Marketplace in-network limit. For 2027, the federal Marketplace says a plan’s out-of-pocket limit can be no more than $12,000 for an individual or $24,000 for a family, although many plans set lower limits.
Walk Through One Medical Year From Beginning to End
Imagine Dana has a plan with a $2,000 deductible, 20% coinsurance after the deductible, and a $6,500 out-of-pocket maximum. In January she pays her monthly premium and has a preventive checkup that qualifies for no-cost preventive coverage. In April she needs diagnostic imaging and pays the negotiated amount because she has not yet met the deductible.
By summer, additional covered care brings her deductible total to $2,000. Future covered services subject to coinsurance may then be split between Dana and the insurer. If her qualifying in-network cost sharing later reaches $6,500, the plan generally pays the full covered in-network amount for the rest of the plan year. Her premiums still continue because they are the price of keeping the policy active.
Why the Lowest-Premium Plan Can Cost More
Suppose Plan A has a lower monthly premium but a $7,000 deductible and higher coinsurance, while Plan B costs more each month but has a $2,000 deductible and lower cost sharing. A person who rarely uses care might value Plan A’s lower fixed monthly cost. Someone expecting regular specialist visits, therapy, imaging, or an outpatient procedure could spend less overall with Plan B despite paying more each month.
The right comparison depends on expected use, prescription needs, emergency savings, family size, premium assistance, and the worst-case amount the household could realistically absorb. No single premium or deductible number can answer all of those questions.
What to Compare Before Choosing a Plan
A practical comparison should include the annual premium after any tax credit, the medical deductible, any prescription deductible, copays, coinsurance, the out-of-pocket maximum, the provider network, and the cost of regular prescriptions. Looking at those items together gives a better picture of both normal-year spending and a high-medical-use year.
If one plan looks cheaper only because the monthly premium is lower, calculate what happens when care is actually used. Health insurance becomes much easier to compare once the premium is treated as the beginning of the cost discussion rather than the end of it.
Use Low-, Medium-, and High-Use Scenarios Before You Enroll
A simple way to compare plans is to run three scenarios instead of trying to predict the exact future. In a low-use year, add the annual premium to a few routine visits and regular prescriptions. In a medium-use year, add specialist care, labs, imaging, or therapy. In a high-use year, compare the annual premium plus the plan’s out-of-pocket maximum for covered in-network care.
This approach does not predict what will happen, but it exposes the trade-off. A plan with a lower premium may win in the low-use scenario and lose badly in the high-use scenario. The best plan is the one whose cost pattern fits both the household’s expected care and its ability to absorb an unexpected medical year.
Run One Final Cost Check Before Enrolling
Before choosing a plan, put the full year on one page. Start with the health insurance premium for all 12 months, then list the health insurance deductible, routine copays, likely coinsurance, and the out of pocket maximum. This makes the comparison more realistic than looking at the monthly price alone. It also makes copay vs coinsurance easier to understand because you can attach each type of cost sharing to services you may actually use, such as primary care, specialist visits, imaging, therapy, or prescriptions.
Frequently Asked Questions
Does my health insurance premium count toward my deductible?
No. The premium is what you pay to keep coverage active. It does not normally count toward the deductible or the Marketplace out-of-pocket maximum.
Does meeting the deductible mean medical care becomes free?
Usually not. After the deductible, a plan may still require copays or coinsurance until the applicable out-of-pocket maximum is reached.
Does everything I spend count toward the out-of-pocket maximum?
No. Premiums, noncovered services, many out-of-network expenses, and amounts above the plan’s allowed charge generally do not count toward the in-network out-of-pocket limit.
The Best Number Is the One That Matches How You Use Care
A health insurance premium is easy to compare because it appears every month. The harder and more useful comparison is how the plan behaves once medical care starts. Understanding the deductible, copay, coinsurance, and out-of-pocket maximum together is what turns a plan brochure into a realistic estimate of what the year may actually cost.