

Guaranteed Issue vs Simplified Issue Life Insurance | Key Differences
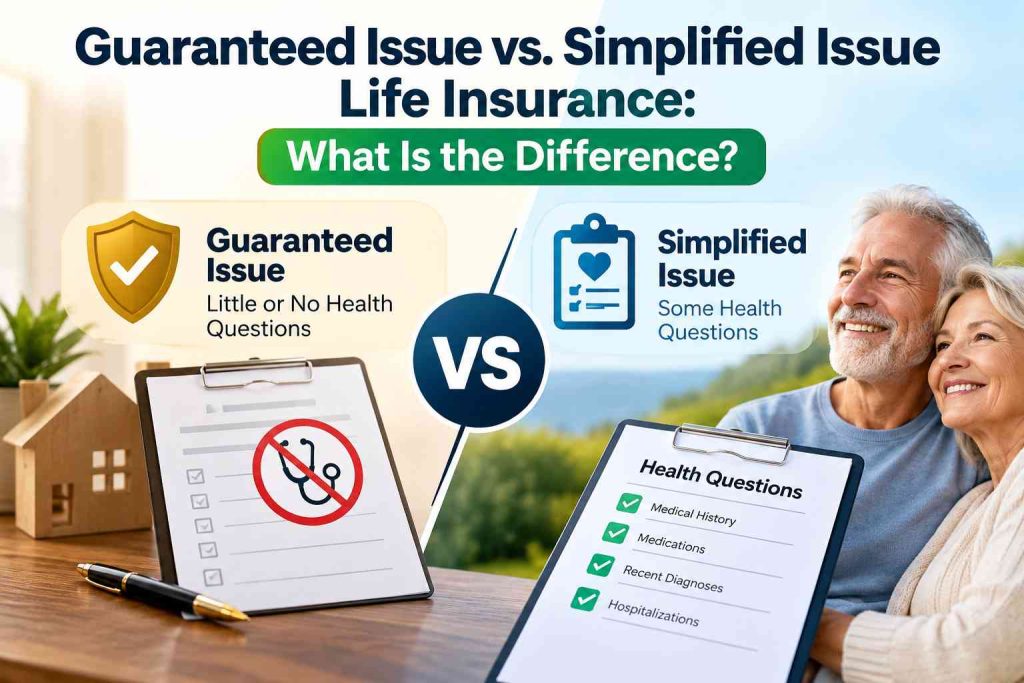
Two policies can both avoid a traditional medical exam and still work very differently. That is the key distinction in guaranteed issue life insurance vs simplified issue life insurance. One route usually still asks health questions and may use underwriting data. The other may accept applicants with little or no health qualification, subject to product eligibility rules.
Those differences affect more than convenience. They can influence premium, benefit size, waiting periods, and how quickly a policy is issued. Someone searching for life insurance with no health questions may assume the easiest application is automatically the best deal. In practice, a healthier applicant may receive stronger pricing or more coverage through simplified issue.
The useful comparison is therefore not just, “Which one asks fewer questions?” It is, “Which underwriting path gives this applicant the right balance of access, price, and protection?”
Simplified Issue Still Uses Health Screening
Simplified issue life insurance usually removes the paramedical exam but still uses health screening. The application may ask about recent diagnoses, hospitalizations, medications, tobacco use, and other conditions. Insurers may also review authorized databases or other records.
Because the carrier has more information about the applicant, simplified issue can sometimes offer more favorable pricing or larger benefits than guaranteed issue. That is not a rule for every product, but it is a reason to avoid skipping straight to the easiest application.
A buyer should answer health questions accurately. The absence of an exam does not remove the duty to provide truthful information. If a question is unclear, it is better to ask for clarification than guess.
Guaranteed Issue Uses Little or No Health Qualification
Guaranteed acceptance life insurance generally uses little or no medical qualification within stated eligibility rules. That can make coverage available to people who may have difficulty qualifying elsewhere. The convenience and accessibility can be valuable, especially when the desired death benefit is modest.
The trade-off is that the insurer knows less about the applicant’s health. Products may therefore have smaller maximum benefits, higher premiums per dollar of coverage, or graded-benefit provisions. Terms vary, so no single guaranteed-issue design should be treated as universal.
Guaranteed does not mean every person in every age range can buy every amount. The applicant still has to meet the product’s age, residency, and other eligibility rules.
A side-by-side example can make the choice easier. A relatively healthy 67-year-old may qualify for a $25,000 simplified-issue policy after answering several health questions. The same person could also qualify for a guaranteed-issue policy with fewer questions, but the premium may be higher and the early natural-death benefit may be graded. If the applicant can qualify for simplified issue, the extra questions may be worth answering. A different applicant with serious health problems may value the guaranteed path more. The better route is the one that produces usable coverage for that person’s health and budget.
Why Guaranteed Issue Often Costs More per Dollar of Coverage
Guaranteed issue often costs more per dollar of coverage because the insurer accepts more uncertainty. Simplified issue can use health information to separate risks more precisely. A healthier applicant may therefore receive a better price after answering questions.
This is why no medical exam life insurance should be compared on total value, not just application effort. If answering a short health questionnaire saves meaningful premium over many years, that extra effort may be worthwhile.
On the other hand, someone with significant health challenges may value access more than price. The purpose of insurance is to secure protection that can realistically be obtained and maintained. The best underwriting path depends on the applicant, not on the number of questions alone.
Understand Graded Benefits and Waiting Periods
Some guaranteed-issue policies use a graded death benefit or waiting period for natural death during the first policy years. The exact structure varies by contract. Accidental death may be treated differently. This is one of the most important provisions to read before buying.
A graded benefit can mean the full stated natural-death benefit is not immediately payable during the initial period. Instead, the policy may return premiums plus an amount defined by the contract or provide another limited benefit.
Because these rules differ, a consumer should never assume that “approved today” means “full natural-death benefit today.” The policy schedule and disclosure documents should make the timing clear.
A buyer can make the comparison concrete with five columns: medical exam, health questions, data checks, full-benefit timing, and premium. Fill in the actual terms for each product rather than relying on the words “simplified” or “guaranteed.” Then add the maximum available benefit and issue-age range. This small table often makes the trade-offs obvious. A policy with fewer questions may have a smaller benefit or a graded period. A policy with more screening may offer better value to someone who can qualify. Labels matter less once the actual terms are visible.
Which Application Route Fits the Situation?
The choice comes down to health profile, desired benefit, urgency, budget, and willingness to answer questions. Someone in reasonably good health may want simplified issue because it can offer stronger value. Someone who cannot qualify through health screening may find guaranteed issue more practical.
Coverage amount also matters. If the goal is final expenses, a smaller guaranteed policy may solve the problem. If the need is larger, other underwriting routes may need to be explored.
MM4I can help compare guaranteed issue life insurance and simplified issue life insurance side by side. The review should include health questions, decision speed, benefit size, premium, and any graded-benefit period. That turns an easy-application decision into a protection decision.
Do not choose guaranteed issue solely because another policy asked an uncomfortable health question. If the applicant can truthfully qualify for simplified issue, the improved pricing or benefit may be meaningful over many years. Conversely, do not keep applying to increasingly strict products if health clearly makes them unrealistic and the family needs coverage soon. An adviser should explain the likely underwriting path before multiple applications are submitted. The objective is not to “beat” underwriting. It is to find the most suitable product the applicant can qualify for honestly and maintain comfortably.
If the buyer is uncertain whether health questions can be answered favorably, review them before submitting the application. An experienced licensed professional can explain the wording without telling the applicant how to hide information. Accurate answers protect the integrity of the application and reduce the risk of problems later.
The policy’s purpose should remain visible throughout the underwriting decision. If the family needs $20,000 for final expenses, a guaranteed-issue policy that reliably provides that amount may be perfectly reasonable even if another product has a more attractive rate. If the need is much larger, the applicant may need to explore different underwriting routes. Product fit comes before application convenience.
If the choice is still close, ask for the actual product summary before applying. Compare the issue-age range, available death-benefit amounts, whether health questions are required, how the insurer uses outside data, whether a graded natural-death benefit applies, and how long premiums are scheduled to continue. Put those details beside the monthly premium rather than treating approval speed as the main feature. That simple review can prevent a buyer from paying more for less coverage merely because a policy was easier to obtain. It also gives MM4I a clearer basis for comparing products without assuming one underwriting route is best for everyone.
Frequently Asked Questions
What is guaranteed issue life insurance?
Guaranteed issue life insurance generally uses little or no health qualification within product eligibility rules. It can be useful for applicants who may have difficulty qualifying through more detailed underwriting.
Does simplified issue life insurance require a medical exam?
Usually not. Simplified issue typically avoids the traditional paramedical exam, but the application can still include health questions and authorized data checks.
What is a graded death benefit?
A graded death benefit limits the amount payable for certain causes of death during an initial period, according to the policy. The exact terms vary, so the contract must be reviewed.
Choose the Underwriting Path, Not Just the Easiest Application
Guaranteed and simplified issue both reduce application friction, but they solve different underwriting problems. A healthier applicant may benefit from answering more questions. A harder-to-insure applicant may value guaranteed access.
MM4I can help compare the trade-offs before an application is submitted. The right route is the one that delivers useful coverage at a sustainable premium with terms the buyer understands.