

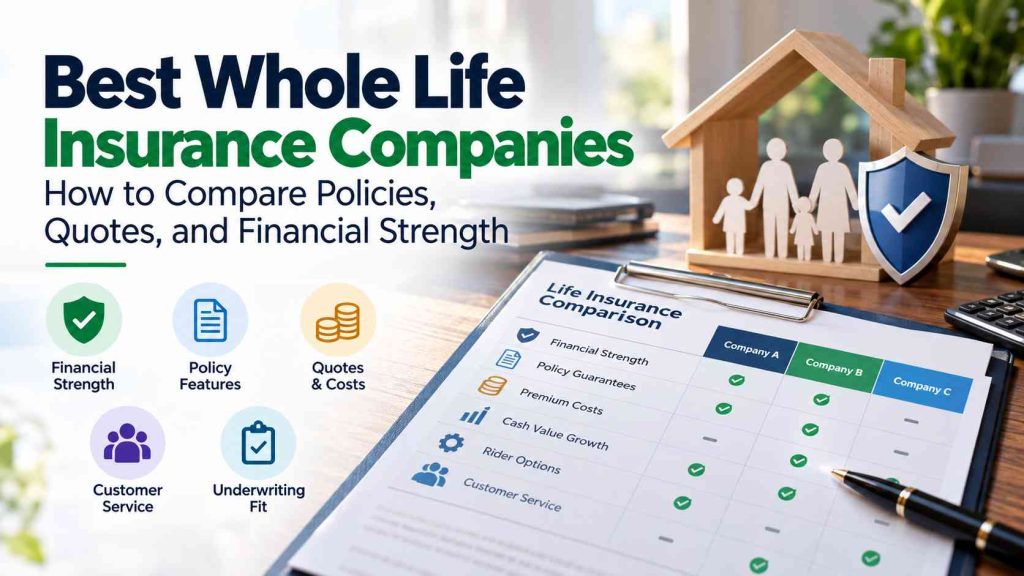
Best Whole Life Insurance Companies | How to Compare Policies
The best whole life insurance cannot be identified from one premium quote. A low price may come with a different policy design. A famous company name does not tell you whether the underwriting will be favorable. A high projected value may depend on assumptions that are not guaranteed.
That is why comparing whole life insurance companies should start with a framework instead of a ranking. Financial strength matters because the insurer may be responsible for the policy for decades. The contract matters because guarantees, riders, premium schedules, and cash values differ. Service matters because owners may need help with beneficiary changes, loans, billing, and claims many years after purchase.
A useful comparison asks, “Which company and policy fit this person, this budget, and this purpose?” That question is more durable than a list of the best life insurance companies that can become outdated as products, ratings, and underwriting change.
Start With Financial Strength and Claims-Paying Ability
Life insurance is a long-duration promise, so financial strength deserves attention. Independent rating agencies evaluate insurers using their own methods and scales. Those ratings can help consumers understand the agency’s view of an insurer’s financial condition, but they are not a guarantee that every claim or policy outcome will be perfect.
Do not compare letter grades across agencies as if they use the same scale. An A from one organization may not mean the same thing as an A from another. Look at the full rating scale, the date of the rating, and whether the rating applies to the issuing insurance company rather than a parent brand.
Financial strength is one part of the decision, not the whole decision. A highly rated insurer can still offer a policy that is poorly matched to a buyer’s goal. The contract and underwriting offer must still be evaluated.
Compare the Policy, Not Just the Company Name
Company reputation matters, but the policy details decide how the coverage behaves. Compare guaranteed premiums, guaranteed cash values, death-benefit guarantees, rider availability, surrender schedules, and whether the policy participates in dividends. If dividends are illustrated, remember that they are not guaranteed.
Underwriting fit can also change the result. One insurer may classify an applicant more favorably than another because companies use different underwriting guidelines. That can change the premium or the amount of coverage available.
The best life insurance companies for one person may therefore be different for someone else. A buyer with a specific medical history, occupation, travel pattern, or family history may receive materially different offers from different carriers. The comparison should include the approved underwriting class, not only the brochure.
A disciplined shopping process can narrow the field without publishing a permanent “top five” list. Start with several financially credible insurers that offer the type of whole-life design being considered. Request quotes using the same age, health assumptions, death benefit, riders, and premium schedule. Record each approved underwriting class. Then compare guaranteed values at the same policy years and place non-guaranteed projections in a separate column. Finally, review service options and any carrier-specific features that matter to the buyer. This process may produce a different winner for two people, which is exactly why a static ranking is less useful than a repeatable method.
Read Whole Life Insurance Quotes Side by Side
Whole life insurance quotes should be compared on equal assumptions. Use the same death benefit, age, sex where applicable to pricing, tobacco status, premium schedule, and rider configuration. If one illustration is heavily funded and another is designed for the minimum scheduled premium, the projected cash values are not an apples-to-apples comparison.
Then separate guaranteed from non-guaranteed values. A quote with a larger projected number may simply be using a different dividend assumption. That does not make it wrong, but it changes what the number means.
A simple comparison worksheet can help: premium, guaranteed death benefit, guaranteed cash value at selected years, projected values, surrender value, riders, and underwriting class. When those rows are aligned, differences become easier to understand.
Service and Policy Management Matter for Decades
Policy management can last longer than the original sales relationship. During that time, an owner may change beneficiaries, update ownership, request a loan, adjust billing, ask for an in-force illustration, or file a claim through the family. The quality and accessibility of service can therefore matter for decades.
Digital tools are helpful, but they are not the only measure. Some buyers want an adviser they can call. Others value a strong online portal and fast document access. Business owners may care about ownership and beneficiary administration. Families may care about clear claims support.
When comparing life insurance companies, ask how routine service works before there is a problem. A policy is easier to own when statements are clear, support is reachable, and requests are documented.
Once a shortlist is created, verify that the issuing company named on the policy is the company whose strength and service you researched. Large insurance groups can contain several legal entities. Ask for the current rating information, but also read the rating agency’s scale and date. Then compare complaint and service information available through state insurance resources where appropriate. None of those measures replaces the contract, but together they provide a fuller picture. A buyer should be able to explain why both the insurer and the specific policy belong on the shortlist.
What ‘Best’ Should Mean for the Buyer
The word best should mean best fit. That includes the need, budget, underwriting profile, desired guarantees, policy design, service preference, and company strength. A carrier can be excellent and still not be the right match for a particular person.
Avoid rankings that present one company as universally superior without a current methodology. Products change. Ratings change. Underwriting niches change. What matters is the evidence available at the time of purchase.
MM4I can help compare whole life insurance companies without turning the process into a popularity contest. The useful outcome is a shortlist of credible insurers and policies that fit the same defined need. From there, approved quotes and illustrations can be compared on the same assumptions.
Before making a final choice, request the policy form or specimen contract when available and compare the promises with the illustration. An illustration explains how a policy may perform under stated assumptions; the contract controls the actual rights and obligations. Check the free-look period required in the buyer’s state, beneficiary rules, policy-loan terms, grace provisions, and any rider limitations. If a feature was important in the sales conversation, confirm where it appears in the contract or rider. This step can feel slower than choosing from a quote sheet, but it is exactly what makes a long-term purchase more defensible. The strongest whole life insurance companies should be comfortable with a buyer who wants to understand the documents before committing.
Finally, remember that a company comparison can change over time. A carrier that fits one applicant today may not be the strongest choice for another applicant next year. Underwriting niches, product features, and ratings can change. Save the dated materials used for the decision so the comparison can be understood later.
Frequently Asked Questions
How do I compare whole life insurance companies?
Compare financial strength, policy guarantees, rider options, surrender values, service, underwriting fit, and approved quotes. Use the same coverage amount and assumptions so the comparison is fair.
Should I choose the cheapest whole life insurance quote?
Not necessarily. A lower premium may come with a different design, underwriting class, cash-value pattern, or rider package. The quote should be judged with the policy’s guarantees and purpose.
What financial-strength ratings should I review?
Review current ratings from established rating agencies and understand each agency’s scale. Ratings should be one input among several, not the sole reason for choosing an insurer.
Choose a Company and a Contract Together
The insurer matters because a life policy can last for decades. The contract matters because it determines what the owner is actually buying. A strong comparison looks at both.
MM4I can help organize current quotes, policy guarantees, and company information into one side-by-side review. The goal is not to crown a permanent winner. It is to find a financially credible insurer offering a policy that fits the buyer’s real need.