
Bronze, Silver, Gold, or Platinum? How ACA Metal Levels Change What You Pay
Bronze, Silver, Gold, and Platinum sound like quality rankings. In Marketplace health insurance, they are not. The metal levels describe how costs are generally divided between the plan and the enrollee when covered services are used. A Gold plan does not automatically mean better doctors, and a Bronze plan does not mean lower-quality care.
Understanding the health insurance metal tiers helps separate two different decisions: how much you want to pay every month and how much financial responsibility you are willing to take on when care is needed.
What the Metal Levels Actually Measure
HealthCare.gov currently describes the categories using approximate shares of total covered costs for a standard population. Bronze plans are designed around roughly a 60% plan share and 40% enrollee share, Silver around 70% and 30%, Gold around 80% and 20%, and Platinum around 90% and 10%. These are actuarial averages, not a promise that the insurer will pay exactly that percentage of one person’s medical bills.
The real cost for an individual depends on the plan’s premium, deductible, copays, coinsurance, out-of-pocket maximum, prescriptions, and how much care the person actually uses.
Bronze: Lower Monthly Cost, More Exposure When Care Is Used
Bronze plans generally have lower premiums and higher cost sharing than the richer metal levels. They can appeal to someone who wants to keep the monthly premium down and has enough savings to handle a larger deductible or other expenses if medical care is needed.
That does not mean Bronze is ‘for healthy people.’ A person can be healthy today and still have an accident, emergency, or unexpected diagnosis. The right question is whether the lower monthly premium is worth the higher financial exposure under that specific plan.
Silver: The Category With a Special Extra-Savings Rule
Silver is unique because eligible Marketplace enrollees can receive cost-sharing reductions only through a Silver plan. Those extra savings can reduce deductibles, copays, coinsurance, and the out-of-pocket maximum. Depending on eligibility, an enhanced Silver plan can pay a much larger share of covered costs than a standard Silver plan.
This is why someone who qualifies for cost-sharing reductions should not automatically jump to Gold because it sounds more generous. An enhanced Silver option can sometimes offer stronger cost sharing than a Gold plan while also preserving the premium tax credit.
Gold and Platinum: More Up Front, Less Cost Sharing When Care Is Used
Gold plans generally ask the enrollee to pay more in premium and less when medical care is used. Platinum plans go further, with the plan paying a larger average share of covered costs. These categories may appeal to someone expecting frequent specialist care, therapy, procedures, or other ongoing use.
The higher metal level is not automatically the cheapest overall. A person who rarely uses care may spend more on premiums than they save in cost sharing. The only useful comparison is total expected spending, not the prestige of the metal name.
A More Expensive Metal Does Not Mean a Better Network
Metal level and network type answer different questions. Bronze, Silver, Gold, and Platinum describe the plan’s general cost-sharing design. HMO, PPO, EPO, and POS describe the provider-network structure. A Gold HMO can have a narrower network than a Bronze PPO, and a Bronze plan may include a doctor that a Gold competitor excludes.
That is why ACA marketplace plans should be compared on both cost and access. A lower deductible is not useful if the specialist you need is out of network, and a broad network does not help if the annual cost is unaffordable.
Compare the Same Medical Year Across Different Categories
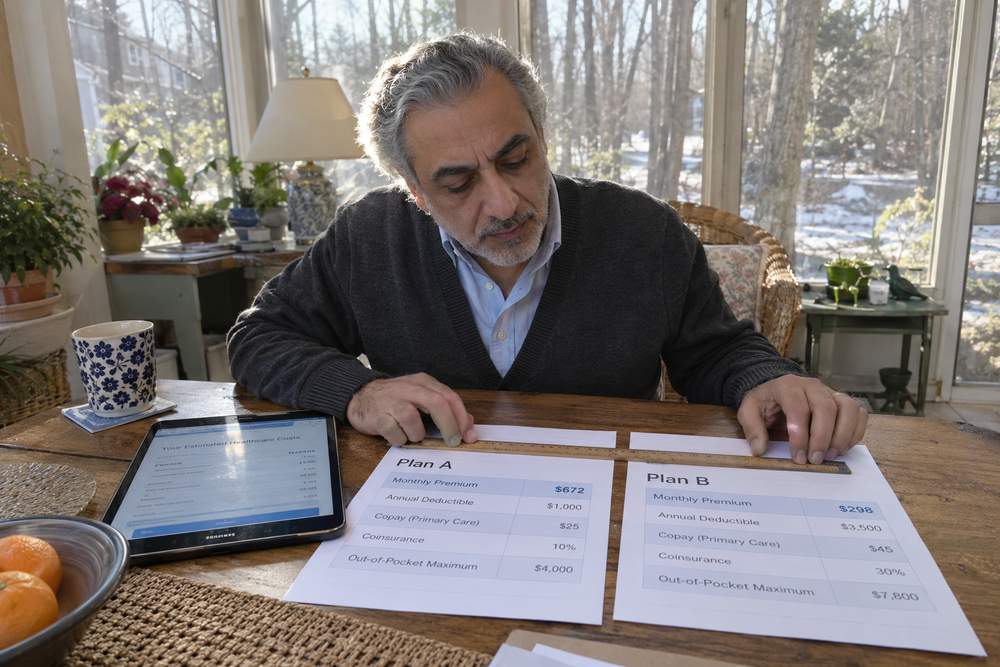
Imagine a person expects twelve specialist visits, several ongoing prescriptions, and one planned outpatient procedure. A Bronze plan may save money in premiums but require more spending before and after the deductible. A Gold plan may cost more each month while reducing the cost of those expected services. If the person also qualifies for Silver cost-sharing reductions, the Silver plan could outperform both.
The numbers should be tested using the actual plan summaries available in the person’s ZIP code. Marketplace tools estimate total yearly costs, but the final decision should still check provider networks and prescription coverage.
What Should Drive the Decision
Compare the annual premium after any premium tax credit, the deductible, out-of-pocket maximum, expected copays and coinsurance, prescription costs, network, and whether cost-sharing reductions are available. If you qualify for extra savings, make sure you evaluate Silver before moving to another category.
Also remember that Marketplace plans in every metal category must cover the same set of essential health benefit categories. The metal level changes how costs are generally shared, not whether the plan is allowed to offer basic ACA-compliant coverage.
Premium Tax Credits and Metal Levels Are Separate Decisions
A premium tax credit lowers the monthly premium for eligible Marketplace enrollees and can generally be applied across eligible metal categories. That means the same household may see discounted Bronze, Silver, and Gold options. The amount of the credit does not turn a Bronze plan into a Silver plan or change the plan’s underlying deductible and cost-sharing design.
Cost-sharing reductions are different. They lower the deductible, copays, coinsurance, and out-of-pocket maximum only when an eligible person enrolls in Silver. That is why a shopper should first check whether extra savings are available, then compare the actual after-credit premium and out-of-pocket structure across the plans that remain.
Use the Actual Plan, Not the Metal Average
The 60/40 or 80/20 metal percentages are useful for understanding the category, but they are not a shortcut for reading the plan. Two Silver plans can have different deductibles, copays, networks, drug formularies, and out-of-pocket maximums while still fitting the Silver actuarial range.
Compare the Summary of Benefits and Coverage for each option you are seriously considering. The metal level narrows the field; the actual plan details determine what you will pay and which doctors and medications you can use.
Turn the Metal Labels Into a Real Cost Comparison
When people compare health insurance marketplace plans, they often begin with a bronze silver gold health insurance search because the labels are easy to recognize. The labels are useful, but the health insurance metal tiers describe how costs are generally shared across a standard population, not what one person will definitely spend. That is why ACA marketplace plans within the same metal level can still have different deductibles, copays, networks, and drug coverage. A good marketplace health insurance comparison always goes one level deeper than the metal name.
Take two or three health insurance marketplace plans and estimate the total cost under a low use, medium use, and high use year. Then compare the premium, deductible, prescriptions, and maximum financial exposure. This turns a bronze silver gold health insurance comparison into a household budget decision instead of a color choice. It also shows why health insurance metal tiers should not be treated as quality ratings. Even among ACA marketplace plans, a lower metal level can be the better fit for one person while a higher level is better for another. Before enrolling in marketplace health insurance, confirm the exact plan details rather than relying on the category average. A final review of health insurance marketplace plans can also make a bronze silver gold health insurance comparison more useful because it ties the label back to real plan costs.
Frequently Asked Questions
Is Gold health insurance better quality than Bronze?
No. The metal categories describe cost sharing, not quality of care. Marketplace quality ratings and provider networks are separate measures.
Why can Silver sometimes be better than Gold?
If you qualify for cost-sharing reductions, those extra savings are available only on Silver plans and can substantially lower the deductible, copays, coinsurance, and out-of-pocket maximum.
Can premium tax credits be used with all metal levels?
If you qualify for a premium tax credit, it can generally be applied to eligible Marketplace plans across metal categories. Cost-sharing reductions are different and require a Silver plan.
Metal Is About Cost Sharing, Not Status
Bronze, Silver, Gold, and Platinum are useful labels only when they are read as a guide to financial structure. The best marketplace health insurance plan is the one that fits the household’s premium budget, expected medical use, network needs, prescriptions, and available savings. The metal name alone cannot make that decision.