

Whole Life vs Universal Life Insurance | Guarantees and Flexibility
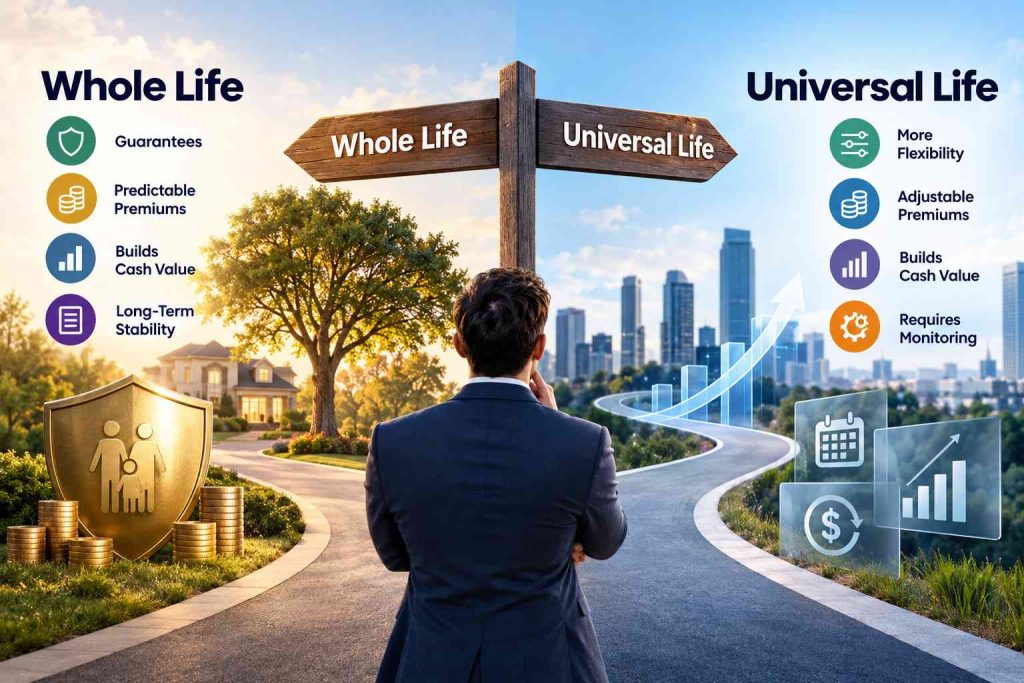
Whole life and universal life can both provide permanent protection and build cash value, but they manage certainty and flexibility in very different ways. That is the core of whole life vs universal life insurance. One structure generally emphasizes a scheduled premium and contractual values. The other gives the owner more flexibility but can require more active funding decisions.
Consider two people buying the same amount of permanent coverage. One wants to know the required premium and guaranteed values with as few moving parts as possible. The other has variable income and wants the ability to adjust premium timing or the death benefit within policy rules. Both may have a valid reason for permanent life insurance. They simply value different features.
The comparison becomes useful when it moves beyond product names. Universal life vs whole life is really a choice about guarantees, flexibility, cash-value mechanics, and how much policy management the owner is willing to accept.
Both Are Permanent – But the Contracts Behave Differently
Both policies are designed for long-term life insurance rather than a fixed term, and both can build cash value. Both also require the owner to understand premiums, policy values, loans, and beneficiary protection. That common ground is important because the products are sometimes presented as if they have nothing in common.
The differences appear in the contract structure. Traditional whole life usually has a scheduled premium and guaranteed cash-value pattern. Universal life separates premiums, charges, and credited interest more explicitly and often allows more variation in funding.
Neither structure automatically produces a better outcome. The more important question is which set of rules is easier for the owner to maintain. A predictable policy that is unaffordable is not a good fit. A flexible policy that the owner never reviews can also become a poor fit.
Whole Life Emphasizes Predictability
Whole life emphasizes predictability. The scheduled premium, guaranteed death benefit, and guaranteed cash values are set out in the contract, assuming policy requirements are met. Participating policies may show dividends, but dividends are not guaranteed.
This structure can appeal to someone who values certainty and does not want to make frequent funding decisions. It can also make long-term budgeting easier because the required payment pattern is clearer.
The trade-off is reduced flexibility. Whole life generally requires a higher premium than term coverage, and changing the policy design later may be more limited than with universal life. Early surrender values can also be disappointing if the owner did not intend to keep the policy long enough.
A practical comparison can use two fictional buyers. Maria wants a permanent death benefit and dislikes financial products that require regular adjustments. She is willing to pay a predictable premium for a simpler contract. David owns a seasonal business and wants more room to vary premium timing, but he is comfortable reviewing statements each year. Whole life may naturally appeal more to Maria, while universal life may deserve a closer look for David. The example is not a recommendation. It shows that the better contract can depend on how a person prefers to manage money, not only on which illustration shows the larger future value.
Universal Life Emphasizes Flexibility
Universal life emphasizes flexibility. Depending on the contract, the owner may be able to vary premium payments or adjust the death benefit. The policy’s cash value is affected by credited interest and charges, which means funding decisions matter.
That flexibility can be attractive to a business owner or professional with variable income. It can also be useful when coverage needs change. However, paying less than planned can reduce the policy’s margin. A lower current value, higher charges, or weaker crediting may require larger future premiums to keep the desired coverage.
Universal life insurance therefore rewards monitoring. Owners should review statements and request in-force illustrations when funding changes. Flexibility is a feature, not a guarantee that every premium pattern will support lifetime coverage.
Compare Cash Value and Policy Management
Cash value should be compared by guarantee level and assumption type. Whole-life illustrations often show guaranteed values plus possible dividends. Universal-life illustrations can show guaranteed and current assumptions related to charges and crediting. Comparing the highest projected value on each page can therefore be misleading.
A better comparison uses the same death benefit and looks at selected years. What is guaranteed? What is projected? What premium is required? What happens under weaker assumptions? How do loans affect the policy?
Policy management is another difference. Whole life tends to require fewer ongoing funding decisions. Universal life may require more attention to actual performance and premium adequacy. The owner should choose the level of complexity they are willing to manage for decades.
A side-by-side worksheet should use the same death benefit, similar underwriting assumptions, and a comparable time horizon. For whole life insurance, record the scheduled premium, guaranteed cash value, guaranteed death benefit, and any non-guaranteed dividend illustration. For universal life insurance, record the planned premium, guaranteed assumptions, current assumptions, charges, and projected duration. Then ask what changes if the owner pays less for two years. The answer can reveal the practical difference between predictability and flexibility more clearly than a long list of product features.
Match the Structure to the Owner’s Preference
A certainty-focused buyer may prefer whole life. They want a clearer premium schedule, contractual cash values, and fewer moving parts. A flexibility-focused buyer may prefer universal life because they want adjustable funding or coverage features and are comfortable reviewing the policy.
Budget still matters. Whole life can be predictable but expensive. Universal life can appear more affordable at first but may require future adjustments depending on design and guarantees. The comparison should include long-term sustainability, not just the first premium.
MM4I can help make the choice practical by putting the two structures side by side. The question is not which policy is more sophisticated. It is which contract matches the owner’s preference for predictability, flexibility, and ongoing management.
The replacement question also deserves attention. If someone already owns whole life and is considering universal life, or vice versa, do not assume switching is automatically an upgrade. The existing policy may have accumulated value, favorable guarantees, or an underwriting advantage that cannot be recreated. A new policy can bring new acquisition costs, surrender schedules, and underwriting. Compare the in-force policy with the proposed policy on the same timeline before replacing anything. Sometimes the better solution is to keep the existing contract and add or adjust coverage rather than start over.
If both structures appear affordable, the decision can come down to behavior. Some people value a contract that asks for the same disciplined payment every year. Others prefer flexibility and are willing to manage it. The policy that matches the owner’s real behavior is often easier to keep than the policy that looks best in theory.
Ask one more practical question: who will notice first if the policy begins to drift from the original plan? With whole life, the answer may be less urgent because the guaranteed schedule is clearer. With universal life, the owner should know which statement values or notices signal that more premium may be needed. A policy is easier to own when the review responsibility is defined before problems appear.
Frequently Asked Questions
Which is more flexible, whole life or universal life?
Universal life is generally more flexible because many policies permit premium or death-benefit adjustments within contract rules. That flexibility can also require more monitoring and careful funding.
Which has more guarantees?
Traditional whole life generally emphasizes stronger scheduled guarantees for premiums and cash values. Universal-life guarantees vary by contract, so the specific policy must be reviewed.
Can whole life and universal life both build cash value?
Yes. Both are forms of permanent insurance and both can build cash value, but they use different premium, guarantee, and crediting structures.
Choose the Structure You Can Maintain
Permanent coverage is a long relationship with a contract. Whole life tends to reward buyers who value predictability. Universal life tends to appeal to buyers who value flexibility and are willing to monitor funding.
MM4I can help compare the guarantees, assumptions, and long-term premium requirements without turning the choice into a product contest. The better structure is the one the owner understands and can realistically support.